
Here’s what’s driving Australian equities this week according to Pendal’s head of equities Crispin Murray. Reported by portfolio specialist Chris Adams.
Concerns over the Delta variant’s potential to derail economic recovery, both domestically and overseas, dominated headlines.
Nevertheless, equity markets remain resilient. The S&P/ASX 300 gained 1.96% and S&P 500 0.96% for the week.
We don’t see this as an unsustainable disconnection between growth concerns and market returns. There are a number of factors providing support, including a strong US earnings season and ample liquidity which is fuelling M&A activity. Concerns over growth have also seen bond yields fall, bolstering returns for growth stocks.
US employment data at the end of the week was a reminder that economic growth may prove more resilient than the market thinks.
COVID – US
The US is bracing for an inevitable rise in cases as Delta takes hold. The main issue is that, unlike in the UK, the rise in new cases is leading to a material increase in headline hospitalisation rates.
The link between vaccination and a less severe infection is holding. However, there are states with low rates of vaccination, leading to a pick up at the headline levels of hospitalisations as new cases surge. We are also mindful that new case numbers are clearly being understated, as people are less likely to get tested.
The impact on mobility is yet to be seen. Mask mandates are being reinstated and are now recommended indoors by the Centre for Disease Control and Prevention (CDC). There is a high degree of resistance to this – from both vaccinated and unvaccinated people. At this point there appears to be no appetite for returning to lockdowns and there has only been limited signs of more subdued economic activity form this wave.
Find out about
Pendal Focus
Australian Share Fund
Crispin Murray,
Head of Equities
We are watching Missouri and Florida closely as some of the first states to experience the Delta wave. Based on the Indian and UK experience cases here could peak around 60-70 days into the wave, which would be by the end of August. There is some risk to this, given it would coincide with the return to school. Nevertheless, signals of a peaking wave in these states could be the trigger for a rotation back to cyclicals.
COVID – China
There are reports that China is facing Delta outbreaks in 17 of its 32 provinces. Beijing faces a similar challenge to Australia in that the political strategy has been elimination of Covid and there are not sufficient people vaccinated. Only 16% of the population is fully vaccinated and 60% have had one dose. Data suggests that the Chinese vaccines are also less effective than the mRNA-based approaches.
China is implementing lockdowns as a result, which of course affects growth. This is dragging on commodities and resources. However, it also means Beijing is more likely to pull the lever of traditional stimulus – property and infrastructure – given consumer demand growth remains muted.
Covid – Australia
The domestic emphasis is on the run rate of vaccinations. This has been accelerated by the shift in recommendation for AstraZeneca.
We are now running at 0.7% of the population being vaccinated each day. Peak rates in places such as Israel and the UK ranged from 0.8% to 1.0% per day. Australia could reach that rate on the current trajectory by the end of this month if people continue to take up AZ, where supply is available.
Nevertheless we go into reporting season with some wariness around domestic cyclicals, given uncertainty over the economic consequences, policy response and likely cautious tone from a number of these companies.
Economics
The narrative of concern around a slow-down seems to be nearing a crescendo – just as we get a reminder that the real US economy is still going well – in the form of jobs data.
- US July payrolls rose 943,000 on the previous month versus expectations of 870,000. The previous months’ result was also revised up by 199,000. Government jobs were an important contributor, but the private sector was also strong driven by leisure and hospitality.
- The Unemployment rate dropped from 5.9% to 5.4% which is real progress to the Fed’s goal of full employment.
- Hourly earnings were also up 0.4% month-on-month and 4.0% year-on-year. Wage growth in leisure and hospitality is now running >12%.
2021 Money Management of the Year Awards
Pendal Australian Shares Portfolio
Winner – SMA Australian Equities
Pendal Property Investment Fund
Winner – Australian Property Securities
This demonstrates ongoing resilience in the US economy, despite the narrative of “peak growth “ and surge in Delta.
There is also capacity for more upside surprise with >5m jobs still not returned. This will become apparent once the holiday season ends, although the Delta strain has likely reduced the pace of this job recovery.
This strength is reflected in shifting expectations around policy. The strong jobs data means consensus now expects the Fed to announce tapering of QE in November and implement it immediately, or in December, rather than waiting until 2022. The market is also now assuming that the pace of tapering will be swifter than was the case a few months ago.
Inflation
Inflationary expectations are also playing a role in this view. There are some indications that the supply bottlenecks which caused the spike in short-term inflation may prove more persistent than first thought. For example, the number of ports seeing capacity issues has actually increased.
Delta’s rise in Asia is also raising concerns for global supply chains if lockdowns remain in place. Anecdotally, US auto dealers are sitting on several million fewer cars in inventory than would normally be the case at this time of year.
In addition to this, survey data indicates US companies currently have more pricing power than we have seen in decades.
The upshot is that inflation concerns are still real, despite what the decrease in bond yields in recent months might suggest.
Markets
The confluence of surging US cases and outbreaks in China exacerbated concerns over global growth and weighed on commodities last week. Brent crude fell -7.4%, iron ore -6.0% and copper -3.0%.
Commodity prices remains largely hostage to Covid sentiment in the near term. This will be tied to the rate of new US cases and hospitalisations, which are likely to deteriorate for at least 2-3 weeks.
Bonds yields may be hitting their lows for the balance of the year. Concerns over growth feel like they are reaching a peak, while several technical supports also look to be near their maximums. The potential for more persistent inflation is also likely to play a role.
While we could not expect yields to fall much lower, we would not be surprised to see bonds holding in near these levels for the rest of the quarter. We don’t expect anywhere near the degree of sell-off seen in Q1 2021.
US earnings season continues to be very strong. The S&P 500 is beating quarterly earnings forecasts by 25%. Re-opening stocks have fared best, beating expectations by 45% on average. However, the stocks have not reacted given concerns over Delta.
Upgraded CY21 earnings expectations means the S&P 500 is now on 21x earnings. This isn’t cheap, but is reasonable given rates. At this point the consensus is only for 5% earnings growth in CY22.
There was significant rotation on the ASX. Concerns over the growth outlook saw Technology (+12.7%), Staples (+2.8%) and Health Care (+2.6%) outperform the benchmark. Technology also got a kicker from Square’s bid for Afterpay (APT, +36.7%).
One key risk heading into reporting season is that the valuation multiple for a lot of growth and quality defensive companies remains elevated, reflecting high expectations. Any disappointment – or impact from lockdowns – leaves them vulnerable.
Stocks
Resource stocks fared worst on the ASX 100 reflecting lower prices. Fortescue Metals (FMG, -7.5%) and Mineral Resources (MIN, -6.4%), both leveraged to iron ore, were the worst performers. Oz Minerals (OZL, -3.3%), Northern Star (NST, -2.7%), BHP (BHP, -2.6%) and Rio Tinto (RIO, -2.5%) were all close behind.
REA Group’s (REA, -1.4%) result was broadly in line. Management’s observation that Sydney listing volumes were down 22% in July should not have surprised anyone. However, it does emphasise the potential impact of near-term operating momentum on the more highly-valued parts of the index, as both it and Domain (DHG, -4.9%) came off.
Santos (STO, 0.0%) and Oil Search (OSH, +3.9%) agreed terms on their proposed merger. We still have limited insight on synergies. However, the combined entity will be better positioned to navigate the on-going energy transition.
APT jumped on the bid and – given that it is now effectively trading as a proxy for Square – continued to benefit from rotation to the latter in the US market. It was the best performer on the ASX 100.
The bid highlights the escalation of the land grab in buy-now-pay-later (BNPL) and in payments more broadly. Square, Paypal, Shopify, Apple and Affirm are all jostling for positions within this system, alongside more traditional banks. The battle-lines are being drawn and competitive intensity is likely to increase. APT’s decision to sell seems a good one in this context.
Other growth stocks performed well mainly driven by thematics. Wisetech (WTC, +7.6%) and Xero (XRO, +6.0%) also did well, the latter announcing measures to drive revenue growth through its app store.
ResMed’s (RMD, +3.2%) result was a good one. The flowgen machine recall by Philips leaves RMD is a strong competitive space and is driving large increases in revenue, although they are running into some supply constraints. There is also some pressure on margins last quarter as a result of rising prices on polymers and components. The stock has been strong and is in a sweet spot. However, we are wary over the degree to which people are capitalising the share gains from Philips.
Finally, it is worth noting that the Federal Court ruled in favour of Chubb Insurance in a dispute over business interruption cover with Star Entertainment (SGR, -2.3%) based on the lack of physical damage. This may help set a precedent for other similar cases.
Find out about Crispin Murray’s Pendal Focus Australian Share Fund
About Crispin Murray and Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia. Crispin’s Pendal Focus Australian Share Fund has beaten the benchmark in 12 years of its 16-year history (after fees), across a range of market conditions.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about Pendal Focus Australian Share Fund here.
Contact a Pendal key account manager here.
Here’s our weekly Bond, Income and Defensive Strategies note from Pendal portfolio manager Tim Hext.
THE latest RBA statement on monetary policy is a great read, not just for thoughts on the economy but for the graphs.
The RBA’s vast team of economists always find new and interesting ways to look at the state of play.
There were several that caught our eye this time.
We are truly in a world of money printing
The first graph below shows how much government bond markets are owned by central banks.
This is the government printing money to finance the government. And still no inflation. Modern Monetary Theory is onto something here.
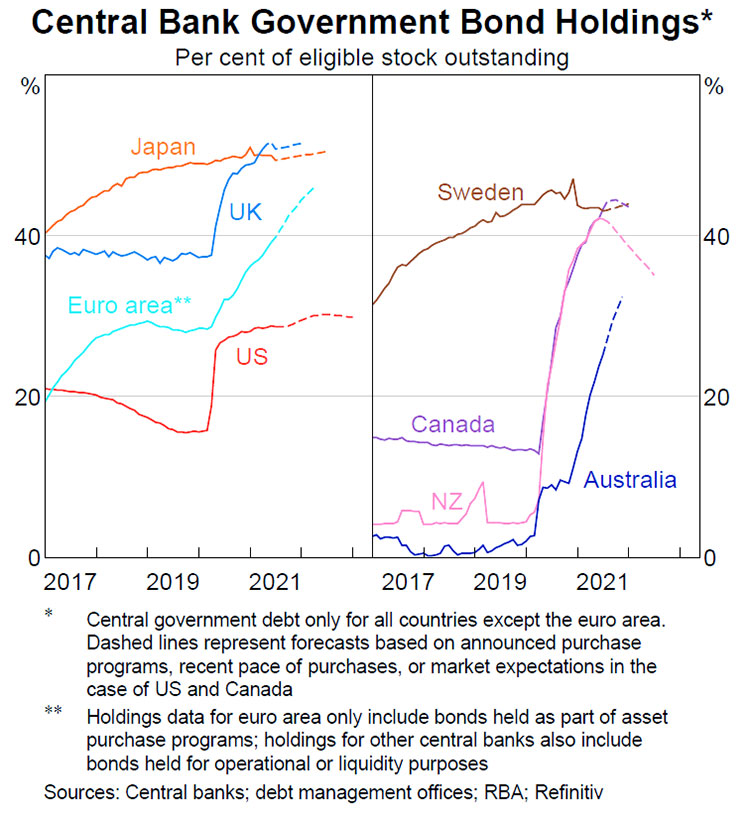
The message from the RBA seems to be: relax, we’re not even in the medals.
These purchases and super-low cash rates are all part of a slow and subtle financial repression.
Rather than having people go backwards nominally, just keep rates below inflation and have savers go backwards in purchasing power.
At first this is not noticed too much. Since growth assets re-rate higher with negative real yields, asset owners sit back happily. This is the period we are still in.
But eventually this will eat away at our standard of living — especially as inflation picks up.
Most of the world’s GDP is opening up and living with 50-60% vaccination rates
This second graph will come as no surprise to locked-down readers.
Australia’s developing country status in vaccines versus our developed peers is shown here. I guess our success and eventual complacency in 2020 came back to bite us in 2021.
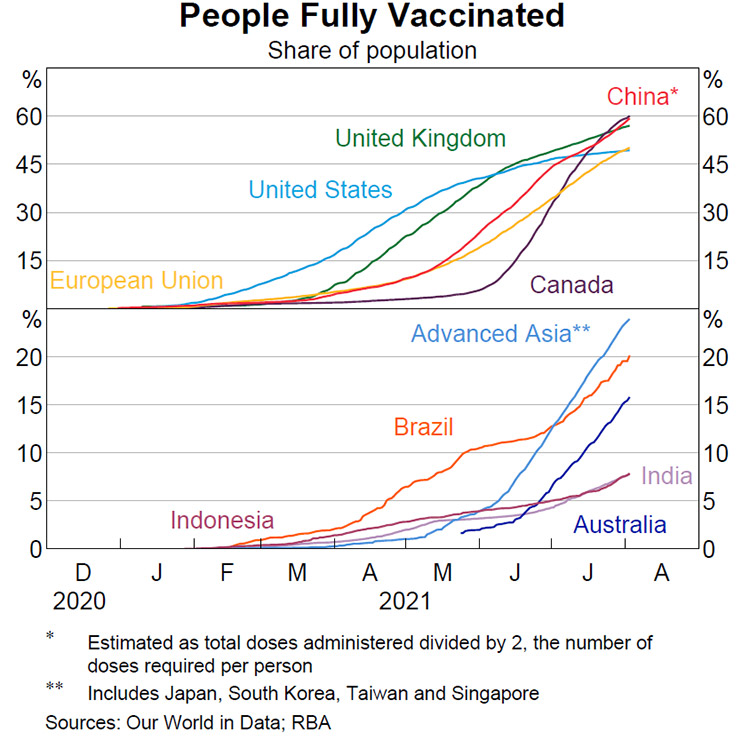
This graph shows that the majority of the world’s GDP is now opening up and living with the virus at around 50-60% vaccination rates.
By 2022 we should be opening and hopefully seeing the end of lockdowns.
Pent-up savings and demand should see a strong rebound in the economy and some wage and price pressures.
Other than that, rates markets have spent the past few weeks treading water — sitting back and once again watching with envy the never-ending riches of equities.

Find out about
Pendal’s Income and Fixed Interest funds
About Tim Hext and Pendal’s Income and Fixed Interest boutique
Tim Hext is a portfolio manager with Pendal’s Income and Fixed Interest team.
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia. In 2020 the team won the Australian Fixed Interest category in the Zenith awards.
With the goal of building the most defensive line of funds in Australia, the team oversees A$22 billion invested across income, composite, pure alpha, global and Australian government strategies.
Find out more about Pendal’s Income and Fixed Interest strategies here
About Pendal Group
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
The cement industry accounts for about 8 per cent of global greenhouse gas emissions. French-based Hoffmann Green Cement has a potentially lucrative solution
- Innovative solution to one of the biggest emissions conundrums
- Potential long-term upside for investors
- Find out more about Regnan Global Equity Impact Solutions
THE cement industry is one of the world’s biggest carbon polluters.
It is the most widely used human-made material across the globe with about 4.6 billion tonnes produced each year. And it’s remained largely the same for centuries.
“The story goes that if the Roman emperors were in the world today, one thing that would still be familiar to them is cement production,” says Maxime Le Floch, an investment analyst focused on equity impact solutions at Regnan.
It’s an industry that hasn’t innovated very much. Until now.
French-based Hoffmann Green Cement Technologies is changing the way cement is manufactured, drastically reducing the amount of greenhouse gases emitted in the process of creating concrete.
“The reason we got interested in the company is because we need to decarbonise the economy,” Le Floch says candidly.
“The cement industry accounts for about 8 per cent of global greenhouse gas emissions. That’s a big share of industrial emissions, which is going to stand out even more as other sectors decarbonise.”

Find out about
Regnan Global Equity Impact Solutions Fund
Hoffmann Green’s breakthrough was to eliminate the use of clinker in the creation of cement.
Clinker is a mix of limestone and minerals that are heated in a kiln as part of the cement making process. This releases enormous amounts of carbon dioxide.
Eliminating clinker substantially reduces the amount of CO2 released into the atmosphere during the production of cement.
“Hoffmann Green reduces the carbon footprint of cement by a factor of five,” Le Floch explains so was an obvious option for Regnan to consider.
Regnan thinks about stocks in terms of impact, value creation, value distribution and value gap. The impact Hoffmann Green can have in terms of reducing carbon emission is clear.
“Most of the innovation happening in the cement industry is incremental, around existing technology. But Hoffmann Green has removed the clinker chemical reaction in making cement and that’s quite dramatic.”
Hoffmann Green also ticks the value creation box, in part because its competitors aren’t innovating fast enough, burdened by existing infrastructure that risks becoming stranded. Cement is generally a relatively localised industry because of costs associated with transporting the product long distances.
“Hoffmann Green can come in, have a product that’s much more radical and better for the environment, and there’s demand for that. They are able to charge about twice the price of normal cement because of the green credentials.”
[Hoffmann] are able to charge about twice the price of normal cement because of the green credentials.
Maxime Le Floch, Regnan investment analyst
Hoffmann Green’s process also means the energy bill to produce cement is lower, reducing the group’s cost base.
“The cost base is quite low. The capital requirements on new sites are much lower than other cement companies. There’s a lot more operating leverage as they scale up,” Le Floch says.
“In terms of value distribution, this is a relatively small company that’s scaling up,” he says. “They’re very committed to sustainability. It’s quite an automated process that doesn’t involve large amounts of industrial heat for instance … so it’s also a much safer process for employees compared to other types of cement making.”
A company like Hoffmann Green should benefit in the future because as they grow, their value proposition will become more evident to customers, who are being pushed to de-carbonise.
“Hoffmann Green is relatively small – a half a billion Euro market cap. It’s the smallest company we have. But as they scale up, we will have the opportunity to scale up,” Le Floch says. “They are in an investment phase. They are building new sites.”
He argues there’s plenty of opportunity for the company. There’s a potential for more sites. There’s also a benefit when carbon prices increase, because customers will be look for low CO2 emission options. And there’s an option for an international licensing model.
Of course, every investment carries risk.
“The key risk is in execution,” Le Floch says. “It’s in delays to building out their manufacturing and production capacity. There is always a technology risk with new processes, though I think that’s reducing over time as they get more confirmation from customers using their cement. And there will be other competitors emerging in the pathway to decarbonisation.”
“But Hoffmann Green has been able to hit its key milestones in terms of its product being validated. There’s a new innovation cycle in the economy around decarbonisation and sustainability more generally … and Hoffmann Green is at the cutting edge.”
About Regnan
Regnan is a responsible investment leader with a long and proud history of providing insight and advice to investors with an interest in long-term, broad-based or values-aligned performance.
Building on that expertise, in 2019 Regnan expanded into responsible investment funds management, backed by the considerable resources of Perpetual Group.
The Regnan Global Equity Impact Solutions Fund invests in mission-driven companies we believe are well placed to solve the world’s biggest problems.
The Regnan Credit Impact Trust (available in Australia only) invests in cash, fixed and floating rate securities where the proceeds create positive environmental and social change. Both funds are distributed by Perpetual Group in Australia.
Find out about Regnan Global Equity Impact Solutions Fund
Find out about Regnan Credit Impact Trust
For more information on these and other responsible investing strategies, contact Head of Regnan and Responsible Investment Distribution Jeremy Dean at jeremy.dean@regnan.com.
Quality oil and gas companies are transforming. That’s where opportunities lie says Pendal’s head of global equities, Ashley Pittard.
- There are strong earnings tailwinds behind oil companies
- Buying into transforming oil giants can be earnings and green positive
- Find out more about Pendal Concentrated Global Share Fund
HOW should investors think about oil companies?
They aren’t the most environmentally friendly companies in an increasingly green world. And they haven’t attracted many investor friends recently with activist shareholders aggressively challenging boards.
Not that the activists have necessarily been wrong.
Banks in the US — the home of ExxonMobil, Chevron and ConocoPhillips — have formed the Net-Zero Banking Alliance, which wants virtually zero lending to carbon producing companies by 2030.
A recent court decision in the Netherlands effectively said Royal Dutch Shell — Europe’s biggest oil company — needs to reduce carbon emissions by 45 per cent by 2030. And in the middle of last month, the European Commission released its Fit for ’55 roadmap to zero carbon emissions in Europe, as a continent, by 2055.
But oil companies comprise more than 6 per cent of the market capitalisation of companies around the globe. Their output, literally, makes the world move around and will be in demand for decades to come.
It’s an investors dilemma, says Ashley Pittard, Pendal’s head of global equities.
“Oil companies will have to limit their capital expenditure which means production growth will be slower and prices will remain strong,” Pittard says.
“And that means oil companies will have significant free cash flow so we should expect buybacks, dividends and investing in greener technology like wind, hydrogen and batteries.”

Find out about
Pendal Concentrated Global Share Fund
Valuations on the companies are compelling, Pittard says, trading around six to eight times earnings.
“They are trading below, or significantly below, their replacement value, and they’re on a dividend yield of 6 per cent. And while much of the rest of the market is at near record levels, oil company prices are flat.”
So, there’s clearly opportunity. But what about the green question?
“It’s better to be in the tent, buying businesses and enacting change via proxy voting then saying we’re just not going to fund these businesses,” Pittard explains.
But that doesn’t mean its okay to buy any oil company.
“We will screen out stocks that structurally that can never change,” Pittard says, giving the example of tobacco companies.
“But some oil companies can change and the best example is TotalEnergies. Over the last five years that have spent a significant amount of their free capital on battery farms, wind farms and gas. They have used their free cash flow to reinvent themselves.”
“Total is already at the front end of being green among the integrated oil companies. They are investing in renewable technology. But other companies are being dragged to the table.”
In essence, investing in oil companies that benefit from the current market conditions, and are using cash flow to shift into renewables is a way of having your cake, and eating it too?
“It’s better to be in the tent, buying businesses and enacting change via proxy voting then saying we’re just not going to fund these businesses.”
Ashley Pittard, Pendal’s head of Global equities
“In the short term, tailwinds of limited capital expenditure and higher oil prices are attractive. But in the long term, automobiles are becoming electric, notwithstanding there will be a long tail of vehicles,” Pittard says.
“What you will see over time is the best oil companies becoming more like wind generation companies, or battery technology companies.
“Ironically that will reduce cyclicality among the integrated oil companies and they will end up with a business model which is more like a utility companies.
“You can invest in oil companies so long as they are doing a good job reinventing themselves, increasing their focus on wind technology, battery technology, solar and the rest.
“That way you can get the upside of them being an oil company today.”
About Ashley Pittard and Pendal Concentrated Global Share Fund
Ashley Pittard leads Pendal’s Global Equities investment boutique. He is responsible for setting the strategy, processes and risk management for the boutique and its funds including Pendal Concentrated Global Share (COGS) Fund.
Ashley has more than 24 years of finance experience, including roles in petroleum economics, global energy investment analysis and 20 years as a global equities fund manager.
Pendal COGS Fund is an actively managed, concentrated portfolio of global shares diversified across a broad range of global sharemarkets.
Find out more about Pendal Concentrated Global Share Fund
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Emerging markets investors need to take great care when choosing tech-related stocks right now. Here, Pendal’s EM team JAMES SYME, PAUL WIMBORNE and ADA CHAN explain why
- Find out about Pendal Global Emerging Markets Opportunities fund
JULY was a strong month for emerging market equities.
The MSCI EM index returned 6.2% in USD terms, with strong gains from some major groups of stocks.
Chinese internet names performed well, including some key portfolio holdings.
Some emerging market banks rose strongly, including portfolio holdings in Mexico and South Africa. Turkish (not held) stocks rose strongly on hopes for more orthodox economic policies.
By far the strongest gains, though, were in parts of the broader technology sector — especially stocks with exposure to electric vehicles or batteries, and stocks that are possible artificial intelligence beneficiaries.
We see multiple signs that there may be excessive optimism in some of these stocks.
We’re not taking a view on particular companies or business models — and we’re not saying these upward moves are finished.
But it’s worth highlighting some of the market dynamics we saw in July:
1. Huge volumes and parabolic price moves driven by retail investors
This has particularly been the case with the Korea EV and battery sector.
These stocks represented nearly half the total Korean stock market turnover on some days in July, driven by retail investor leverage rising to a record 10 trillion South Korean won.
Key to stock selection has been a Korean YouTube presenter Park Soon-hyeok, better known as ‘Mr Battery’.
Six of his eight recommended names rose more than 40% in the month. The strongest of them, Ecopro (not held), was up 1059% this year at the time of writing.
There have also been a raft of new issuance in Korean EV/battery ETFs in recent weeks.
2. The strongest moves are in names that might have quality challenges
Chinese online education play New Oriental Education (not held) returned 49.8% in July. It’s previously been the subject of short-seller allegations of dishonesty and a crackdown on online education by the Chinese government.
NIO (China, EV, not held) lifted 58% in July, though it’s forecast by consensus estimates to have a net loss of US$2 billion on $8.9 billion of sales this year.

Find out about
Pendal Global Emerging Markets Opportunities Fund
Nio underperformed XPeng (China, EV, not held), which rose 74% in the same period, despite expectations it will lose $1.2 billion on $4.5 billion in sales.
Oh, and in May of this year Lee Dong-chae, chairman and biggest shareholder in Ecopro, was sentenced to two years in prison for violating South Korean capital market laws.
3. We’ve seen parabolic moves in stocks that aren’t pure-play tech names:
Posco Holdings (Korea, steel, not held) is one of Asia’s biggest steel producers, with 30,000 employees producing 32 million tons of steel every year.
The company has made some smart investments in green steel technology, and has ongoing investments in EV battery components.
A management update in July was material in driving Posco’s market cap from $24.9 billion to $42.5 billion in the month.
Similarly, exceptionally strong monthly gains (50% plus) were seen in some Taiwanese computer hardware makers, even though they have been reporting declining PC, laptop and server volumes this year.
Investors are hoping server orders from artificial intelligence (AI) businesses are about to follow — even though volumes and margins at this point are unclear.
4. High-quality, large-cap companies with proven track records and technologies were laggards in July
TSMC (Taiwan, tech hardware, held) is widely recognised as the world’s dominant producer of the high-performance semiconductors that are key to AI.
The stock fell 2.8% in July.
Samsung Electronics (Korea, tech hardware, held) is TSMC’s nearest challenger in high-end semiconductors, as well as a major producer of computer memory, including the HBM type used in AI servers.
The stock fell 0.4% in July.
Technological revolutions in AI and EV are changing the world, but equity markets will not price that opportunity with perfect efficiency.
We are concerned that some parts of the EM equity space look particularly inefficient right now.
About Pendal Global Emerging Markets Opportunities Fund
James Syme, Paul Wimborne and Ada Chan are co-managers of Pendal’s Global Emerging Markets Opportunities Fund.
The fund aims to add value through a combination of country allocation and individual stock selection.
The country allocation process is based on analysis of a country’s economic growth, monetary policy, market liquidity, currency, governance/politics and equity market valuation.
The stock selection process focuses on buying quality growth stocks at attractive valuations.
Find out more about Pendal Global Emerging Markets Opportunities Fund here
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
China faces slowing growth and weak consumer confidence. But there are opportunities for investors willing to take a closer look, argues PAUL WIMBORNE
- Economic stimulus unlikely
- But China equities look good value
- Find out about Pendal Global Emerging Markets Opportunities fund
CHINA’S economic downturn is starting to create attractive opportunities for equity investors, though a mixed performance across the economy means a cautious approach is warranted, says Pendal’s Paul Wimborne.
Beijing’s policymakers are struggling with a mix of slowing growth, weak consumer confidence and rising youth unemployment, as the brief spark of activity after last year’s COVID lockdowns fizzles out.
Markets latched on to a dovish statement from last week’s politburo meeting that said the government planned to step up “countercyclical measures”.
But there are few real signs of significant stimulus, says Wimborne, co-manager of the Pendal Global Emerging Market Opportunities fund.
“There is a lack of confidence in China driving this weakness – so the question is how does the government assess and react to that?
Long-term focus
“We think the key priority for the Chinese government remains building long-term economic and financial system resilience and growth hasn’t yet fallen to the levels that would lead them to aggressively stimulate.
“We think they will continue to push through mini stimulus measures in certain areas where they would like to encourage growth — but we don’t think they’re at a point where we’ll get a big stimulus plan.”
Wimborne says Beijing’s focus on long term resilience means some of the stimulus measures the market is hoping for — like expanding credit availability for the property sector — are unlikely to eventuate.
“The key policy plank that has been in place over the last three years is to shrink the size of the property industry and consolidate around the better run companies with stronger balance sheets.
“We believe that is still a key policy plank for them and it’s very unlikely that they are going to want to shift away from that unless conditions get much worse.”
Find out about
Pendal Global Emerging Markets Opportunities Fund
Direct stimulus for consumers — echoing the West’s policy measures during the pandemic — is also unlikely, says Wimborne.
“The risk of these policies, as we have seen in the West, is inflation. The government has stated that they do not want to move down that path. They don’t think handing out free money is a good way to manage an economy.”
Large-scale stimulus unlikely
The upshot for investors is that any stimulus is likely to be narrowly targeted and aligned with Beijing’s long-term policy outcomes.
“So, for example tax exemptions on electric vehicle sales – that is aligned with the direction they want to take the economy, reducing demand for oil and promoting the size and scale of the domestic electric vehicle manufacturing industry.
“But these are small scale — they help at the margin, but they’re not going to be a big stimulus.”
Value to be found
The implication for investors is not to get fooled by apparently attractive valuations but instead tread a careful path and be selective about investments.
“China’s equity market is very cheap,” says Wimborne.
“While economic growth is slower than people were anticipating at the start of the year, it’s not terrible and there are certain areas where growth is holding up relatively well.
“That means there are parts of the economy we are happy to get exposure to — and parts that we would like to avoid.
“Overall, it leads us to be slightly underweight China but there are key areas which we think show decent growth trends with cheap valuations that are interesting from an investment point of view.”
Wimborne says his preferred investments in China include premium domestic brands Tsingtao Brewery and Proya Cosmetics alongside companies exposed to the energy transition like natural gas distributor ENN Energy and solar panel glass maker Xinyi Solar.
About Paul Wimborne and Pendal Global Emerging Markets Opportunities Fund
Paul Wimborne is a senior portfolio manager and co-manager of Pendal’s Global Emerging Markets Opportunities Fund with James Syme and Ada Chan.
The fund aims to add value through a combination of country allocation and individual stock selection.
The country allocation process is based on analysis of a country’s economic growth, monetary policy, market liquidity, currency, governance/politics and equity market valuation.
The stock selection process focuses on buying quality growth stocks at attractive valuations.
Find out more about Pendal Global Emerging Markets Opportunities Fund
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.