
- Tech and education crackdown sends Chinese shares falling
- China government aims to ease cost of living pressures
- Questions over risk-reward balance for investors
CHINESE regulators this week outlined reforms that will ban private firms that teach the school curriculum from generating profits, raising capital or going public.
The move was aimed at reducing cost-of-living expenses for Chinese familes, who are now encouraged to have three children.
The changes caught investors by surprise. Shares in Chinese private education companies inside and outside the country plummeted.
But this policy shift also has potential implications for a number of Australian-listed companies, in areas such as infant formula.
“There’s two interesting aspects here,” says Elise McKay, an analyst in Pendal’s equities team.
“First of all, China needs to address its population problem.”

“New births have fallen off in China to the lowest level since the famine in 1961. Women of child-bearing age are having fewer children and the population is ageing. This causes real issues.”
“COVID has accelerated this because some people are putting off pregnancy while they get vaccinated or to avoid getting COVID while they are pregnant.”
“The new policy is to lower the cost of raising a child and boost birth rates. They also want to reduce inequality amongst those who can afford to pay for after school tutoring and those who cannot,” says McKay.
Lifting China’s birth rate is potentially good news for businesses that sell to Chinese families, including Australia’s high-profile suppliers of infant formula.
However there is a second aspect to this shift.
“There’s also this increasing uncertainty around regulation, particularly in public companies,” says McKay.
“We need to watch for signals of regulation around pricing for infant formula – this also affects the cost of rearing children.”

Pendal Focus Australian Share Fund
A high-conviction equity fund with 16 years of strong performance in a range of market conditions
“We may also see China look to prioritise domestic brands.”
There are several recent examples of greater intervention in markets. The move in education comes after similar crackdowns in technology, payments and ride-hailing.
A high-profile investigation into ride-hailing firm Didi’s handling of customer data that halved the newly-listed company’s share price.
And it follows a regulatory inquiry into tech giant Alibaba earlier this year that scuppered the float of its payments arm Ant.
A higher birth rate could be an opportunity for Australian companies. But the prospect of more regulation and the prioritisation of domestic brands may shift the balance of risk against investors.
“It’s very nuanced,” says McKay. “And it’s a case for actively managing risk. It is a development that we will be watching very closely.”
About Elise McKay and Pendal
Elise is an investment analyst with Pendal’s Australian equities team. Elise previously worked as an investment analyst for US fund manager Cartica where she covered a variety of emerging market companies.
She has also worked in investment banking and corporate finance at JP Morgan and Ernst & Young.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out about Pendal Focus Australian Share Fund here.
The biggest question in local and global financial markets is no longer about the COVID pandemic. It’s about inflation and whether it will stick around.
- The current bout of inflation is more than transitory.
- RBA models have a bias toward low price rises.
- Mortgage rates likely to start drifting higher
CENTRAL BANKS around the world acknowledge that the global economy is in the midst of a bout of inflation. Most argue it’s transitory, driven by supply-side effects that will dissipate later in 2021.
But has the Reserve Bank of Australia, and its peers, got it wrong?
Quite possibly, says Tim Hext, portfolio manager in Pendal’s Bond, Income and Defensive Strategies team.
“We think that inflation and wages will come back to the RBA target range a lot quicker than the Reserve Bank thinks.”
One of the reasons for the central bank’s potential misreading of the economy is because it forecasts inflation using a model developed about five years ago, which picks up on inflation expectations, Hext says. And expectations over recent years have been low.
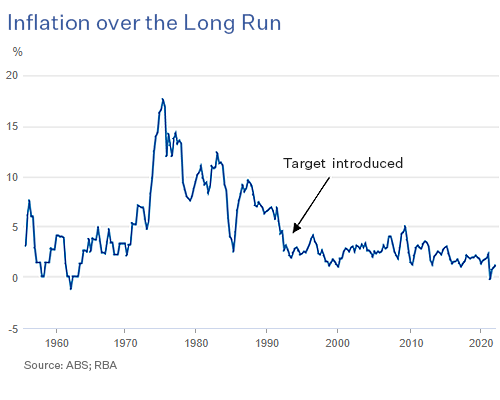
“So the model says … the best guide to future inflation is past inflation, because of people’s expectations. It says businesses will be slow to increase prices and consumers won’t be expecting inflation to be a problem. It has a bias in it.”
Another reason for the likelihood of the official cash rate rising sooner than the RBA’s current forecast of 2024 is because it came out so publicly about rates remaining low in an effort to stem the downturn in the economy.
“The Reserve Bank is like a big oil tanker. It takes time to turn around,” Hext says. “After providing strong guidance last year, everything in the economy started improving.
“It’s gotten to the point where they’re now using inflation to fit their narrative, as opposed to building their narrative around inflation.”
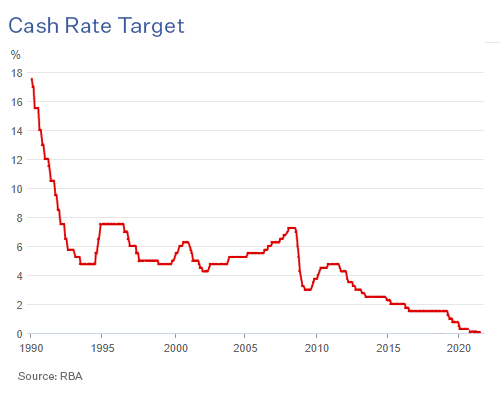
“It suits them to use the inflation figures [which are very low], but you have to remember that inflation lags the economy by 12 to 18 months. The economy started to pick up in the middle of last year, so I expect to see inflation at the end of this year,” Hext says.
He doesn’t support the view that the supply-induced price rises, currently apparent in the economy, are transitory.
“You’re going to see goods prices squeezed and businesses are in a pretty good position to pass on the cost increases. The data is already showing that in the US.
“And services inflation, which is more important than goods inflation, is exposed to labour markets. Labour is the primary input into services. And the labour market is going to get a lot stronger. It’s likely to be near four per cent this time next year.”
The oil tanker, as Hext puts it, will have to start turning.

Find out about
Pendal’s Income and Fixed Interest funds
The first thing the Reserve Bank did was switch off the term funding facility for banks at the end of June, thereby denying lenders a cheap source of funds, Hext says.
They have also announced a taper of quantitative easing by reducing purchases of government bonds from $5 billion a week to $4 billion a week in September, although recent lockdowns may see that timing pushed back.
And finally the central bank will have to lift the official cash rate, which is used to price other lending rates.
Hext says the term funding facility played as big a role on interest rates for mortgages on the way down and is likely to do so on the way back up.
“The money the banks borrow [to lend to customers] will be at a higher rate once the funding facility ends. It will take time to work through the system, but the overall cost of funding for banks will go up. And mortgage rates will start drifting higher.”
The spectre of inflation is back, and as Hext puts it, the Reserve Bank oil tanker might need to turn just a bit faster.
About Tim Hext and Pendal’s Income and Fixed Interest boutique
Tim Hext is a portfolio manager with Pendal’s Income and Fixed Interest team.
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia. In 2020 the team won the Australian Fixed Interest category in the Zenith awards.
With the goal of building the most defensive line of funds in Australia, the team oversees A$22 billion invested across income, composite, pure alpha, global and Australian government strategies.
Find out more about Pendal’s Income and Fixed Interest strategies here
About Pendal Group
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Here’s what’s driving Australian equities this week according to Pendal’s head of equities Crispin Murray. Reported by portfolio specialist Chris Adams.
ALTHOUGH the ASX is touching new highs, equity markets continue to grapple with a slowdown in economic growth and potential implications of the Delta variant.
The sell-off on July 19 reversed late last week as US earnings continued to show strength and M&A activity supported the local market. The S&P/ASX 300 rose 0.6% last week and the S&P 500 was up 2%.
Despite growing uncertainty, the underlying foundations of fiscal stimulus and abundant liquidity continue to win out.
COVID and vaccines
British data continues to show a disconnection between the rise in new Delta-strain Covid cases and the resulting rate of hospitalisations.
Initial signs of a decline in new UK cases provide grounds for optimism, though new cases are expected to pick up as restrictions are removed.
There are also signs of stabilisation in new cases elsewhere — including Spain, Malta and Indonesia which have all experienced a surge in Delta infections.
On the negative side, it is becoming apparent that even well-vaccinated countries will experience a Delta-driven wave.
In the US we are not seeing a disconnection to the same extent as the UK. New cases are up 56% week-on-week and hospitalisations have risen 36%. This may reflect lower testing rates and a higher proportion of unvaccinated people. Data shows that fewer than 3% of hospital admissions are vaccinated.
The big issues are Delta’s effect on government policy, the potential for on-going restrictions and the need for booster doses. The reality is that we don’t have answers at the moment.
Find out about
Pendal Focus
Australian Share Fund
Crispin Murray,
Head of Equities
We are seeing increased hospitalisations in Israel – albeit off a low base and well below the previous wave.
The sample size is small and there are complexities related to age, but this may suggest vaccines become less effective in terms of infection and hospitalisation over time. This could mean some restrictions will remain in place even after countries move to re-open.
The issue of “breakthrough” infections in people who have been vaccinated poses a difficult issue for Australia, given low political tolerance for any degree of community infection.
The concept of herd immunity is getting difficult to pursue and may require some pivot in approach. There remains potential for policy confusion and further delays in re-opening of borders.
In Australia the news has been mixed. There are signs that Victoria will be able to re-open to a degree, while Sydney is facing an extended lockdown.
The market is focused on economic implications. We may see the RBA signal an extension of tapering given the change in economic momentum. There will be a lot of focus on potential for government stimulus.
Economics
Some indicators suggest the second derivative of growth – the rate at which it is growing – has ticked over. This is unsurprising: the speed of economic recovery could not be maintained.
Nevertheless, this is some causing some concern in markets, particularly in combination with the Delta strain.
History suggests that when the second derivative of growth turns, this marks the beginning of a phase where disappointments are more likely and earnings revisions are negative.
But the unique nature of this cycle may offer a counter-argument.
Normally slowing economic momentum is a function of some form of policy action. For example in 2018 Fed tightening clearly prompted the slowdown. This time slowing momentum is a function of the unprecedented growth rate triggered by the Q1 US stimulus.
The bullish case for cyclical stocks says there is currently no policy tightening; no prospect of rates rising; and tapering is increasingly likely to be pushed into 2022.
2021 Money Management of the Year Awards
Pendal Australian Shares Portfolio
Winner – SMA Australian Equities
Pendal Property Investment Fund
Winner – Australian Property Securities
The bear case says the Fed will face a quandary with slowing economic momentum yet high inflation — and may end up tapering into a weaker economy.
We tend towards the bull case at this point. Slowing economic momentum would likely ease inflationary pressures as well. All the evidence of the past 18 months suggests governments are pro-growth and will react with more policy stimulus.
Clarity on this issue is unlikely before Q4 2021. By then we’ll have seen the end of the US summer break and unemployment insurance payments trailing off. At this point we’ll potentially see job growth reaccelerating.
Until then, we could see the current rotation to more defensive, quality, bond-sensitive stocks persist.
Markets
Equity markets continue to rise despite concerns over Delta and the slowing pace of growth, although breadth has narrowed.
Liquidity and low rates continue to act as backstops. The combined balance sheet of the Fed and European Central Bank continues to expand at more than US$100 billion a week.
US earnings season is good so far. Earnings revisions have the potential to shift the S&P 500 price/earnings ratio from 22x to 20x. The next two weeks will be important to watch in this regard.
Australia’s upcoming earnings reason will not be as buoyant as the US and guidance will be subdued. But the prospect of a weaker Australian dollar, delayed monetary tightening and potential for fiscal stimulus should continue to support the market.
Last week rotation continued into defensives and quality. Health care (+4.6%) led alongside Consumer Staples (+2.1%). Energy (-1.8%) and Materials (-1.1%) underperformed.
Altium (ALU, -9.4%) was the weakest on the ASX 100. Management rejected a takeover offer from US company Autodesk, which then withdrew the bid.
Gold miners underperformed despite the market’s more defensive bent, as the gold price came off 0.7%. There was some news flow in the sector. Evolution (EVN, -9.4%) was weaker on a quarterly update that signalled lower production and higher capex in the near term as they accelerate longer-term project development.
The stock fell, but rebounded as management raised capital to buy an asset from Northern Star (NST, -6.0%) which will help increase utilisation and extend the life of its Mungari mill in Western Australia. The deal makes sound strategic sense, though the timing of the capital raise could have been better.
Crown (CWN, -8.4%) continued to wallow in the wake of the Victorian Royal Commission. Last week Star (-1.4%) withdrew its offer for CWN. There is still logic to a merger, but the three-month wait until the Commission’s outcome makes it hard to value the company.
Santos (STO, -6.1%) proposed a merger with Oil Search (OSH, +3.1%) which also makes strategic sense, given the impact that ESG is having on capital available in the sector. A merger would address a number of issues depressing OSH’s valuation rating and would offer cost synergies. The implied 10% premium proposed by STO may not be enough for OSH shareholders at this point.
BHP (BHP, -1.2%) delivered a decent quarterly production update, in contrast to Rio Tinto (RIO, -2.7%) where operating issues remain. There was speculation that BHP would combine some or all of its Australian oil and gas business with Woodside (WPL, -1.9%) in some form. This is complex given the difficulty of estimating reserves and arriving at a valuation in areas such as Bass Strait.
Health care stocks benefited from the rotation to quality and defensives. Fisher and Paykel Healthcare (FPH, +7.6%) did best.
CSL (CSL, +5.7%) was among the strongest ASX 100 stocks last week. It has lagged for some time over concerns around plasma collection in the US. The outlook here is improving.
Retailers were strong with Wesfarmers (WES) up 4.8% and JB Hi-Fi (JBH, +4.6%). JBH provided positive guidance, but we are cautious. Unlike previous lockdowns there is not the same support for retail spending.
Find out about Crispin Murray’s Pendal Focus Australian Share Fund
About Crispin Murray and Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia. Crispin’s Pendal Focus Australian Share Fund has beaten the benchmark in 12 years of its 16-year history (after fees), across a range of market conditions.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about Pendal Focus Australian Share Fund here.
Contact a Pendal key account manager here.
Pendal Group (ASX:PDL) has announced the completion of its acquisition of US-based value-oriented investment management company, Thompson, Siegel & Walmsley LLC (TSW).
Highlights:
- 96% of TSW client consent to the acquisition secured and expect to achieve 100% consent shortly after close.
- Early completion achieved – reflecting the cultural and commercial alignment of both teams and the strong mutual commitment to realise the growth opportunities ahead.
- John Reifsnider, TSW CEO, to lead Pendal’s consolidated US business and joins the Pendal Group Global Executive Committee.
- Step change in Pendal’s FUM: more than doubling US FUM to A$62.5 billion (US$47.0 billion)* and increasing total Group FUM by 31% to A$139.3 billion.
- Expected to be double digit EPS accretive in the first full year, post completion.
PENDAL Group CEO, Nick Good (pictured), said: “We are thrilled to welcome the TSW team and its clients to Pendal Group.
“Client support has been incredibly strong, with 96% TSW client consent received in just 11 weeks. It is testament to the compatibility and drive of the two organisations and their teams that we have completed the acquisition well ahead of original expectations.
“As a result of the acquisition, we will double our addressable market in the US and extend our ability to generate new FUM through the distribution of both TSW and JOHCM products across an expanded global network.
“Today, John Reifsnider becomes the new leader of the combined US business. John and I have worked closely together to complete the transaction expeditiously, cognisant of the importance of client and team support for the go-forward proposition. I am very pleased that John will be taking on this key role.”
Mr Reifsnider said: “The team and I are more convinced than ever of the merits of bringing together these two culturally aligned and forward-looking businesses.
“We believed from the outset that both organisations are a natural fit with compatibility in investment philosophy, client service and our entrepreneurial approach.
“The teamwork in delivering early completion and client consent is validation of this view and bodes well for future success.”
Broader range of product solutions
Mr Good commented: “This acquisition significantly broadens the range of product solutions we can offer clients via an expanded distribution network, and we are focused on providing our combined investment strategies to our enlarged client base as soon as possible.
“Both organisations share a core belief in investment team autonomy, and TSW’s investment autonomy will be preserved, an important consideration for our clients.
“As complementary businesses, with almost no overlap of investment strategies, together, we will be better placed to take advantage of the growth opportunities we see in the US market.”
There was strong support for the acquisition from Pendal’s institutional and retail shareholders and as a result, the successful Placement and Share Purchase Plan raised A$380 million in total.
This equity raising reduced the debt and balance sheet funding which was required to complete the transaction to A$57 million (US$44 million). This outcome provides additional balance sheet strength and capacity for Pendal to accelerate its growth opportunities.
Mr Good concluded: “The acquisition has delivered immediate value for our shareholders and a step change in Pendal Group’s diversification, scale and client offering.
This creates enhanced opportunities for growth, particularly with increasingly positive investor sentiment, a flourishing US economy and the global economic rebound.”
* Includes TSW FUM of US$24.6 billion (A$32.6 billion). Based on exchange rate of AUD:USD of 0.7518 at 30 June 2021.
Visit Pendal’s shareholder website for more information.
About Pendal
Pendal Group (“Pendal”) is an independent global investment manager focused on delivering superior investment returns for clients through active management. Pendal manages A$106.7 billion in FUM (as at 30 June 2021) in client assets through J O Hambro UK, Europe & Asia; JOHCM USA; Pendal Australia and Regnan.
Pendal operates a multi-boutique style business delivering superior results across a global marketplace through a meritocratic investment-led culture. Its experienced, long-tenured fund managers have the autonomy to offer a broad range of investment strategies with high conviction based on an investment philosophy that fosters success from a diversity of insights and investment approaches.
Listed on the Australian Securities Exchange since 2007 (ASX: PDL), the company has offices in offices in Sydney, Melbourne, London, Prague, Singapore, New York, Boston and Berwyn, Pennsylvania in the US.
About Thompson, Siegel and Walmsley (TSW)
TSW is a US-based value-oriented investment management and advisory company, operating primarily in the long-only equity (International and US) and fixed income asset classes with US$24.6 billion (A$32.6 billion) of FUM as at 30 June 2021.
Established in 1969 and headquartered in Richmond, Virginia, the company has a well-known record in attracting and retaining investment talent, with an average tenure of 12 years among the investment team members.
Here’s what’s driving Australian equities this week according to Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
GLOBAL equities have struggled to push higher recently under the weight of several factors.
US inflation data was again stronger than expected last week, while concern lingered over the impact of the contagious Delta Covid variant.
Global equities dropped — the S&P 500 gave up 0.96% — but the Australian market bucked the trend, rising 1.05%. Merger and acquisition activity and a stronger resource sector continued to lend support.
Markets are in something of a holding pattern while investors look for visibility on a number of unresolved issues.
These include:
- Economic growth: How much is it slowing? To what extent is this about temporary supply-related issues? Or is it a signal that pent-up demand is less than expected?
- Inflation: How transitory will this be?
- Covid: To what extent will Delta or other variants affect the recovery and re-opening of economies?
- Central bank policy: How quickly will they need to reduce balance sheet expansion and begin to raise rates?
- Fiscal policy: Do we see more stimulus coming through in the form of infrastructure and other social investment programs?
- China: To what extent is the economy slowing and how material a shift in policy will we see?
- Corporate earnings: How much leverage to re-opening, the impact of rising cost pressures and the ability to raise prices?
These issues are inter-related. Some such as inflation and fiscal policy may take a long time to become clear.
However we should get a good read on most factors through this quarter. This will play into how bonds and the US dollar perform, which will in turn affect the performance of commodities, as well as cyclicals and defensives in the equity market.
We expect markets to consolidate in the near term. Domestic cyclicals are likely to struggle. But we expect concerns around most of the factors above to ease, potentially creating opportunities.
COVID and vaccines
South East Asian countries with low vaccination rates are reporting a surge in new Covid cases. Malaysia, Thailand and Indonesia are running at their highest daily case numbers so far.
But we are also seeing surges in countries such as the UK and the Netherlands, where vaccination rates are high. Rising cases in France, the US and Israel have prompted a return to restrictions.

In Malta 80% of the population is fully vaccinated and a further 5% have had a single dose — yet it is seeing a sharp rise in new cases. There are still questions to be answered — is the spread primarily among the unvaccinated for example? But places like Malta will be important in understanding whether the new wave of Covid will lead to a more restricted re-opening.
The UK remains something of a bellwether. New daily cases are running within 15% of the highs of the previous wave, but hospitalisations are 80% lower.
This suggests vaccines are helping prevent people from getting very sick. But it’s not yet clear if new cases are predominantly unvaccinated people or “breakthrough infections” among those who are vaccinated.
We can also gain insight from the US. There is a clear link between rates of vaccination and infections by county. Counties with vaccination rates of 50-59% have half the infection rate of counties with less than 30% vaccination.
The US is also publishing reassuring data on breakthrough infections and hospitalisations. So far this year vaccinated patients account for only 0.4% of Covid-related hospital admissions. That is running at about 1% more recently, which reflects the Delta strain. Some 75% of recent admissions have been people over 65.
We can make a couple of observations about Australia in light of this.
First, it is difficult to envisage us remaining Covid-free even with high vaccination rates, without keeping international borders shut. This necessitates some shift in policy approach, which will be more complex than first thought. This will be an important factor in elections.
Second, it highlights the difficulty in achieving eradication in NSW. Even if you get cases very low, the latest Victorian wave shows how quickly the variant can spread.
Policy makers will need to decide whether to extend restrictions to contain case numbers until we reach warmer months when the vaccine program can be accelerated. This could take us through to October or November.
If so, we would expect significant offsetting stimulus. Nevertheless it would weigh on the domestic economy and have a negative impact on more cyclical stocks. Given the lack of visibility, we are wary of re-loading on this part of the market despite recent weakness.
Economics and policy
There are some real-time indicators. The Atlanta Fed’s GDPNow estimate suggests economic growth has fallen below market consensus levels for the first time this year, while still remaining strong in absolute levels. This is why bonds have rallied and cyclicals have fallen.
We believe much of this reflects supply bottlenecks in certain areas which — alongside labour constraints — is preventing some businesses from operating or producing as much as they would like. We still expect the effects of pent-up demand, excess savings, low inventories and high wealth effect to help fuel an on-going strong recovery.
That said, the risks to this scenario are rising.
US inflation data surprised to the upside for the third month in a row. Material elements of this – such as used car and holiday accommodation prices – reflect some supply disruptions and a bounce back from last year’s deflation.
But there is also evidence of increases among some longer duration inflation factors. For example there is a pick-up in rents with the ending of restrictions on evicting non-paying tenants. These factors could persist even as more transitory effects roll off.
This is why we believe it is too early to make the call on inflation being temporary — despite the bond market suggesting it is.
Markets
Markets remain in something of a lull due to the Northern hemisphere summer.
Last week we did see the start of what could be a correction in global equities, with higher beta growth names underperforming.
The current equity market rebound differs from other post-crisis environments – particularly the post-GFC experience — since we haven’t had any real correction so far.
This is likely due to the degree of liquidity added by central banks. It would be entirely plausible to see a correction given current uncertainty. However the US earnings season which has just kicked off promises to be quite strong, potentially providing support.
Brent Crude fell 2.6% as the OPEC deal came through, even though this assuaged the previous week’s concerns over OPEC breaking down. We expect the oil market to remain tight. Extra OPEC supply is necessary to prevent a dislocation in the market.
The Australian market played catch-up from previous week, although the gain came almost entirely from resource stocks, while tech and banks sold off. The effects of lockdowns hasn’t really hit sentiment yet. But late last week we began to see domestic cyclicals lag the market.
Infrastructure M&A dominated newsflow for the second week in a row. This time it was Spark Infrastructure (SKI, +17.4%) receiving a bid. The 20% premium offered by Ontario Teachers and private equity firm KKR was less than that offered for Sydney Airport. SKI owns only minority stakes in assets and is more heavily regulated.
Sydney Airport (SYD) gained 2.1% last week. While the board rejected the bid and struck a negative tone to selling, there were also some signals that an offer over $9 might be considered. This is steep, but the bidders have deep pockets and a very long duration timeframe in assessing return. They may well move, although the market is not convinced.
Mining and steel stocks generally outperformed on the combination of Beijing’s policy shift, some better data out of China and the prospect of large capital returns in upcoming results. Fortescue (FMG) was up 8% and BlueScope Steel (BSL, +7.48%).
Rio Tinto’s (RIO, +2.23%) quarterly report was disappointing on the production front and highlights on-going supply issues facing many metals. Nevertheless, strong iron ore prices are likely to underpin a very strong result.
Gold stocks were generally better as the gold price recovers. Northern Star (NST) gained 6.24%. Evolution (EVN, +2.63%) lagged as its quarterly highlighted near-term lower production and higher capex as they scale up the plans for their Red Lake asset.
Tech stocks were weaker, led by Afterpay (APT, -12.17%). We saw further evidence of increasing competition in the buy-now-pay-later space as Paypal entered the Australian market with a product that had no late fees.
This comes as no surprise. Rumours that Apple will enter the BNPL space with an extension of Apple Pay is potentially a much bigger threat to the sector.