
Pendal Stable Cash Plus Fund (APIR: BTA0459AU)
Important information
Reduction in management costs from 1 July 2020 to 30 June 2021
Due to the economic impacts of Covid-19, the RBA reduced the official cash rate from 0.50% to 0.25% on 20 March 2020.
With the cash rate likely to remain at a record low of 0.25%, the Pendal Stable Cash Plus Fund (Fund), currently offered to investors with a minimum initial investment of $500,000 at an issuer fee of 0.18% pa will be reduced to 0.15% pa effective from 1 July 2020, for a period of 12 months. Over this period, the Fund’s issuer fee will be reviewed and any changes will be communicated to investors prior to 1 July 2021.
Pendal Managed Cash Fund (APIR: WFS0245AU, ARSN: 088 832 491)
Increase to the Fund’s management fee effective 1 October 2022
Effective 1 October 2022, the management (issuer) fee for the Pendal Managed Cash Fund (Fund) will increase from 0.12% p.a. to 0.22% p.a.
Why is the management fee increasing?
Since 2020, Australia has experienced historically low official cash rates due to the economic impact of Covid-19. On 1 July 2020, Pendal temporarily reduced its management fee for this Fund from 0.22% p.a. to 0.12% p.a. Although originally intended as a 12-month fee reduction, the lower management fee has continued to apply in light of the continued lower cash rates.
The management fee will increase to its original rate of 0.22% p.a. effective 1 October 2022.
There are no other changes to the Fund.
An updated Product Disclosure Statement (PDS) was issued for the Fund on 26 August 2022 and is available on www.pendalgroup.com. If you would like a hard copy of the PDS, please contact us.
Pendal Managed Cash Fund (APIR: WFS0245AU, ARSN: 088 832 491)
Important information
Reduction in management costs from 1 July 2020 to 30 June 2021
Due to the economic impacts of Covid-19, the RBA reduced the official cash rate from 0.50% to 0.25% on 20 March 2020.
With the cash rate likely to remain at a record low of 0.25%, the Pendal Managed Cash Fund (Fund), currently offered to investors with a minimum initial investment of $25,000 at an issuer fee of 0.22% pa will be reduced to 0.12% pa effective from 1 July 2020, for a period of 12 months. Over this period, the Fund’s issuer fee will be reviewed and any changes will be communicated to investors prior to 1 July 2021.
Here’s the latest outlook for Australian equities from Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
FEARS of a second wave of infections are weighing on markets. This pushed the S&P/ ASX 300 down -0.74% last week.
We are at a critical point in this regard. The next week or two will reveal if the US rise in cases will lead to a surge in hospitalisations, stress on intensive care units and deaths. This is a heightened and material risk with important ramifications for market confidence.
However it is not a foregone conclusion — for reasons discussed below.
The economic data remains supportive and the policy response remains robust. There is political will to do more if needed.
At this point we do not expect recent weakness to morph into a second sharp drop in markets:
-
-
- We believe sufficient measures are underway or will be taken to avoid the resurgence in US cases from triggering material new shutdowns, which would see a big hit to confidence. However this remains a key risk.
- The Victorian outbreak should be containable. While delaying border re-opening it does not represent a significant deterioration in the economic outlook.
- The current case rise will likely cement the need for more stimulus in US and Australia
- Economic momentum is still positive
- Significant liquidity remains on the sidelines in cash, which can support equity markets
-
That said, we expect this period of consolidation to continue. The rate of improvement in economic data will now slow down, the market’s short-term positioning remains too bullish and policy news flow is in a lull to the end of July.
COVID-19 outlook
While second-wave clusters in China and Germany appear contained, cases continue to rise in the US.
This alone is not causing economic issues. But there are fears of a re-run of March/April, with cases leading to stress in hospitals and ICUs and a surge in deaths. This would likely be a material set-back for market sentiment.
Hospitalisation and mortality data in the next week or two are critical for how the market will trade in coming months.
As China and Germany have demonstrated, a replay of April — in terms of case-loads, hospitalisations and mortality —is not a foregone conclusion. Today’s situation is different in several important ways:
-
-
- The outbreaks are in less densely populated areas compared to New York
- The age profile of new cases is a lot lower this time — an average of 20 years younger.
- There is substantially more testing. This may result in worse-looking numbers. But it means the problem is being identified earlier than in April
- There is more physical distancing and use of face masks — despite well-publicised incidents to the contrary.
- Knowledge of how to treat the virus is now far better. Previous treatment had focused on lung issues, which are now thought to be symptomatic in nature. Treatment is now focused on anti-inflammatories, with better outcomes as a result.
-
We continue to monitor key US data points.
At this point we don’t believe it will escalate to levels seen in New York several months ago. However this cannot be ruled out. Material risks remain in play. Our portfolio continues to reflect a range of possible outcomes.
One silver lining to the US surge is a strong, continuing focus on vaccine development. Pfizer’s CEO alluded to the possibility of a vaccine being available this year. Results of a 30,000-person trial are due in September. If successful he suggested 100 million doses might be available this year, growing to 1 billion in 2021.
Economic data
Economic data remains broadly supportive, off-setting negative news on case-loads.
Last week’s Purchasing Manager’s Indices — PMIs are a leading indicator of economic momentum — showed a sharp rebound from earlier depths.
Credit card data also suggests consumption continues to rebound. Government payments have prompted savings rates to surge. In combination with pent-up demand this can help support higher consumer demand.
Recent data suggests the Australia’s GDP has fallen about 4% from its pre-pandemic level, placing it among the least-affected nations. It is interesting to note China and Sweden have also fared better than most, given the very different approaches taken by all three countries.
Impact on the US is estimated at about 6.5%. GDP expectations have also been improving in recent weeks.
Fed balance sheet
There have been some concerns about the Fed shrinking its balance sheet and the implications for liquidity.
We do not think this should be interpreted as a signal of Fed tightening. Rather, we think it reflects reduced risk aversion from foreign central banks as they run down their swap lines.
The Fed balance sheet can be looked at in three ways:
-
-
- The Quantitative Easing portfolio: This is unchanged. The Fed continues to buy US$80 billion in Treasuries and US$40 billion in mortgage-backed securities per month.
- The liquidity programs: The FX swaps provided to foreign central banks to ensure they could access US dollars reached US$450 billion at the peak of crisis. This is now down to US$275 billion as USD funding issues have eased.
- Direct credit programs — primary and secondary market corporate credit facilities: These are ramping up more slowly than planned. There has been US$10 billion provided so far, mainly into the secondary program (ie credit ETFs). Part of this is the complexity of getting program running. Also, the availability of credit has not proven to be as big an issue as many feared. The market has seen record levels of credit issuance in recent weeks.
-
While there are a lot of moving parts, we still see at least US$1 trillion in liquidity to be added by the end of 2020 — and a commitment to keep adding potentially $1.5 trillion next year.
Markets
Equities have sold off and sentiment has shifted negatively. But there has been no breakdown in other key indicators we are watching.
US 2-year yields remain flat, oil rose 5%, the EUR/USD was only up 1%, gold was only up 2% and the copper/gold price ratio held firm. Credit spreads widened — but not outside recent ranges.
At this point it still feels like a market consolidation rather than a reversal and a new phase of crisis. But a lot will come down to hospitalisations in coming weeks.
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and a strong track record leading Australian and European equities funds. He manages a number of our flagship funds along with one of the largest equities teams in Australia.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
https://www.pendalgroup.com/about/our-people/sales-team/
Important Updates
Pendal Dynamic Income Fund (APIR: BTA8657AU, ARSN 622 750 734)
Pendal Enhanced Credit Fund (APIR: RFA0100AU, ARSN 089 937 815)
Pendal Fixed Interest Fund (APIR: RFA0813AU, ARSN 089 939 542)
Pendal MicroCap Opportunities Fund (APIR: RFA0061AU, ARSN 118 585 354)
Pendal Monthly Income Plus Fund (APIR: BTA0318AU, ARSN 137 707 996)
Pendal Sustainable Australian Fixed Interest Fund (APIR: BTA0507AU, ARSN 612 664 730)
Effective 30 June 2020, prior notice will no longer be provided in the event of a material increase to the buy-sell spreads of the above mentioned funds (Funds). Section 6, ‘Fees and costs’, of the PDS of the Funds has been updated to reflect these changes.
The buy-sell spread is an additional cost to you and is generally incurred whenever you invest in a Fund. The buy-sell spread is retained by the Fund (it is not a fee paid to us) and represents a contribution to the transaction costs incurred by the Fund such as brokerage and stamp duty, when the Fund is purchasing and selling assets as a result of applications to or redemptions from the Fund. The buy-sell spread also reflects the market impact of buying and selling the underlying securities in the market.
During periods of heightened volatility, as experienced during the COVID-19 pandemic, the cost of buying and selling securities can increase significantly, and suddenly. As a result, a Fund’s buy-sell spread may need to be adjusted to reflect the increase in transaction costs at short notice. This is to ensure all unit holders are treated fairly by attributing the costs of trading securities to those unit holders who are buying and selling units in a Fund.
You should review current buy-sell spread information before making a decision to invest or withdraw from a Fund. Please refer to our website www.pendalgroup.com and click ‘Products’ for the latest buy-sell spread for each of the Funds.
What is the role of fixed income in a portfolio right now? Pendal portfolio manager Amy Xie Patrick explains here and outlines the team’s strategy for its Dynamic Income Fund.
Watch the video above or read the transcript below.
TRANSCRIPT
What is the role of fixed income in a portfolio?
Fixed interest has two main roles in the portfolio: to provide diversification and generate income. Now, with diversification, let’s face it, nobody likes to see one part of their portfolio fall, even though other parts of their portfolio, maybe rising. But we all need some portion of our portfolio to be defensive in times of market stress.
And that’s what we really mean when we talk about diversification. Interest rates exposure, through high-quality government bonds, provides this kind of defensiveness.
The Pendal Dynamic Income fund seeks primarily to play the role of income through maintaining an ability to shift between asset classes — some that are income and risk-seeking, such as investment-grade credit and emerging markets; and others that are more defensive such as government bonds.
As a result, it is a much more defensive product, than most high yield or hybrid funds, but is unlikely to provide the same degree of shelter and crisis liquidity as composite cell products, such as the Pendal Fixed Interest fund.
Why has Pendal’s Dynamic Income Fund experienced a faster recovery?
The Dynamic Income Fund benefits from tried-and-tested design, where we have focused on switching off the riskiest piece quickly and efficiently. For this fund, this is emerging market sovereigns. As risks mounted earlier this year, we made two key asset allocation decisions.
The first was to reduce emerging market risk from 25% to almost zero in just a matter of days. Had this portfolio been a quarter exposed to offshore high yield bonds or Australian hybrids, this kind of de-risking simply could not have happened as market liquidity dried up.
Although the fund suffered losses over this period, our swift de-risking out of Emerging Markets (EM), meant that we avoided the worst of those losses. And more importantly, it allowed us to add back some of that exposure at much better levels during April.
The second was increasing our government bond exposure.
The market continues to doubt government bonds because yields are so low. But time and again, they proved themselves to be defensive when things go awry.
Our decision to add here generated positive returns at the height of the crisis. But our decision to pull back our exposure since then has allowed us to book some of those gains. It’s just precisely this active asset allocation approach that has driven the strong recovery of this Fund over the last two months.
What is the most supportive environment for the fund?
The fund relies on Australian investment-grade credit as its core income engine. While less defensive than government bonds, it is far better at generating income, which is important in a world where interest rates are going to be glued to the floor for some time.
Also unlike equities, a slow-growth environment is actually quite supportive for investment-grade bonds, because corporates choose balance sheet repair over aggressive expansion, and investors flocked to the asset class in search of yield.
As for emerging markets, this is likely to do well as long as the recovery continues, at whatever pace. Especially so considering the extreme levels to which emerging markets had sold off during the crisis.
And unlike most composites style funds, this fund has the ability to tolerate a much wider range of interest rate scenarios because we can choose to hold no government bond exposure whatsoever, should we feel that a significant rise in interest rates is around the corner.
Most importantly, this fund has the room to top up on income-generating potential, which can take the portfolio’s yield to close to 4%.
This is not to be sniffed at considering that term deposits can’t even pay close to 1%.
Amy Xie Patrick is a portfolio manager with Pendal’s Bond, Income and Defensive Strategies team.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
PENDAL is placing higher importance on sustainability factors in its Multi-Asset Target Return Fund amid growing need for liquid sustainable alternative assets in balanced portfolios.
Watch a short video above to hear our Head of Multi-Asset Michael Blayney explain the move.
PENDAL is increasing consideration of sustainability factors within the existing investment process of its Multi-Asset Target Return Fund, in response to the growing need for liquid sustainable alternative assets in balanced portfolios.
Pendal’s Multi-Asset team collaborated with Regnan — Pendal’s in-house ESG research, advisory, and engagement firm — to examine the impact of a stronger focus on sustainability and ESG on risk-adjusted returns.
The research project was led by industry veteran Michael Blayney, who heads up Pendal’s Multi-Asset investment team.
“This is a first for a real return multi-asset fund in Australia and provides investors with more diverse options that factor in social and environmental outcomes over long term time horizons,” Mr Blayney said.
The fund aims to provide a return of 5 per cent per annum above the Australian Consumer Price Index (gross of fees and tax) over rolling five-year periods. There will be no change to this objective, or to the existing fee structure for clients.
The fund will continue to generate returns and reduce risk by blending a highly active asset allocation process with both active security selection and top-down relative value strategies. A greater focus on ESG and sustainability will underpin these sources of return.
A powerful combination of changes in consumer behaviour, stakeholder expectations, and regulatory intervention, we believe, will significantly influence earnings and asset prices across all asset classes in the next decade and beyond.
Of course, we have already seen ample research that shows the outperformance of stocks with stronger ESG credentials.
A landmark Oxford University research report identified a positive correlation between sustainability and good financial performance in 80 per cent of studies analysed.
“Our analysis found that negatively screened companies are in sectors more susceptible to adverse regulatory changes or the loss of a social licence to operate,” Mr Blayney said.
“Furthermore, we will favour sustainable implementation with positive impacts where possible.”
Sustainable investing has become the fastest-growing part of the investment management industry.
Pendal has offered sustainable diversified funds via its Sustainable Conservative and Sustainable Balanced Funds launched by the Bankers Trust group in 1984 as the BT Australia Charities Trust.
Since then we have continued to enhance our consideration of ESG issues, in both fundamental analysis as well as specific strategies.
“We see this type of fund transformation part of the new way of investing where you can target positive returns plus achieve better outcomes for society,” said Richard Brandweiner, CEO of Pendal Australia.
Michael Blayney leads Pendal’s Multi-Asset team.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
How will the risk of a second wave of virus infections impact investors? Pendal’s Head of Bond, Income and Defensive Strategies Vimal Gor explains in a new video interview with online business channel Ausbiz.com.au.
Watch the video above or read the transcript below.
TRANSCRIPT
AUSBIZ.COM.AU INTERVIEWER: Vimal Gor is Head of Bond, Income and Defensive Strategies at Pendal, and he’s joining us live via Skype. Vimal, great to see you there again. Good to have you on Ausbiz. We have this very real risk of a second wave of COVID — some say still the first wave. Are you concerned that it seems the US Government is going with the Swedish approach — to just let it ride out?
VIMAL GOR: YesIf you look across the numbers coming out of the US, there’s a very strong bifurcation between the States that voted for Trump and the States have voted for Clinton. The Clinton States, obviously California, US, seeing their numbers fall quite markedly in line with a lot of the developed countries across the world.
And then you’ve got the other States, which were the Trump-voting States, which are the Midwest etc., where you’re seeing in the southeast the numbers pick up really quite materially. And I don’t know what the US does now because we haven’t got a vaccine, there’s, there’s no impetus or willingness to do further lockdowns.
And the numbers are picking up. I mean, what is the response for the countries, which can’t or won’t do lockdowns and no vaccines? I don’t see what the response is there. And this is going to be super interesting to watch this play out over the next few weeks.
INTERVIEWER: It’s pretty mind-blowing to think of the sheer number of Americans who have fallen victim to this pandemic. How do you, as an investor, gauge the psychological impact, the flow-on effects of a disaster of that magnitude?
VIMAL GOR: Yes, that’s a tough question. I’m coming to the view that there are two things that are kind of useless to look at right now, but take up a lot of time and effort. One is the COVID numbers, because absent an idea for how the response is going to be by the government, we don’t know what the impact is going to be on economic data.
And second is the underlying economic data by itself. The problem with the data right now is that the size of the moves we’re seeing are so large that they’re just unable to be comprehended in terms of what that means for the market.
So the way I generally approach this is, markets generally move in line with the economic cycle and the best way to determine what the economic cycle is, new orders to inventories ratios and PMI, because the manufacturing sector leads the US economy, even though consumption’s larger, consumption, kind of does this, whereas manufacturing does this.
And so it’s the one that leads the economy into and out of recessions. But the problem is the numbers are so large and swinging around so much that they’re kind of pointless. And also because the amount of liquidity that the central banks have flooded the system with, it means that there’s this growing divergence between the underlying economic data in the markets.
So the only thing you can look at to try and get a gauge on where the markets are going or determine what value is purely the central bank packages. And so then, we saw last week that they’re coming out and buying investment-grade credit bonds in the US now, even though they’re pretty much at their all-time highs.
It seems a bit silly, but that’s one thing they’re doing. So you’ve got a green light to buy as much as you can in that space. We talked about fallen angels in the high yield market last time. They very clearly want the equity market to go up, they very clearly want bond yields to stay low.
They’re pretty much supporting every asset market under the world. So what COVID does to the underlying economic data and what the underlying economic data means for the markets is kind of broken now. The markets, we talked about this last time, the market’s largely fixed. That’s the problem.
INTERVIEWER: So if we were to see a vaccine, if we really do see that next stage, are we expecting to see a further rally in equities, a further fall in bond prices? Is that how the markets would play out? Would they be rational?
VIMAL GOR: Yes, I think it’s definitely positive for equity markets and that if we were to see a vaccine that would be great. Yes, it would definitely lead to a strong rally in equity markets. But I don’t think bond yields will sell-off because the central bank very clearly doesn’t want bonds to sell-off.
And because we’ve seen a massive increase in total debt, whether that be a household, corporate or government debt across the world. They don’t want bond yields to sell-off, which slows the economy. So they will continue to hold bond yields down, equity markets would rally, and then ultimately you would expect there to be inflation. And that’s something that I think we need to get our heads around.
That we’ve been in a deflationary environment really since the 1980s. And at some point, given the amount of fiscal largesse we’re seeing, we will be shifting to an inflationary environment. It’s just a question of when and how quickly that happens.
INTERVIEWER: So Vimal if you’re going to be long bonds, what is your preferred exposure?
VIMAL GOR: Well the front ends everywhere a lot now, I still think they’re going to go to negative rates. But you can buy US 10-year Treasury at probably 70 basis points today. And I still think they’re probably going to go sub-zero, probably down to -1.
Now to put that in context, if they go from 70 to -1, you’ve probably got a 40% return on those. So there’s still a lot of money to be left in the bond markets, and therefore I don’t believe you should be underweight bonds.
I think you should be max long bonds at this juncture.
Vimal Gor leads Pendal’s Bond, Income and Defensive Strategies team.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
Here’s the latest outlook for Australian equities from Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
CONCERNS about a material second wave of COVID-19 infections have increased over the past week. This reflects a rise in cases in some parts of the US and other countries.
Here in Australia the spike in Victorian cases needs to be watched. Although small in number it may challenge the theory of a faster re-opening here.
The market rose +1.6% last week despite these issues emerging. This was driven by continued constructive economic data and optimism on further policy support. There was some rotation back to growth — the market sees value stocks more at risk in a potential second wave.
Second-wave risks
Concerns of a second wave are focused mainly on the US. However there are also clusters in Beijing, Germany, and an acceleration of cases in Latin America and India along with an increase in Victorian cases.
The issue from the market’s perspective is the degree to which this will impede the recovery. We think it unlikely the US will return to a broad lockdown, but targeted restrictions will limit some activity. The larger risk is the possible negative effect on consumer and business confidence.
This is a critical test of the US’s ability to absorb periodic increases in infections. If it can be managed, this may begin to build further confidence.
The headline numbers from the US are not encouraging. New daily cases have almost returned to where they were at the previous peak. The concern is this may lead to more hospitalisations, more stress on ICU units and more deaths.
Increases in US cases are concentrated in certain States. For example, Texas has seen cases double in the last few days while Florida is experiencing new daily cases at double the rate of its peak. Declines continue in north-eastern States that were hit hard earlier.
At this point hospitalisations are not picking up on a nationwide basis. The increases in Texas and Florida are not at concerning levels.
Since the previous peak a number of medical developments have emerged — notably awareness of the importance of anti-coagulants and steroids which can help reduce the severity of cases. ICU capacity has also increased.
The key issue to watch this week is whether the combination of much higher testing, physical distancing and better care prevents a significant escalation in severity.
While the uptick in Victorian cases is relatively small in number, it may be highly significant for the market. The consensus view is that disease has been successfully suppressed in Australia, which has led to a more optimistic view on the Australian economy relative to other countries.
If people start to expect restrictions around the country will remain in place longer than first thought, it will have a meaningful impact on market optimism and positioning within it.
Economy
Economic data remains constructive and is doing enough to offset burgeoning concerns over a second wave at this point.
Indicators out of the US remain strong. This partly reflects the fact that the north-eastern States so far avoiding a second wave make up a larger part of the economy than those facing the need for potential new restrictions.
Last week’s US retail sales data were better than expected. The Citi economic surprise index – which tracks the outcome of various data points versus expectations — is at its highest level in 18 years.
In Australia employment data was also better than expected. Monthly hours worked fell -10% from March, versus the -15% to -20% that the market had predicted.
Valuation versus liquidity
Liquidity is helping prop up the market despite more negative news – and is trumping concerns about near-term valuations.
The Fed and other central banks have pumped money into the system, most of which has found its way into cash and bonds.
This is reflected in the surge in FUM in retail money market funds. There has also been record issuance of investment-grade and high-yield bonds.
The overall market position has become more a neutral than a supporting factor. But it is far from a headwind. The liquidity program has allowed access to capital so companies can sort out their balance sheets and become more resilient.
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and a strong track record leading Australian and European equities funds. He manages a number of our flagship funds along with one of the largest equities teams in Australia.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
https://www.pendalgroup.com/about/our-people/sales-team/
What are the different ypes of sustainable investments, how did they develop and why are they growing so quickly? Pendal CEO Richard Brandweiner explains in this Lonsec webinar from June 10, 2020.
Watch the video above or read the transcript below.
RICHARD BRANDWEINER: Sustainability is a particularly relevant topic right now for many reasons.
This is not just because of what we’ve experienced recently through bushfires, floods, famine — and the perspective that the economy is intrinsically linked to these events and our behaviours.
But also because regulators around the world and people are starting to evolve and adapt and change.
Your clients — and yourselves — are starting to buy goods and services based not just on what a company does, but how they go about doing it.
These are fundamental shifts in our psyche that are underpinning a wholesale move towards greater thinking about how we invest.
I’d like to take you on the journey of how we’ve got here and how we’ve evolved in the investment profession from “ethical investing” all the way to “impact investing”.
Then I’ll give you some thoughts about how we at Pendal are adapting to that and have adapted to that over many years.
Then I’ll put that in perspective around the latest development — positive impact.
Ethical investing — where it started
This all really started years ago as ethical funds began to emerge in the 1980s and 1990s.
The idea of “ethical investing” then was very much about values. It was mainly church-based or faith-based groups investing in ways that were aligned with their moral code or their values.
It was really about screening: about not owning tobacco, not owning gaming, not owning other types of companies that do harm.
Externalities
This movement grew in the first part of the 2000s around the concept of “externalities”.
Externalities is an economic concept that refers to an activity’s second and third-order effects on the broader ecosystem.
It is best illustrated by an economic problem known as “the Tragedy of the Commons”, which was first talked about in the early 19th century by an English economist, William Forster Lloyd.
Lloyd observed that if I graze my cattle on common land, it’s in my interests to put more cattle on the land. But if everyone did that, acting in their own best interests, the external impact was the devastation of the land for everybody.
So there was a conflict between your internal motivations and what’s best for society — and ultimately for you in the long term.
Now we recognise pollution is an externality. We recognise supply chains generate externalities. Even employment generates externalities.
Little by little, as we became more sophisticated, we understood you could measure those externalities — and they weren’t free. The costs were borne by society.
As regulation evolved and as we became more aware of externalities, it became clear they ended up affecting your earnings over time — as regulations shifted or consumer demand changed.
And that ultimately leads to a change in your cost base.
A good friend of mine from asset consultant Willis Towers Watson wrote a wonderful article that said “past performance is not even a good guide to past performance”.
What he means is the performance of stocks and securities over a period of time is not fully reflective of the true, intrinsic earnings of those companies — because they didn’t factor in a lot of the externalities those companies were generating.
A good example is tobacco.
Tobacco was the best-performing sector in the world over the last century. I don’t think that will be the case over the next century. But the reason why it performed so well in the past is that as a society we didn’t understand the externalities.
We didn’t understand the impact of the products being sold. We weren’t factoring that properly into an assessment of the companies.
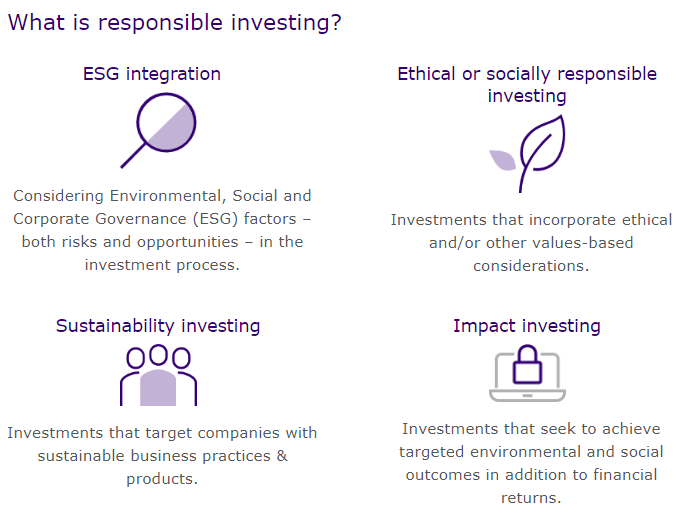
Environmental, Social and Governance (ESG) factors
So the United Nations principles for Responsible Investments grew and the emphasis on this new idea of ESG — environmental, social and governance criteria — became an idea around long-term risk management.
ESG recognised that if these externalities are real — and if we expect over time they will be increasingly factored into the price of securities — then as investors we should start thinking about these factors now.
It wasn’t about values. It wasn’t about what you believe is right or is wrong. This evolution from ethical investing to ESG was in its early incarnation about long-term risk management of making an investment decision.
Sustainable investing
Then things evolved another step.
We recognised these externalities — these second and third-order impacts — were real. And as investors we recognised the potential to build portfolios in a way that was more sustainable and recognised the impact of these externalities.
We could build a “sustainable portfolio” that not only managed ESG risks and factored them into the pricing of securities. It could also bias a portfolio towards more sustainable companies or sectors over time.
Why might you do that? There are two reasons.
You might believe there’s an alpha source there. You might believe those sorts of companies will perform better over time.
As consumer behaviour changes, they’ll be more attracted to products and companies that are sustainable. Companies that are less sustainable will actually do worse over time.
The other reason is because you want your capital to be invested in positive ways.
This is happening more and more. Sustainable investing is one of the fastest-growing parts of the investment management universe.
About nine out of 10 Australians in recent Roy Morgan research have said they expect their investments to be managed in a sustainable way.
That is something we really can’t ignore.
Impact investing
But there’s a final step to this — and that is impact investing.
Impact investing not only recognises those externalities, it deliberately builds a portfolio targeting the creation of positive externalities.
It’s not simply asking: “is this a sustainable company in a sustainable industry?” It’s recognising a company can generate very positive and profound outcomes for the world.
Impact investing is about targeting those sorts of investments and then measuring the outcomes beyond the financial returns of the company.
Impact investing is the point of the arrow. This is the bit where we actually recognise that capital has real power and that all of us — financial advisors, fund managers, asset owners — are in a very unique position.
We are in a position of responsibility. A position to operate as fiduciaries recognising the way we invest matters.
There is a purpose to our financial system. The purpose is not money in its own right. It’s not an end in of itself.
The purpose is to channel capital towards productive enterprise and to create our future.
There’s about $130 trillion globally that sits in pension funds, super funds, sovereign wealth funds advised by financial advisors, fund managers, insurance companies. That’s almost twice the value of annual global GDP.
The way that money is invested will help shape the world that your clients and you and me will retire into.
That makes impact investing hugely important for us as fiduciaries, advisors and allocators of capital.
This is about our growth as investors — as humans recognising the world is not two-dimensional. It is a complex, adaptive system.
The third axis
We can think of this as the third axis of investing.
In the beginning there was one axis — returns. Back in the 1940s and 1950s we really only spoke to our clients about the returns we generated.
Then with modern portfolio theory the idea of risk emerged and we had two axes — risk and return.
Today it seems like madness to think about return without understanding the risk we’re taking to get that return. But it was always there — we just didn’t measure it.
Now we realise there is a third axis — the impact of the investment or the company or government we are lending money to.
Again — the third axis was always there. We just didn’t measure it like we are starting to do now.
Pendal and Regnan
We helped found an organisation called Regnan, which is now one of the leading ESG research and engagement providers in Australia.
Regnan’s business originated with work done in conjunction with Monash University in Melbourne in the 1990s to think about the impact of environmental change on company earnings.
Recently, Pendal bought out our other Regnan partners to bring it a lot closer to our investment decision-making.
We’re now using Regnan to grow the impact investing space.
We recently launched a product called the Regnan Credit Impact fund, which lends money to investment-grade borrowers, governments, super nationals and corporates for green and social bonds. Then we measure the outcomes of all that lending.
Even at launch with a small initial seeding of $30 million, the fund is already taking something like 13,000 tons of carbon dioxide out of the atmosphere on an annual basis.
It’s restored 60 hectares of forests.
It’s generated 16,000 megawatts of renewable energy a year.
It’s provided 340 jobs.
It’s created 50 loans to female-owned small enterprises.
And all of that with high-quality, investment grade credit paying strong returns.
So you’re getting liquidity and high-quality, investment-grade credit. And at the same time these externalities are being measured and targeted.
For us, that’s a huge leap.
Pendal sustainable funds
Pendal offers a range of sustainable products across different asset classes. We have been doing this for a long time and they are well-rated.
- Pendal Sustainable Balanced – Est. 1984 – Diversified/Multi-Asset
- Pendal Sustainable Conservative – Est. 1989 – Diversified/Multi-Asset
- Pendal Ethical Share – Est. 2001 – Australian Equities
- Pendal Sustainable Australian Share – Est. 2001 – Australian Equities
- Pendal Sustainable Australian Fixed Interest – Est. 2016 – Australian Fixed Income
- Pendal Sustainable International Fixed Interest – Est. 2016 – International Fixed Income
- Pendal Sustainable International Share – Est. 2016 – International Equities
- Pendal Sustainable Future Australian Shares SMA – Est. 2018 – Australian Equities
Regnan funds
This year we are launching high-impact investment strategies globally under our Regnan brand:
- Regnan Credit Impact Trust – Est.2020 – Australian Fixed Income
- Regnan Global Equity Income Solutions – To be launched in late 2020 – Global Equities
Richard Brandweiner is Pendal’s Chief Executive Officer, Australia. Richard has more than 20 years of experience in investment management and is responsible for the Australian arm of Pendal Group, including asset management, operations, sales and marketing.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
https://www.pendalgroup.com/about/our-people/sales-team/