
Get set for a 2024 that flips the script on the story of 2023, with the end of big tech outperformance and a resurgent Japanese yen. CHRISTOPHER LEES explains
- Magnificent Seven peaking
- Japanese yen set for recovery
- Find out about Pendal Global Select Fund
Lees – speaking above via video update to holders of the Pendal Global Select fund – says 2024 is shaping to provide a number of ‘vice versa’ performances when compared to 2023.
Apart from the end big tech’s outperformance, the year is also likely to be characterised by a peak in US market outperformance as emerging markets take the lead, and renewed strength from the historically weak Japanese yen.
These changes have profound implications across equities, fixed income and currency markets, says Lees.
Pendal Global
Select Fund
Something very
different in
global equities
“In 2023, the US improved and emerging markets deteriorated. That’s one of the first things we think might be a vice versa in 2024 with the US economy slowing and emerging market earnings recovering.”
Lees says emerging markets inflation rates are falling and emerging market interest rates still have quite a way to come down. Meanwhile, cyclical indicators in emerging markets are recovering very strongly.
“We expect emerging market earnings to recover very strongly as well,” he says.
“So you put those two things together, the prospect of falling interest rates and accelerating earnings growth in emerging markets and that’s why we think emerging markets will perform much better in 2024 than they did in 2023.”
Lees says another change could come from the end of historical weakness in the Japanese yen, which is trading at a 50-year low relative to other major currencies.
“The Bank of Japan was the last central bank with negative interest rates. Many people think that will change in 2024.
“Recently we’ve seen the Fed do a dovish pivot on interest rates and we’ve seen the Bank of Japan loosening yield curve control.
“Both of those we think are early warning signs and very, very bullish for the Japanese yen in 2024.”
Find out more about Pendal Global Select Fund
Hear more from Pendal Global Select Fund portfolio managers Chris Lees and Nudgem Richyal:
- Fast podcast: What makes this cycle different – and which data investors should be watching
- Fast podcast: How to find opportunity in global equities right now
- Webinar: Listen to an in-depth webinar with Chris and Nudgem (registration required)
- Article: A different path to the summit: Chris Lees and Nudgem Richyal launch Pendal Global Select Fund in Australia
- Article: Everyone’s looking for something different in global equities. Here’s how to find it
- Article: Two of us: Pendal global equities fund managers Chris Lees and Nudgem are ‘Yin and Yang’
About Chris Lees and Nudgem Richyal
Chris Lees and Nudgem Richyal are senior fund managers of Pendal Global Select Fund. The pair have been working together as investment managers for more than 20 years.
Chris has more than 32 years of investment industry experience. He joined Pendal Group’s UK-based asset manager J O Hambro Capital Management (JOHCM) in 2008 after spending 19 years at Baring Asset Management, ultimately as head of its global sector team.
Nudgem has 22 years of industry experience, joining JOHCM with Chris in 2008. He was previously an investment director with the Global Equity Group of Baring Asset Management, where he worked closely with Chris since 2001.
* Source: JO Hambro, Morningstar universe – Global Large-Cap Growth Equity funds, Lipper survey – Sector quartile ranking: IA Global, and Lipper Global Equity Global domiciled in the UK, offshore Ireland, or offshore Luxembourg. Lipper ranking is from A GBP Class. Please note that these performance figures have not been calculated in accordance with the Financial Services Council (FSC) standards.
About Pendal Global Select Fund
Pendal Global Select Fund is a global equities portfolio with a distinctive, yet proven approach and a 17-year track record of outperformance. Since its inception, the underlying strategy (JOHCM Global Select Fund) has delivered top-decile performance in Lipper and 2nd decile in Morningstar.*
This presentation has been prepared by Pendal Fund Services Limited (PFSL) ABN 13 161 249 332, AFSL No 431426. It is not to be published, or otherwise made available to any person other than the party to whom it is provided. PFSL has appointed J O Hambro Capital Management Limited (JOHCML) as the investment manager of the Fund. JOHCML is a wholly owned subsidiary of Perpetual Limited and a related party of Pendal Institutional Limited. Pendal Institutional Limited has appointed JOHCML as its authorised representative (Representative number 001280039) under its Australian Financial Services Licence.
PFSL is the responsible entity and issuer of units in the Pendal Global Select Fund (Fund) ARSN: 651 789 678. PFSL has appointed J O Hambro Capital Management Limited (JOHCML) as the investment manager of the Fund. JOHCML is a wholly owned subsidiary of Perpetual Limited and a related party of Pendal Institutional Limited. Pendal Institutional Limited has appointed JOHCML as its authorised representative (Representative number 001280039) under its Australian Financial Services Licence.
A product disclosure statement (PDS) is available for the Fund and can be obtained by calling 1300 346 821 or visiting www.pendalgroup.com. The Target Market Determination (TMD) for the Fund is available at www.pendalgroup.com/ddo. You should obtain and consider the PDS and the TMD before deciding whether to acquire, continue to hold or dispose of units in the Fund.
An investment in the Fund is subject to investment risk, including possible delays in repayment of withdrawal proceeds and loss of income and principal invested.
This presentation is for general information purposes only, should not be considered as a comprehensive statement on any matter and should not be relied upon as such. It has been prepared without taking into account any recipient’s personal objectives, financial situation or needs. Because of this, recipients should, before acting on this information, consider its appropriateness having regard to their individual objectives, financial situation and needs. This information is not to be regarded as a securities recommendation.
The information in this presentation may contain material provided by third parties, is given in good faith and has been derived from sources believed to be accurate as at its issue date. While such material is published with necessary permission, and while all reasonable care has been taken to ensure that the information in this presentation is complete and correct, to the maximum extent permitted by law neither PFSL nor any company in the Pendal group accepts any responsibility or liability for the accuracy or completeness of this information.
About Pendal
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management. Pendal Group includes Pendal Australia, J O Hambro Capital Management, Regnan and Thompson, Siegel and Walmsley (TSW).
Deglobalisation, digitisation and decarbonisation are the three global megatrends that will dictate portfolio returns post-Covid, says Pendal portfolio manager Chris Lees
- Deglobalisation, digitisation, decarbonisation are key trends
- Look for ‘good stocks in good neighbourhoods’
- Find out about Pendal Global Select Fund
THREE global megatrends will drive stock markets returns in coming years: deglobalisation, digitisation and decarbonisation, says portfolio manager Chris Lees, who oversees Pendal Global Select Fund with Nudgem Richyal.
The concept of megatrends driving returns forms part of Lees’ and Richyal’s highly differentiated, high-conviction global equities strategy.
“Global megatrends transcend sector, they transcend geography,” says Lees, speaking at a Pendal webinar introducing the Global Select fund. The fund was awarded a Zenith “Highly Recommended” rating on September 27, 2021.**
“Deglobalisation, digitisation and decarbonisation are three of the biggest megatrends that we see — and they are all accelerated by Covid.
“These mega, long-term themes are beginning to reassert themselves as the market moves on from Covid bounce recovery plays. It’s now mid-cycle and the market is now really beginning to be driven by these trends.”
Lees says the three themes play off each other to cause a “triplification” effect on markets: “There’s a huge capex boom ahead,” he says.
The megatrends view of investing forms part of Lees’ and Richyal’s longstanding investment process which takes broader themes into account rather than simply stock-specific factors.
“What we try to do is very similar to real estate investing,” says Lees.
“If you buy a good house in a rapidly deteriorating neighbourhood, you’re not going to make much money.
Pendal Global
Select Fund
Something very
different in
global equities
“The way make really good money over the long term in real estate investing is look for the improving neighbourhoods.
“The stock market is exactly the same… We go looking for good stocks and fixer-upper, improving stocks in rapidly improving neighbourhoods.”
Lees says the history of global investing shows big themes drive markets.
In the 70s, successful investing was about tilting portfolios to gold. The 80s were about Japan. The 90s were about the NASDAQ. The early 2000s were about iron ore and the 2010s about the US tech stocks.
“Bubbles are fun early on. That’s where you make money. The concept is tilting into the new neighbourhood — the new bubble,” says Lees.
“People who view the stock market as mean reversion are mathematically correct, but they’re implementing wrong,” he says.
“A much better way to look at markets is extreme reversion — markets go from one extreme to the other, from fear to greed, from fear to greed.”
Richyal says the trick to successful portfolio management is taking an equal weight approach in a portfolio and weeding out the losers ruthlessly.
“What we can do is mitigate our own foibles by doing it this way.
“We are trying to mitigate the endowment effect — the concept that we as human beings assign more value to something we possess than what somebody else would pay for it.”
Find out more about Pendal Global Select Fund
** The Zenith Investment Partners (ABN 27 103 132 672, AFS Licence 226872) (“Zenith”) rating (assigned ) referred to in this document is limited to “General Advice” (s766B Corporations Act 2001) for Wholesale clients only. This advice has been prepared without taking into account the objectives, financial situation or needs of any individual and is subject to change at any time without prior notice. It is not a specific recommendation to purchase, sell or hold the relevant product(s). Investors should seek independent financial advice before making an investment decision and should consider the appropriateness of this advice in light of their own objectives, financial situation and needs. Investors should obtain a copy of and consider the PDS or offer document before making any decision and refer to the full Zenith Product Assessment available on the Zenith website. Past performance is not an indication of future performance. Zenith usually charges the product issuer, fund manager or related party to conduct Product Assessments. Full details regarding Zenith’s methodology, ratings definitions and regulatory compliance are available on our Product Assessments and at http://www.zenithpartners. com.au/RegulatoryGuidelines
About Chris Lees and Nudgem Richyal
Chris Lees and Nudgem Richyal are senior fund managers of Pendal Global Select Fund. The pair have been working together as investment managers for more than 20 years.
Chris has more than 32 years of investment industry experience. He joined Pendal Group’s UK-based asset manager J O Hambro Capital Management (JOHCM) in 2008 after spending 19 years at Baring Asset Management, ultimately as head of its global sector team.
Nudgem has 22 years of industry experience, joining JOHCM with Chris in 2008. He was previously an investment director with the Global Equity Group of Baring Asset Management, where he worked closely with Chris since 2001.
About Pendal Global Select Fund
Pendal Global Select Fund is a global equities portfolio with a distinctive, yet proven approach and a 17-year track record of outperformance. Since its inception, the underlying strategy (JOHCM Global Select Fund) has delivered top-decile performance in Lipper and 2nd decile in Morningstar.*
* Source: JO Hambro, Morningstar universe – Global Large-Cap Growth Equity funds, Lipper survey – Sector quartile ranking: IA Global, and Lipper Global Equity Global domiciled in the UK, offshore Ireland, or offshore Luxembourg. Lipper ranking is from A GBP Class. Please note that these performance figures have not been calculated in accordance with the Financial Services Council (FSC) standards.
About Pendal
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management. Pendal Group includes Pendal Australia, J O Hambro Capital Management, Regnan and Thompson, Siegel and Walmsley (TSW).
Pendal has brought a very different global equities strategy to Australia. Here fund managers Chris Lees and Nudgem Richyal explain the Pendal Global Select Fund process
- Something very different in global equities
- “Highly recommended” by Zenith (Sep 27, 2021)*
- Find out about Pendal Global Select Fund
CHRIS LEES and Nudgem Richyal have spent almost 20 years building a highly differentiated global equities investment strategy — and now it’s finally available in Australia.
Originally created in 2004 at Barings Asset Management, the global equities strategy features very different names to those that frequently dominate such funds.
The pair brought their strategy to Pendal’s UK-based asset manager JOHCM in 2008, where they built it into a US$5.3 billion fund.
After recently launching in Australia as Pendal Global Select Fund, Zenith awarded the fund its highest rating of “Highly recommended” (Sep 27, 2021).**
Yin and Yang
“If you asked clients about us, they would say ‘Chris and Nudgem are Yin and Yang’,” says Lees, a Londoner who now lives in a small village called Andermatt in the Swiss Alps.
“We both bring very different things to the process.”
Singapore-based Richyal says: “We feel unique because we are trying to combine this high-conviction, bottom-up stock picking within the context of top-down factors — particularly sectors and countries.
“It sounds glib, but it’s the Warren Buffet bottom-up stuff with the George Soros top-down stuff.”
A four-dimensional, ‘quantamental’ process
Lees uses the word “quantamental” — a merger of quanatitative and fundamental — to describe the the process.
“The first dimension is old-fashioned stock-picking via fundamentals. We are looking for good or improving companies.
“The second dimension is valuation. We want those companies in the right sectors at attractive valuations.”
Analysis of sector, country and other factors is important in this part of the process. “Think of it like real estate. Even the best home in a deteriorating neighbourhood can lose you money,” Lees says.
“Third, we buy shares when they’re going up, not down, because that’s the only way you can make money for your clients.”
Pendal Global
Select Fund
Something very
different in
global equities
A critical part of the third dimension is understanding key drivers of not only different sectors, but different geographies.
“Just look at China right now. It doesn’t really matter what stock you hold, it hasn’t worked out well,” Lees says.
“And the fourth dimension is about tomorrow. The world is always evolving. Nobody could have seen the exact impact of COVID, for example. The fourth dimension is where we are really good,” Lees says.
“We can map out very quickly the good houses in the good neighbourhoods and map out what’s changing over time,” says Lees.
“We quant-screen and that tells us what the best stocks are, what the best sectors are and what the best geographies are. We do that Monday morning — we call that three-two-one.
“Then we spend the rest of the week thinking about the fourth dimension — what’s changing, what’s evolving, which good areas are getting slightly worse. Which bad areas are getting slightly better?”
‘Open-source’ approach to investing
Lees and Richyal adopt what they call an “open-source” attitude to finding opportunities — a reference to the software development paradigm that draws on expertise form many sources.
The pair draws on the expertise of 50-plus investment professionals at Pendal’s UK-based asset manager JOHCM.
“Open source always wins in technology because it’s about taking ideas wherever you find them,” Lees explains.
“All the teams in JO Hambro are coming up with great ideas for us to take a look at.
Richyal says this philosophy is critical to their ability to outperform the benchmark.
“We don’t care about the provenance of the idea. If it’s interesting we will go and do our checks on it,” Richyal says. “That open-mindedness to ideas really helps.”
Rule of thumb
Often, they don’t agree about stocks.
“That’s part of our strength. We come at opportunities from slightly different ways,” Richyal explains.
“We have this rule of thumb about stocks. If it’s one minus one — one of us likes it, and the other doesn’t — it doesn’t get in,” he says.
“If it’s one plus zero, that gets in if one of us can convince the other. Over time that’s where we’ve gotten the best results.
“But if it’s one plus one, those are the stocks that are usually at the end of their life,” Richyal says. “If it’s so obvious that we both really like it, it usually means there’s not much juice left.”
“And then there’s the minus one, minus one. They tend to keep underperforming.”
Lees agrees.
“If we’re both very bullish on something, we make good money on it but not really good money. Historically we’ve made most money where one of us is pounding the table bullish, whether it’s a stock or sector or geography or currency.
“In that case it’s good to have the other person’s scepticism in the room,” he says.
Ability to move fast
Agility is important, Lees says.
“By the time a large investment committee agrees on something, often the opportunity has gone. The real money is made where someone has spotted something early, and the rest of the room waits to gather more evidence.”
And given the breadth of the fund — global equities — there are relatively few stocks.
Hear more from Pendal Global Select Fund portfolio managers Chris Lees and Nudgem Richyal:
- Fast podcast: What makes this cycle different – and which data investors should be watching
- Fast podcast: How to find opportunity in global equities right now
- Webinar: Listen to an in-depth webinar with Chris and Nudgem (registration required)
- Article: A different path to the summit: Chris Lees and Nudgem Richyal launch Pendal Global Select Fund in Australia
- Article: Everyone’s looking for something different in global equities. Here’s how to find it
- Article: Two of us: Pendal global equities fund managers Chris Lees and Nudgem are ‘Yin and Yang’
“If you want to outperform the global index, you’ve had to own a narrow set of companies,” Lees says. “It’s always been that way.”
Over the past decade holding the big technology companies has meant outperformance, he says. The decade prior to that was about holding emerging markets and commodities, and then in the 1990s it was about holding technology, media and telecommunications companies.
Digitisation, decarbonisation and deglobalisation are the new themes.
Not wrong for long
Lees says critical to the fund is knowing when to sell stocks.
“It goes right back to what Einstein said when he was asked what the greatest discovery humankind had ever made. He said the power of compound interest,” Lees says.
“Most people still don’t understand that. If you are holding losers in your portfolio, you’re holding back the compounding effect.
Lees adds that it’s been proven that losing stocks carry on losing with greater persistency, and winning stocks carry on winning.
“Weed out the losers and let the winners run.”
Equal weighting
Just as critical is equal weighting of the portfolio’s 30-to-60 stocks.
“It tilts you away from large-cap growth over time and towards mid-cap value. And it’s systematic rebalancing. It forces you to trim you winners back to equal weight. And review your losers.”
Richyal says its about mitigating the endowment effect on the way down.
“That’s when you ascribe more value to something in your possession than its actually worth in the outside world. And on the upside, we’re trying to mitigate overconfidence bias.”
“We really believe that performance follows flows. And our process has been built to say where is the money going to go to? We aren’t trying to pre-empt that move. We are just fast followers and lock on to the trend.”
Find out more about Pendal Global Select Fund
*Source: JO Hambro, Morningstar universe – Global Large-Cap Growth Equity funds, Lipper survey – Sector quartile ranking: IA Global, and Lipper Global Equity Global domiciled in the UK, offshore Ireland, or offshore Luxembourg. Lipper ranking is from A GBP Class. Please note that these performance figures have not been calculated in accordance with the Financial Services Council (FSC) standards
** The Zenith Investment Partners (ABN 27 103 132 672, AFS Licence 226872) (“Zenith”) rating (assigned ) referred to in this document is limited to “General Advice” (s766B Corporations Act 2001) for Wholesale clients only. This advice has been prepared without taking into account the objectives, financial situation or needs of any individual and is subject to change at any time without prior notice. It is not a specific recommendation to purchase, sell or hold the relevant product(s). Investors should seek independent financial advice before making an investment decision and should consider the appropriateness of this advice in light of their own objectives, financial situation and needs. Investors should obtain a copy of and consider the PDS or offer document before making any decision and refer to the full Zenith Product Assessment available on the Zenith website. Past performance is not an indication of future performance. Zenith usually charges the product issuer, fund manager or related party to conduct Product Assessments. Full details regarding Zenith’s methodology, ratings definitions and regulatory compliance are available on our Product Assessments and at http://www.zenithpartners. com.au/RegulatoryGuidelines
About Chris Lees and Nudgem Richyal
Chris Lees and Nudgem Richyal are senior fund managers of Pendal Global Select Fund. The pair have been working together as investment managers for more than 20 years.
Chris has more than 32 years of investment industry experience. He joined Pendal Group’s UK-based asset manager J O Hambro Capital Management (JOHCM) in 2008 after spending 19 years at Baring Asset Management, ultimately as head of its global sector team.
Nudgem has 22 years of industry experience, joining JOHCM with Chris in 2008. He was previously an investment director with the Global Equity Group of Baring Asset Management, where he worked closely with Chris since 2001.
* Source: JO Hambro, Morningstar universe – Global Large-Cap Growth Equity funds, Lipper survey – Sector quartile ranking: IA Global, and Lipper Global Equity Global domiciled in the UK, offshore Ireland, or offshore Luxembourg. Lipper ranking is from A GBP Class. Please note that these performance figures have not been calculated in accordance with the Financial Services Council (FSC) standards.
About Pendal Global Select Fund
Pendal Global Select Fund is a global equities portfolio with a distinctive, yet proven approach and a 17-year track record of outperformance. Since its inception, the underlying strategy (JOHCM Global Select Fund) has delivered top-decile performance in Lipper and 2nd decile in Morningstar.*
About Pendal
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management. Pendal Group includes Pendal Australia, J O Hambro Capital Management, Regnan and Thompson, Siegel and Walmsley (TSW).
Elise provides fundamental company analysis for our Australian Equity large cap strategies. Elise previously worked as an investment analyst for US fund manager Cartica where she covered a variety of emerging market companies. Prior to Cartica, Elise worked in investment banking and corporate finance at JP Morgan and Ernst & Young. Elise holds a Bachelor of Commerce and Economics from the University of Queensland and is a member of the Institute of Chartered Accountants Australia.
Chris Lees and Nudgem Richyal have spent almost 20 years building a differentiated global equities strategy. Here’s their story
- Something very different in global equities
- “Highly recommended” by Zenith (Sep 27, 2021)**
- Find out about Pendal Global Select Fund
“MY KIDS call Nudgem the man with the funny ears because as they grew up, they kept seeing him on my computer screen with his headphones on,” says fund manager Chris Lees of his investing partner of more than 20 years, Nudgem Richyal.
Remote working? The pair have been doing it for years.
Richyal lives in London, while Lees resides in a small village in the Swiss Alps. At the time of this article they hadn’t been in each other’s physical presence since June 2020.
“None of this remote working is new to us,” Richyal explains. “We’ve been doing video calls for a long time.”
For almost 20 years the pair have overseen a highly differentiated, high-conviction global equities fund.
Lees and Richyal created their strategy in 2004 at London-based Barings Asset Management. In 2008 they brought it to Pendal Group’s UK-based asset manager J O Hambro Capital Management, where they built it into a US$5.3 billion fund.
After recently launching the strategy in Australia as Pendal Global Select Fund, research house Zenith awarded the fund its highest rating of “Highly recommended” (Sep 27, 2021).**
Pendal Global
Select Fund
Something very
different in
global equities
The strategy features very different names to those that frequently dominate global equity funds.
Yin and Yang
Lees describes his relationship with Richyal as Yin and Yang — two sides that make up a formidable investment team.
“It’s why we are better together,” Lees explains. “He is definitely not a mini-me. I tend to be big picture first, and then concepts and then drill into the details. I’m good at buying the dips in long-term compounding, great companies.
“Nudgem is details first. And once he’s happy with the details, he steps back and looks at the big picture in a way that many details people can’t.
“I’m very good at holding on to our long-term winners and he is very good at saying ‘actually things might be changing and we need to think about selling’,” Lees says.
“Nudgem has brought to the process a ruthless sell discipline.
“Instinctively I’m very good at buying and Nudgem is very good at selling.”
Path to success
Neither of them started in finance. Lees studied geography and Richyal studied chemistry.
Between Richyal’s second and third year at university, he undertook a work placement. One of his bosses suggested he should try banking rather than science and he soon got a job at British merchant bank Hill Samuel.
On his first day Hill Samuel owner Lloyd Banking Group merged with Scottish Widows — and the investment bank part of the business was going to move to Edinburgh.
“I didn’t want to go … so I got a job at Barings. As part of the traineeship I spent six months in the North American business and that’s where I met Chris.
“He’s a very bubbly personality,” Richyal says of his partner. “He’s an enthusiast and in the US office that wasn’t out of the ordinary. But that type of personality sticks out a little bit more in a UK context.”
While Richyal was still finding his way in the world of finance, Lees had long left geography behind and had nearly decade of experience when he met Richyal.
“When Nudgem was on his graduate program, I was just blown away by his raw intellect,” Lees says. “He’s one of the cleverest people I’ve had the privilege to meet.”
Lees had been asked to move back to London and build a global equities capability. He remembers his boss at the time said build a global equities process not on the way the world should be, but on the way the world is.
“Today those words are still so important. You never make money on should. You make money in an ugly, complicated, evolving, grey world,” Lees explains.
A new global investment process
“I asked Nudgem to help build this new global investment process from scratch based on the way the world actually is.”
Richyal liked the idea.
“I thought that it was a very interesting concept. I thought that was the most entrepreneurial choice to make at the time, and in hindsight I was right,” he says.
The two have been working together ever since.
Hear more from Pendal Global Select Fund portfolio managers Chris Lees and Nudgem Richyal:
- Fast podcast: What makes this cycle different – and which data investors should be watching
- Fast podcast: How to find opportunity in global equities right now
- Webinar: Listen to an in-depth webinar with Chris and Nudgem (registration required)
- Article: A different path to the summit: Chris Lees and Nudgem Richyal launch Pendal Global Select Fund in Australia
- Article: Everyone’s looking for something different in global equities. Here’s how to find it
- Article: Two of us: Pendal global equities fund managers Chris Lees and Nudgem are ‘Yin and Yang’
Sometimes they agree. Sometimes they don’t. In fact, they can be at polar ends of a debate.
“We can disagree about a stock or a sector. But that’s just part of the marriage,” Richyal says.
Lees said it wouldn’t work if they always agreed.
“If I wanted someone to agree with me, I would have employed a mini-me and we wouldn’t be very good.”
After more than 20 years is it still working?
“Nudgem has had job offers for more money,” Lees says. “He’s told me and said we were better working together.
“That’s commitment. I know we’re better together so we’re not splitting up anytime soon. We’re not going anywhere.”
Find out about Pendal Global Select Fund
*Source: JO Hambro, Morningstar universe – Global Large-Cap Growth Equity funds, Lipper survey – Sector quartile ranking: IA Global, and Lipper Global Equity Global domiciled in the UK, offshore Ireland, or offshore Luxembourg. Lipper ranking is from A GBP Class. Please note that these performance figures have not been calculated in accordance with the Financial Services Council (FSC) standards
** The Zenith Investment Partners (ABN 27 103 132 672, AFS Licence 226872) (“Zenith”) rating (assigned ) referred to in this document is limited to “General Advice” (s766B Corporations Act 2001) for Wholesale clients only. This advice has been prepared without taking into account the objectives, financial situation or needs of any individual and is subject to change at any time without prior notice. It is not a specific recommendation to purchase, sell or hold the relevant product(s). Investors should seek independent financial advice before making an investment decision and should consider the appropriateness of this advice in light of their own objectives, financial situation and needs. Investors should obtain a copy of and consider the PDS or offer document before making any decision and refer to the full Zenith Product Assessment available on the Zenith website. Past performance is not an indication of future performance. Zenith usually charges the product issuer, fund manager or related party to conduct Product Assessments. Full details regarding Zenith’s methodology, ratings definitions and regulatory compliance are available on our Product Assessments and at http://www.zenithpartners. com.au/RegulatoryGuidelines
About Chris Lees and Nudgem Richyal
Chris Lees and Nudgem Richyal are senior fund managers of Pendal Global Select Fund. The pair have been working together as investment managers for more than 20 years.
Chris has more than 32 years of investment industry experience. He joined Pendal Group’s UK-based asset manager J O Hambro Capital Management (JOHCM) in 2008 after spending 19 years at Baring Asset Management, ultimately as head of its global sector team.
Nudgem has 22 years of industry experience, joining JOHCM with Chris in 2008. He was previously an investment director with the Global Equity Group of Baring Asset Management, where he worked closely with Chris since 2001.
* Source: JO Hambro, Morningstar universe – Global Large-Cap Growth Equity funds, Lipper survey – Sector quartile ranking: IA Global, and Lipper Global Equity Global domiciled in the UK, offshore Ireland, or offshore Luxembourg. Lipper ranking is from A GBP Class. Please note that these performance figures have not been calculated in accordance with the Financial Services Council (FSC) standards.
About Pendal Global Select Fund
Pendal Global Select Fund is a global equities portfolio with a distinctive, yet proven approach.
About Pendal
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management. Pendal Group includes Pendal Australia, J O Hambro Capital Management, Regnan and Thompson, Siegel and Walmsley (TSW).
Rachel is an Investment Analyst for our Smaller Companies team, providing fundamental analysis on a range of companies within the ASX ex-100 universe. Previously, Rachel was an Investment Analyst covering smaller companies for NAOS Asset Management and First Sentier Investors, where she began her career in their graduate program. Rachel holds a Bachelor of Commerce (Actuarial Studies and Financial Economics) from the University of New South Wales and is a CFA Charterholder.
Michael is Head of Multi Asset for Perpetual Asset Management. In this role he is responsible for the suite of Multi Asset Funds and capital markets research.
Michael joined Perpetual in June 2014 and has 18 years finance industry experience. Prior to joining Perpetual Michael worked at JANA for 13 years, and held a number of positions across research, consulting and portfolio management, including Head of Investments, Implemented Consulting.
Earlier in his career Michael held a variety of positions at UBS, Morgan Stanley and Barclays Capital in both Australia and the United Kingdom.
Michael holds a Bachelor of Business (Economics and Finance) from RMIT University and is a Vincent Fairfax fellow.
Net zero is a megatrend that will define the business landscape for decades. Pendal analyst and co-portfolio manager Oliver Renton explains what it means for investors
- Net zero carbon emissions required to halt global warming
- Hydrogen and carbon capture the key technologies
- Find out about Pendal Focus Australian Share fund
NET ZERO has become a mantra for many businesses in recent months as governments and corporations outdo each other in their commitments to reducing carbon emissions and fighting climate change.
The noise will reach a peak at November’s United Nations climate change summit in Glasgow but arguably the real work to achieve net zero has yet to begin.
Every nation and every company will need to a play a role reducing carbon emissions to avoid the worst effects of global warming. That defines net zero as a megatrend that will define the planet for decades.
“There aren’t that many certainties in investing but the move towards Net Zero is one of them,” says Oliver Renton, an energy analyst at Pendal Group. “It’s a helpful framework in which to invest.”
But what exactly is net zero?
How does the world get there?
And what does it really mean for investors?
What is net zero?
Scientists agree it is unequivocal that human influence has warmed the planet and this can be attributed to increasing greenhouse gases in the atmosphere including carbon dioxide, methane and nitrous oxide.
These emissions are combined into a measure known as “carbon dioxide equivalents” and referred to simply as “carbon” for simplicity.
A wide range of human activities generate greenhouse gases including construction and manufacturing, generating electricity, agriculture, transport and heating and cooling.
To limit warming to 1.5 degrees Celsius above pre-industrial levels – a level scientists estimate to be safe – governments agreed in Paris in 2015 that carbon neutrality by the mid-21st century was essential.
Find out about
Pendal Horizon Sustainable Australian Share Fund
Net zero by 2050 refers to this goal of a mid-century point of neutrality where humans add no more greenhouse gases to the atmosphere than is removed.
Of course, net zero does not mean zero.
Greenhouse gases have always been emitted but historically emissions were absorbed into forests, oceans and soil and the cycle was roughly balanced.
Getting to net zero means carbon emitted by humans is balanced by carbon removed from the atmosphere.
How to get to net zero
There are essentially two ways the world can get to net zero carbon emissions, says Renton:
- Reducing demand for carbon producing activities, and
- Changing the way these activities are undertaken to eliminate emissions
But energy usage and economic growth are inextricably linked. Taking a demand-reduction approach to emissions generally means reducing living standards in prosperous countries and condemning much of the developing world to poverty. (There is of course energy efficiency available to aid in the move to net zero.)
“Developing countries want and deserve to live a more energy-intensive lifestyle,” says Renton.
“Energy poverty is an ESG [Environmental, Social and Governance] issue as much as the environmental impacts of carbon. So, it’s important to take a broad perspective.”
That means solving net zero predominantly falls to the supply side.
The role of energy
Almost all aspects of human society use energy. Right now 80 per cent of the world’s energy supply comes from carbon-emitting fossil fuels, chiefly oil, coal and gas, says Renton.
The remaining 20 per cent comes from non-carbon emitting sources like nuclear, hydroelectricity and renewables.
Importantly, for all the focus on electric vehicles, only about quarter of energy use is transport and only half of that is passenger vehicles.
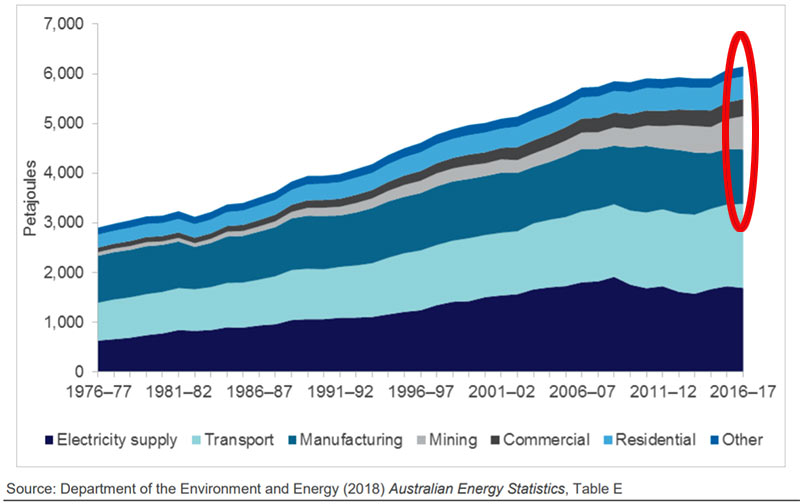
In Australia, the bulk of energy consumption is electricity generation. Other big energy users are manufacturing and mining, the retail and services industries and households.
Australian energy consumption by sector (2018):
So where does that leave net zero?
“We have pretty good solutions for electricity supply and transport in the form of renewables and batteries,” says Renton.
“But half of energy consumption is considered hard to abate and thousands of different solutions will be required.”
One way to analyse how these solutions could play out is to follow how energy is delivered to end users.
Electricity is only one way energy is delivered – and represents about 20 per cent of global energy demand. The 80 per cent remainder is still dominated by oil, coal and gas.
“Even under the best scenarios, electricity only gets to 30 or 40 per cent share – it’s just not feasible to electrify everything,” says Renton.
“So, we still need a solution for transportable liquid or gas forms of energy.
“This is a very interesting insight – because at the moment, the net zero commodity that can be used to transport energy does not exist in a commercial way.”
Technology solutions
The answer to this puzzle lies with technology.
“We’re going to need technological breakthroughs throughout the whole system. But historically, we underestimate the effect of technological change and miss the big picture,” says Renton.
Solar is a case in point. Innovation is driving prices down so rapidly that the solar industry achieved cost milestones some two decades ahead of forecasts.
“It’s pretty unbelievable – and that trajectory can probably be applied to various other aspects of the energy transition.”
The two big hopes for net zero transportable energy are two relatively immature technologies: hydrogen and carbon capture and storage (CCS).
And their prospects are interlinked.
Hydrogen theoretically solves the problem of a transportable, net zero emissions energy source.
Hydrogen is the most abundant and simplest element in the universe and is safer than conventional fuels. It can be manufactured and when burned emits nothing but energy and water. It can be delivered though gas pipelines and used to fuel vehicles.
But, for the foreseeable future, it is too expensive to compete as a fuel.
And worse, depending on how it is made, the hydrogen manufacturing process itself creates carbon.
There are two ways to make hydrogen. The more expensive way is using electricity to split water – a net zero activity only if the electricity itself is carbon free. The cheaper way is to split it from natural gas using steam, but this process produces carbon dioxide as a by-product.
2021 Money Management of the Year Awards
Pendal Australian Shares Portfolio
Winner – SMA Australian Equities
Pendal Property Investment Fund
Winner – Australian Property Securities
The solution? Capturing the carbon emissions and storing them so they cannot add to greenhouse gases in the atmosphere.
This carbon capture and storage (CCS) is the second leg in the net-zero technology race. It quite literally involves a process that captures carbon dioxide from the air — it is in use in fossil fuel power generation and industry.
But its track record is patchy, and the current economics are not promising at mass scale.
“There’s scepticism about carbon capture and storage but it is in everyone’s forecasts to get to net zero,” says Renton.
What does this mean for investors?
Capital markets have already moved in line with net zero.
The cost of capital for fossil fuel energy companies is rising and net zero shareholder resolutions are on the rise.
All evidence shows the energy transition and the drive towards net zero has enormous momentum.
“But energy and fossil fuels have been inextricably linked to GDP and the decoupling will be difficult,” says Renton.
Renton says the challenges facing hydrogen and carbon capture and storage are only resolved in a world where the carbon price is high enough that projects become economic in a timeframe that allows the world to meet its 2050 goals.
“That’s one of the main conclusions for investors — the implicit or explicit price of carbon is going up and it’s really the only solution.”
This means projects that can efficiently reduce carbon emissions are going to be highly valuable.
Ironically, one of the best avenues for investors could be the natural gas industry, which can produce energy at half the emissions intensity of coal.
“We have confidence than the market for gas is there for the medium term, but the focus should be on top-tier projects or projects that complement CCS” says Renton.
Keep an eye on the energy transition
Renton also cautions investors about taking an all-or-nothing approach to assessing investments, saying some fossil fuel companies have the skills, assets and customer base that will allow them to play an important role in the energy transition.
“Look at the fuel companies that distribute fuel on behalf of society — even if we switch to hydrogen these are still difficult substances to deal with. Who are going to be the natural companies to deal with this? They have the skills and existing assets like pipelines and ports that all become very important.
“It’s too narrow a view to label this a dead asset class.”
He says investors should seek out companies with strong management, governance, capital positions, assets that have value in a renewable world and favourable industry structures that will allow them to best hold margins in times of change.
“And look for carbon capture opportunities that can take advantage of a higher carbon price,” he says.
The conclusion? Investors cannot afford to be ideological about net zero.
“The oil and gas companies are the ones that are genuinely going to be the drivers of change – they are the ones developing and distributing hydrogen and the ones capturing and storing carbon.
“Don’t give up on the energy sector – that could be a very poor outcome for the world.”
About Oliver Renton
Oliver is an analyst and co-portfolio manager with Pendal’s Australian equities team. He has more than 15 years of industry experience and focuses on utilities and health care.
About Pendal Group
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
We believe sustainability considerations ultimately drive higher and more stable investment returns over the long term.
Pendal Group has a proud heritage in responsible investing, extending back decades. Our specialist responsible investing business Regnan includes highly experienced ESG research and engagement experts and offers a growing range of investment strategies.
Find out about some of our responsible investing strategies: