
This week Canada’s central bank become the first to signal its stimulus exit. Pendal portfolio manager Tim Hext explains what it means for Australian investors
- Vimal Gor: Bond sell-off looks to have run its course
- Vimal Gor: how to think about the role of bonds in a portfolio right now
- Find out more about Pendal’s fixed interest strategies
WE WOKE on Thursday to headline news that the COVID economic crisis was over — even as the health crisis worsened in some parts of the world.
The Bank of Canada (BoC) released its monetary policy report — becoming the first to signal its stimulus exit.
So what has Canada done? Have we moved past the economic impact? If so, what does that mean for Australian investors?
The BoC is paring back the level of bond purchases in its Quantitative Easing (QE) program from Wednesday. It’s a sign the BoC no longer thinks it needs to prop up the economy.
The numbers have been encouraging. The March 2021 CPI increased 2.2% against the COVID lows of March 2020. The February 2021 CPI print was up 1.1% against pre-COVID price levels of February 2020.
There is confidence in the Canadian recovery based on the economic data post-lockdown.
There were substantial job gains in February and March. Stronger commodity prices. Fewer business insolvencies coupled with high business confidence. And a rapid surge in house prices: 17% across Canada and 20% in capital cities such as Toronto.
It is almost a mirror image of our own recovery here in Australia.
Now the question is: will the RBA taper as well? And if so, when?
It isn’t surprising that the developments in Canada sparked a flurry of discussions. But it turns out we have forgotten to read the pesky fine print. Again!
In Australia, the RBA’s main objectives are:
- Inflation between 2% to 3%, on average, over a business cycle
- Full employment
- Stability of the Australian currency
In Canada, the BoC has a single objective to hit a 2% inflation target — not over a business cycle, but at a point in time. There are no unemployment objectives. No currency objectives.
The BoC prefers not to walk, talk and chew gum at the same time.
The similarities between Australia and Canada’s recovery may seem uncanny (although Australian housing prices have risen only a mere 6% compared to Canada’s 17%).
But there are stark differences.
The BoC has shown more willingness to tackle inflation while there is still a fair amount slack in the Canadian economy. In contrast, the RBA is reluctant to dampen growth until our unemployment numbers are into the lows 4s.
Additionally, with the AUD/USD currently range-bound between 0.75 and 0.8, it’s difficult to see the RBA charting a similar course to the BoC.
Until the pied piper of inflation plays his tune, it appears unlikely the RBA will be lured away from its current path.
Maybe keep the champagne on ice just a little longer.
Tim Hext is a portfolio manager with Pendal’s Bond, Income and Defensive Strategies (BIDS) team.
Led by Vimal Gor, Pendal’s BIDS boutique is one of the most experienced and well-regarded fixed income teams in Australia. In 2020 the team won the Australian Fixed Interest category in the Zenith awards.
The team oversees $22 billion invested across income, composite, pure alpha, global and Australian government strategies with the goal of building Australia’s most defensive line of funds.
Find out more about Pendal’s fixed interest strategies here
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Contact a Pendal key account manager here
Here’s what’s driving Australian equities this week according to Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
- Crispin Murray names the big policy shifts driving equities
- Find out about Pendal’s Focus Australian Share Fund here
THE COUNTERTREND bond rally continued last week, pushing down yields and supporting a continued recovery in growth and defensive stocks.
It is worth noting the market overall has risen in both environments. The ASX 300 was up 4.2% in Q1 when yields were rising and it is up another 4.2% quarter-to-date with yields falling.
This highlights the market’s breadth. The laggard sectors have held up reasonably well in both the value and growth-dominant legs, allowing the overall market to rise. This reflects high levels of underlying liquidity and the continued chase for returns.
The S&P/ASX 300 gained 1% for the week and the S&P 500 was up 1.4%.
The question now is how long the bond rally phase can continue. More on that below, but at a high level we believe the move lower in yields will be limited and bond yields are likely to return to their higher levels within three months.
The bond market rally
There have been five key drivers of the recent rally in bonds, in our view:
-
- Positioning: There was a strong consensus position and very crowded trade long recovery and re-opening plays and short defensive assets like bonds in Q1.
- Yield differential: The yield pick-up for European and Japanese investors buying US treasuries hedged back to domestic currency was at its highest levels for five years.
- Peak growth approaching: In terms of the second derivative – the rate of growth — this peaks in April and early May and slows thereafter.
- Covid spike: Cases are picking up in US and big emerging markets such as Brazil, India and Chile. There are also renewed fears about Covid variants.
- Vaccine safety concerns: The Johnson & Johnson vaccine has now also been linked to blood clots, leading to a temporary suspension in the US.
Covid and vaccine issues
Looking at points four and five above, we believe there are some material medium-term risks for the management of Covid and full global re-opening. But the near-term trends are supportive enough to avoid any breaking down of the current re-opening economic recovery.
In the EU new daily cases remain elevated. The seven-day average is more than 300 people per million compared to fewer than 200 in the US and about 100 in the UK. There are signs this number is stabilising in the EU.
Brazil is surging and is now running just ahead of the EU. Given low rates of testing there, the real number is probably 50% more.
There is some focus on Manaus where some 70% of the population already had Covid — but people are being re-infected with the Brazilian strain (P1). This highlights concerns with the duration of immunity.
Adding to the confusion a new double mutant strain has been reported in India. So far no one knows if it is more resistant to vaccines.
Regarding the surge in Covid cases, the key point is we will achieve herd immunity later than many expected. The outlook for emerging markets in particular has declined. This means a more subdued medium-term global re-opening recovery, which means monetary policy remains looser for longer.
Vaccine duration
The debate over how long vaccines remain protective is important in this context.
Pfizer released data indicating the average effectiveness of its vaccine was 91% over six months. While ostensibly a good number, given it starts at 95% this implies effectiveness is falling into the 80s by the end of the period.
This is backed up by studies showing the presence of relevant antibodies has fallen by two-thirds (for people in the 18-55 year cohort) over that period. For people in the older age cohorts, the degree of antibody decrease is greater still.
This still leaves enough antibodies for the vaccine to be considered effective against the original strain after six months, although for people above 70 years old it is getting closer to the cut-off mark.
However it’s believed the degree of relevant antibodies is deflated by a material factor in the case of the South African and Brazilian variants. It’s unclear if older populations would still be immune after six months.
There is a degree of complexity in measuring the presence of antibodies and rates of decline, particularly among different types of vaccines.
There can be no conclusion on the Covid outlook at this point, but we can make some inferences:
-
- Covid is likely to remain an endemic disease like the flu. It will remain prevalent and disease management will be an important focus.
- Re-opening international borders is likely to be more complicated than expected. New variants are one issue. So is the fact that we will have people with different vaccines received at different times. There is no homogenous standard to assess people’s risk of getting the disease.
- The need for booster shots will continue for some time. Hence Pfizer’s comments regarding the need for a third shot.
The investment consequences of this are complex. One outcome is a dispersion in performance within cyclicals in the US. Domestic cyclicals are outperforming global cyclicals given the issues in both the EU and emerging markets.
Positive near-term news on Covid
These are all medium-term issues. In the near term, developments have been positive on balance, despite the issue with the Johnson & Johnson vaccine.
In Europe, vaccination rates are now dialling up and supply issues are being resolved. The EU is about two to three months behind the US in terms of the vaccine roll-out.
At this point the increase in US Covid cases remains relatively muted, despite a sharp spike in Michigan. The vaccination rate remains at record levels and more than 80% of over-65s have had at least one shot.
The manufacturing capacity of the Moderna vaccine looks set to meet demand requirements. This helps alleviate concerns with other vaccines, though it has run into some supply issue outside the US. At this point we expect concerns over vaccines — which have helped drive bond yields down — should not persist.
Economics and policy outlook
Returning to drivers of the recent bond rally, we believe the strength of the economy will prove more durable than the market expects.
Therefore the peak growth argument for buying bonds will not be sustained.
Data suggests the US economy is booming and this is flowing through into the rest of the world. Consumer spending is at record levels, supported by a surge in consumer net worth and the economic re-opening. The question is how sustainable this is, in the context of an expected peak in the next month.
Our first observation is that the increase in net worth extends well beyond the top decile by wealth. The top 10% of the US by wealth has seen a total 30% increase in net worth, but the next 40% have seen a 33% increase. This is important because it includes income groups that are more likely to spend than save.
This is flowing through into spending plans. Recent survey data asking about expected spending one year out has surged, indicating that consumer spending could extend for longer than expected.
Another reason is that we are seeing household net worth rise at the same time that household debt has fallen materially — from about 105% of GDP to about 75%. The starting point for the savings rate is also very high.
This is fundamentally different to the post-GFC era. Then households had run down savings rates and built up debt, so consumption faced a double headwind as savings rates rose to repay debt. The opposite could happen this cycle.
Meanwhile we are in an environment where households are still covering their spending with wages, ie they are still not eating into the estimated US$3 trillion of excess saving.
In addition, companies are reporting record low levels of inventory as they struggle to meet demand. This suggests they will need to re-build inventories in future quarters. Some of this is being constrained by supply bottlenecks (eg in auto), so this also helps extend the cycle.
Housing also continues to boom. Low rates are a cyclical tailwind, but structural factors are just as important. Housing formation declined materially post-GFC. We are now seeing a supply response to address the current underbuild, which is also supported by aging Millennials and the work-from-home trend. This provides a more sustainable platform for on-going economic strength.
The point here is that the expectation of a peak in growth, as a driver of recent bond strength, is more about sentiment. We expect continued economic strength, evidence of supply chain bottlenecks and some emerging inflation pressures in the next here months.
In this environment it is hard to see real rates staying at -1% and anchoring bond yields at current levels.
Markets
There are a few broad observations on equities at this point.
- The correlation between the yield curve and performance of defensives versus cyclicals and growth versus value has been very clear in recent weeks. If we get a reversal in recent bond rally we should see the value and cyclical trade resume.
- Equity market volatility continues to be supressed. This is worrying some people who believe it’s being held down artificially by central banks. If it continues this should help bolster confidence in equities. It also potentially encourages more equity positioning in risk parity strategies.
- There is not yet any negative signal from credit spread, which have hit post-GFC lows. We see this as correlated with equity valuations.
Last week we got the trifecta of bonds, commodities and equities rallying together. The US dollar also began to roll over, which supports commodities.
Australia, like the rest of the world, last week saw growth stocks lead in what was otherwise a broad rally. Names like Xero (XRO, +5.9%), CarSales.com (CAR, +5.1%), Afterpay (APT, +4.9%), NextDC (NXT, +4.5%) and Wisetech (WTC, +3.8%) were among the best performers in the ASX 100.
About Crispin Murray and Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia.
Crispin’s Pendal Focus Australian Share Fund has beaten the benchmark in 12 years of its 16-year history (after fees), across a range of market conditions , as this graph shows:
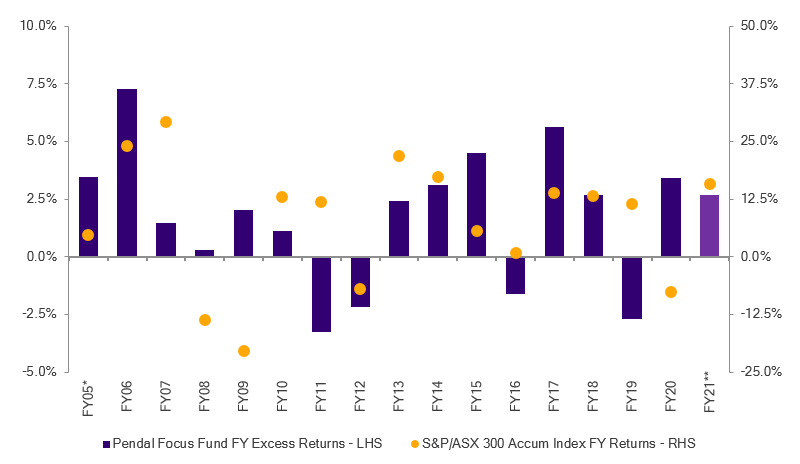
Source: Pendal. Performance is after fees and before taxes. *From 01 Apr 05; **as at 28 Feb 21. Past performance is not a reliable indicator of future performance.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about Pendal Focus Australian Share Fund here.
Sustainable investing leader Regnan has analysed the environmental impacts of hydrogen production in a new research report aimed at investors.
Regnan’s H2 beyond CO2 report reviews popular hydrogen production technologies and identifies factors that may lead to competitive advantages and potential constraints.
The report — produced by Regnan’s Abby Frank, Alison George, Maxime Le Floch and Oshadee Siyaguna — can be downloaded here.
-
- Hydrogen production shows strong potential for investors but there are issues to be managed
- Investors can identify key factors that will influence winners and losers
- Listen to an interview with the report’s authors on Decarb Connect podcast
- Find out more about Regnan or contact Jeremy Dean at jeremy.dean@regnan.com
THERE’S a lot of excitement among investors, scientists and politicians about the scope for hydrogen to be a major energy source of the future, based on its potential contribution to decarbonisation goals.
But there is still a long way to go before hydrogen can be considered a practical alternative to traditional energy sources such as gas.
The conundrum for the world economy between now and 2050 is to reach net-zero emissions while providing enough energy to meet demand from an expanding global population.
This energy transition is at the heart of the United Nations’ Sustainable Development Goals (SDGs), the global agenda launched in 2015 to tackle the world’s toughest environmental and social challenges.
In theory, hydrogen could be used as a fuel for transport and power, as heat for industrial processes and buildings, and as a feedstock for chemicals like fertilisers and industrial products like metals.
In practice, hydrogen’s appeal is difficult to judge.
Hydrogen production needs to be assessed across all sustainability dimensions. Investors and companies are wary of locking into a technology only to find problems later on.
This happened with earlier generations of biofuels and liquified natural gas, all of which were initially promoted as impact solutions.
“It’s a relative game between low-carbon technologies,” says Maxime Le Floch, an analyst with sustainable investing leader Regnan.
Mr Le Floch is a contributor to H2 beyond CO2, a new Regnan research report that examines the environmental impact of hydrogen production for investors.
He is part of a London-based team that manages the Regnan Global Equity Impact Solutions Fund, which aims to generate market-beating, long-term returns by investing in solutions to the world’s environmental and societal problems.
Hydrogen’s potential
“Hydrogen is competing against other technologies for decarbonisation in different parts of the economy,” Le Floch says.
“New hydrogen fuel vehicles have been touted, though with the pace of progress of electric vehicles, hydrogen becomes less likely there. But in other applications like heavy industrial and steel-making, hydrogen might be very interesting.
“We need to keep in mind that these are very long investment cycles, so decisions made today have an impact in 10, 20 or 30 years time. There is a whole carbon cost curve that shows where different solutions stack.”
Growing support for investment in hydrogen technology needs a dose of scepticism — not because the enthusiasm is wrong. It’s just too early to say it’s correct.
“The nature of the investment process within the Regnan Global Equity Impact Solutions team is very comprehensive,” says Regnan’s head of research Alison George, a co-author of the report.
“It’s not just looking at SDGs, but all of the environmental and social impacts. Hydrogen might look attractive, but what are all the implications?”

Key economic, environmental and social issues associated with H2 production. Source: Regnan
George says when researching hydrogen, the economics are discussed constantly, and decarbonisation is talked about some of the time. “But there were gaps in the environmental case.”
“We needed some of these questions answered to determine if it was suitable for the fund. It was really a process of trying to fill some pretty surprising gaps,” she says.
The result was H2 beyond CO2, a report that looks beyond carbon emissions analysis alone.
The report can be downloaded here.
“The entire approach of the fund is to find solutions to the grand problems of sustainability and that approach informs investment decisions. There’s a preference for solutions with the greatest contribution to make, and the clearest pathway to making a difference,” George says.
Key hydrogen production technologies
The report concludes that climate change benefits can be achieved through both green hydrogen and blue hydrogen, but with some important caveats.
For green hydrogen, which is made with electricity, the energy source drives the climate outcomes and the majority of other environmental impacts.
An answer, potentially, is to couple electrolysers with intermittent renewables like wind and solar to help manage output peaks and avoid generator curtailment.
That would support growth in renewables and improve the economics of hydrogen production as well as maximising the contribution to climate goals.
“Few of us have been asking the right questions… this report gives essential answers on the sustainability of climatetech” – Alex Cameron, Decarb Connect podcast
Blue hydrogen has the potential to be a sustainable and economic option for hydrogen production — particularly in regions with local natural gas resources, existing pipelines and transport infrastructure.
But it relies on successful carbon capture and reliable carbon storage. They must be maintained for longer periods to be climate effective.
The Regnan report shows there is much more work to be done in the field of hydrogen.
“Some solutions look great on paper but when you scrutinise the environmental impacts things start to get more nuanced,” Le Floch says. “There’s a great need for more research.”
Case study: hydrogen production with offshore wind
Almost 200 years ago, physicist Hans Christian Orsted discovered electromagnetism, and changed the course of history.
Orsted laid the foundation for the modern generation of electricity, and his name is now synonymous with energy in the Scandinavian countries. Orsted, the company, is the biggest offshore wind developer in the world.
Orsted is one of the few global companies able to generate huge amounts of energy through its offshore wind projects across Europe and in Taiwan. It is a critical piece of the renewable energy puzzle, and not just in terms of wind.
“If you want to decarbonise hydrogen production then you need large sources of energy,” says Regnan’s Maxime Le Floch.
“You can take electricity from the grid but that does not always work. So this is why developing hydrogen production with offshore wind makes sense and projects are being announced.
“Offshore wind projects are on a big scale – and scale is a challenge for other sources of renewable energy like onshore wind and solar,” Le Floch says.
“We are talking about gigawatt scale projects in the North Sea, for instance.”
It demonstrates the necessary links between different energy sources, if renewable power is to reach its potential. It also highlights that companies that could benefit from greater use of hydrogen don’t necessary sit in that sector.
“Orsted is getting involved in exploratory projects around hydrogen and much of the work is to demonstrate that the technology can work,” Le Floch says.
About the authors
Alison George is Regnan’s head of research. She has deep experience in ESG, responsible investment and active ownership. Alison oversees Regnan’s research frameworks, processes and outputs, ensuring it remains at the forefront of industry practice and meets evolving clients needs.
Oshadee Siyaguna is a senior ESG analyst with Regnan, responsible for research and engagement and the generation of analysis and insights on ESG themes and issues. Oshadee joined Regnan as an ESG analyst in 2015. Prior to that he was Assistant Vice President at PolitEcon Research.
Abby Frank is an ESG analyst with Regnan, responsible for research and engagement and the generation of analysis and insights on ESG themes and issues. Abby joined Regnan in 2018.
Maxime Le Floch is an investment analyst with Regnan’s Global Equity Impact Solutions team. He has a decade of experience in sustainable investment. Maxime previously worked as an investment analyst at Hermes where he helped manage Hermes Impact Opportunities Equity Fund and led the integration of ESG and stewardship across investment strategies.
About Regnan
Regnan is a responsible investment leader with a long and proud history of providing insight and advice to investors with an interest in long-term, broad-based or values-aligned performance.
Building on that expertise, in 2019 Regnan expanded into responsible investment funds management, backed by the considerable resources of Pendal Group.
Regnan Global Equity Impact Solutions Fund invests in mission-driven companies we believe are well placed to solve the world’s biggest problems, while the Regnan Credit Impact Trust (available in Australia only) invests in cash, fixed and floating rate securities where the proceeds create positive environmental and social change.
Both funds are distributed by Pendal in Australia.
Find out about Regnan Global Equity Impact Solutions Fund
Find out about Regnan Credit Impact Trust
For more information on these and other responsible investing strategies, contact Head of Regnan and Responsible Investment Distribution Jeremy Dean at jeremy.dean@regnan.com.
Here’s what’s driving Australian equities this week according to Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
- Crispin Murray names the big policy shifts driving equities
- Find out about Pendal’s Focus Australian Share Fund here
MARKETS remain supported by strong economic data. The S&P 500 gained 2.76% last week, while the S&P/ASX 300 was up 2.52%. Market breadth remains high.
It was interesting to see mega cap growth in the US stage a comeback of sorts.
We are mindful that a stabilisation in bond yields could lead to a valuation re-rating of the defensive/healthcare sectors. The consensus trade of rotation from defensives into cyclicals that benefit from the reopening feels like it has run its course to some degree.
Covid-19 and vaccines outlook
It’s generally more of the same in regard to new cases and vaccines.
We are keeping a close eye on an increase in new US cases, particularly given our exposure across materials, housing and gaming there.
Concerns over the impact of a new wave of cases on lockdowns and restrictions appear to have stabilised. Sentiment has been helped by the vaccination program (now running at 3 million new doses daily) and record highs printed in economic indicators. Hospitalisation rates remain under control.
New daily cases in France and Germany continue to improve. But their vaccination programs continue to run well below that of the UK and US. Almost half the UK population has now received one dose. In the US it’s 35% and in Germany 15%.
France brought in additional restrictions last week, but our position in Atlas Arteria (ALX, +1.85%) rose nevertheless.
Economics and data
The March US ISM Services index came in at 63.7, up from 55.3 in February. This is a record high and reflects the impact from stimulus payments. It is yet another indication that the US economy is running hot.
The Fed continues to jawbone the market, attempting to convince all that they won’t change tack and raise rates in response to near-term inflationary pressure.
At this point the market is giving it the benefit of the doubt. As a result US bonds remained stable — 10-year Treasury yields fell 1bp. The Australian equivalent fell 8bps to 1.76%.
The RBA provided commentary on housing. We remain mindful of the risk of macro-prudential measures, particularly for the bank sector. These do not appear imminent given current data on investor participation and affordability.
Markets
The US dollar index (DXY) weakened slightly last week while most commodities were up. Iron ore rose 3.7%, copper 1.2% and gold 1%.
Brent crude fell 2.9% despite oil inventories reaching six week lows, following OPEC’s decision to gently increase supply. It is up 21.5% for the calendar year-to-date.
Our key consideration at the moment is the changing shape of the rotation thematic within the equity market.
In most markets that have had a reasonable run in the last 12 months, the constituents of the “momentum” and “value” buckets have changed quite materially over the last quarter.
Generally the (non-materials) cyclical stocks that used to be the considered “value” have now become the momentum stocks. There is a developing argument that some of the high-flying growth stocks that have underperformed in recent months are now looking relatively attractive.
This could be yet another material shift in the market drivers. There is a high degree of uncertainty which emphasises the importance of having a balanced, non-binary approach to portfolio construction in this environment.
A combination of stabilisation in treasuries and a moderating rotation in the market was generally supportive for equity indices in aggregate.
Only eight stocks in the ASX100 fell last week. AMP (AMP, -4.9%) fell furthest as the company announced the CEO’s departure following weeks of speculation. Disappointment in the effort to realise value via asset sales seems to be a key factor.
Chemical and explosives company Incitec Pivot (IPL, -3.8%) fell after management announced its Wagaman ammonia plant in the US would be offline for longer than expected. Earnings downgrades were in the order of 10%.
Afterpay (APT, +15.1%) was the best performer in the ASX 100, consistent with the better performance from large-cap tech growth stocks in the US. This reflects our view that the recent thematic rotation may have run its course for now.
Our preferred exposure to tech growth, Xero (XRO), gained 6.1%. Other growth stocks such as Seek (SEK, +8.8%), REA Group (REA, +8.7%), and Carsales.com (CAR, +6.9%) caught a bid.
Gold miners Northern Star (NST, +11.2%), Evolution (EVN, +9.1%) and Newcrest (NCM, +6.6%) benefited from a shift back into more defensive areas.
Cleanaway (CWY, +12.3%) made a bid for the Australian-based assets of global waste management group Suez. Suez is subject to a hostile takeover bid on the Paris bourse, which complicates the deal. Nevertheless the market responded well to potential domestic industry consolidation.
It is worth noting the scale of mergers and acquisitions activity in the market. Globally, M&A activity is running at about US$900 billion in 2021.
This is already higher than the total for any year in the past two decades. We suspect there is plenty more to come in 2021 as confidence in the recovery grows.
About Crispin Murray and Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia.
Crispin’s Pendal Focus Australian Share Fund has beaten the benchmark in 12 years of its 16-year history (after fees), across a range of market conditions , as this graph shows:
Source: Pendal. Performance is after fees and before taxes. *From 01 Apr 05; **as at 28 Feb 21. Past performance is not a reliable indicator of future performance.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about Pendal Focus Australian Share Fund here.
Here’s what’s driving Australian equities this week according to Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
- Crispin Murray names the big policy shifts driving equities
- Find out about Pendal’s Focus Australian Share Fund here
EQUITY MARKETS shrugged off concerns over rising Covid cases in the US and in Europe to deliver further gains last week.
The theme of stronger growth — underpinned by yet more encouraging data from the US — seems to be winning.
While there was disruption in the wake of failed hedge fund Archegos, it was felt mainly at a stock-specific level rather than as a broader market event.
The S&P/ASX 300 delivered a 0.63% gain last week, while in the US the S&P 500 was up 2.8%.
Covid and vaccine outlook
There are some localised surges in new Covid cases in the US. Michigan provides a case in point. The 7-day rolling average of new daily cases there has almost returned to the peaks of Q4 2020 as the UK strain spreads. Nevertheless, a national bounce in cases remains relatively muted.
Europe is still struggling to contain a rebound in cases, though there are early signs the surge may not be as bad as previous waves. The impact on sentiment is ameliorated by stronger economic data.
There is a pick-up in the US hospitalisation rate. But at this point the consensus is this will be a mild wave which will not require significant new restrictions. This risk does need to watched, however, given the market’s current appetite for re-opening stocks.
Vaccinations in Europe have begun to step up and are on course for 50% penetration by July.
US vaccinations continue to break new records and are now running at 2.7 million shots a day. Vaccine production capacity is set to rise 50% in April, allowing further acceleration. Almost 40% of the population has been vaccinated.
Economic data remains strong
Economic data continues to demonstrate the strength of the US economic rebound. March payroll data showed 916,000 new jobs versus a consensus expectation of 660,000. Payroll data for the previous two months was also revised up 156,000.
Total US employment, having stalled in recent months, is now accelerating again. The pace of recovery is in stark contrast to post-GFC. It took five years for employment to regain pre-GFC levels. At the current rate, that mark would be reached in 2022. This underpins our view that current policy settings are partly a response to the perceived economic and social failures of the response to the GFC.
There remains a large gap with pre-Covid employment — about 11 million jobs. This helps hold wage inflation in check for the short-term at least.
But if the recovery continues at its current pace it is hard to see the Fed holding to their stated position of no interest rate increases until 2023.
Consumer spending is strengthening in the wake of stimulus payments. In the April 2020 stimulus round, recipients spent about 65% more at the peak than those who did not receive a cheque. In January 2020, the peak rate was only about 30% more. This package looks more like the first one — peaking in the week following cheques at around 58% more. Consumer confidence indicators are also breaking higher.
The US Purchasing Managers Index (PMI), a gauge of sentiment in manufacturing and services, remains elevated at around 65 (on a scale of 1 to 100). The record is 70, achieved in the mid-1980s. Business confidence in Europe is also rising according to surveys, despite a surge in new cases.
More detail emerges on US policy
The Biden administration revealed more detail on the proposed infrastructure package, “The American Jobs Plan.”
It proposes US$2.2 trillion spending, largely in line with consensus expectations. Traditional “hard” infrastructure would account for US$1.7 trillion. The remaining US$500 billion would be allocated to social support policies to address issues such as inequality.
The near-term impact is likely to be less muted than the headline figures suggest, given the spending is extended over a number of years.
Debate over how it is funded — given the need for higher taxes — will be a key area of focus in the near term.
Market outlook
There was some concern that banks selling down positions to help cover the impact of failed hedge fund Archegos would trigger a broad market impact in the vein of Long Term Capital Management (LCTM) in the late 1990s. Total losses from Archegos look to be US$6-8 billion and have hit a number of banks very hard.
Some second-order effects may emerge. At this point associated sell-downs have been seen in specific stocks, but have not destabilised the broader market. The off-setting effects of abundant liquidity and confidence in recovery are holding sway.
Market breadth remains a supportive factor for equity markets. Some 94% of stocks in the S&P 500 are above their 200-day moving average. This is more than at any point since May 2013.
This doesn’t mean we can’t see a correction or consolidation – but it makes it less likely that we are at a market top. A typical sign of extended market tends to be narrower and narrower markets in terms of drivers – and we are clearly not at that point.
Inflation remains the key risk that can de-rail markets.
There are signs of inflationary pressure in specific areas in supply chains. The issue is how quickly – and to what degree – this flows through to wages. The link to wage inflation has not been present for the past 20 years – and we are a long way from employment capacity. Nevertheless, this remains an important factor to watch.
Bond yields edged upwards in the US. The 10-year Treasury yield rose 4bps to 1.67% on the back of stronger economic data. The Australian equivalent rose 16bps to 1.84%.
The US dollar rose another 0.4% as measured by the DXY against a basket of currencies. It is now up 3.3% over the year-to-date, helped by the strength of recovery relative to places such as Europe.
This has weighed on commodities in recent months, although iron ore gained 3.9% last week. Brent crude also rose — up 4.7%, helped by signals that OPEC would continue to be restrained in supply in response to increased demand.
Australian equities recap
Cyclicals such as Materials (+2.7%) and Industrials (+1.6%) tended to outperform on the ASX last week. Confidence in re-opening persisted despite a snap lockdown in Brisbane.
Construction-related stocks continued to perform well on strong housing demand. BlueScope Steel (BSL, +7.4%), Boral (BLD, +7.1%) and James Hardie (JHX, +6.4%) were among the best performers in the ASX 100.
Miners also caught a bid. Mineral Resources (MIN, +6.9%), which has exposure to both iron ore and lithium, was the best of them in the ASX 10, followed by Alumina (AWC, +5.0%), South32 (S32, +4.8%) and Fortescue (FMG, +4.3%).
AGL (AGL, -6.3%) was among the worst performers. It seems the more the market worked through the detail of the proposed demerger, the more it highlighted the limited value in the stock at current levels.
Tabcorp (TAH, -3.5%) gave back some recent gains as it announced a review of its business, potentially delaying a break-up off the company and possible sale of the wagering business. At this point we still expect a demerger of the lotteries and wagering business to be the most likely outcome.
About Crispin Murray and Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia.
Crispin’s Pendal Focus Australian Share Fund has beaten the benchmark in 12 years of its 16-year history (after fees), across a range of market conditions , as this graph shows:
Source: Pendal. Performance is after fees and before taxes. *From 01 Apr 05; **as at 28 Feb 21. Past performance is not a reliable indicator of future performance.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about Pendal Focus Australian Share Fund here.
Bonds look like great value after a sell-off that appears to have run its course, argues Pendal’s Head of Bond, Income and Defensive Strategies Vimal Gor (pictured)
- Bond sell-off a ‘credibility test’ for central banks
- Reversal of decades of falling inflation unlikely
- Bonds look good value
- Find out about Pendal’s fixed interest strategies
RECENT instability in bond markets is shaping into a credibility test for central banks, but Pendal’s Vimal Gor cautions investors against expecting a reversal of the deflationary environment of the past few decades.
A sharp sell-off in bond markets in recent weeks has sent the yield on US 10-year treasuries above 1.7 per cent from scarcely over 1 per cent a few weeks ago.
Gor, who leads Pendal’s Bond, Income and Defensive Strategies team, says the sell-off indicates a divergence between the views of the markets and central banks.
“What it’s telling you is the market is questioning central banks’ credibility,” he says, speaking at last week’s Conexus Fixed Income and Private Credit Forum Digital event.
“They’re questioning both their forward guidance and their willingness to stick to quantitative easing packages.”
Reflation not inflation
Still, Gor cautions against expecting a reversal of the deflationary environment of the past few decades because the demographic and technological drivers of lower prices have not changed.
“I think it’s more reflation than inflation,” he says.
“We know inflation is going to be higher over in the next few months” because it will be compared to the lower prices seen during the heights of the COVID pandemic. “But it’s a very big ask to expect the deflation environment to have come to an end.
“So yes, there is a short run pickup in inflation, which is pressuring bond yields higher, but I question whether that narrative is going to run much further.
“If anything, bonds look great value to us now.
“I think that the sell-off in bonds has largely run its course.”
QE risks for markets
Gor raises questions over the long-term risks of quantitative easing (QE) for markets, saying that central banks determination to hold bond yields down is artificially lifting the price of every other asset.
“Historically, the way yield curves worked is the central bank sets the short-term interest rate, which has an effect on the very short end part of the curve and has less effect as you go up the curve as that’s driven by supply and demand.
“So the front end is locked, the back end moves around.
“Now the central bankers are telling you they want to control the entire yield curve.
“Effectively, they’re telling you that the central bank knows better than the private sector where the price of credit and interest rates should be.
This limits the returns available in government bonds and forces investors to seek a return elsewhere.
“If you hold bond yields down artificially… it has impact on every other asset. Everything from private equity to venture capital to SPACS [special purpose acquisition companies] to real estate – every asset in the world is largely a derivative of a central bank.”
Cryptocurrency role in portfolios
The risk inherent in QE means investors should consider seeking out defensive alternatives to bonds as they construct portfolios, with cryptocurrencies like bitcoin a potential supplement to bonds.
“If I was to say to you ‘sell all your government bonds and buy crypto’ well that’s a ridiculous statement and I’d never say it.
“But instead of owning 100 per cent of your defensive assets in government bonds … how about you think about utilising other strategies and at times utilise crypto because they do have positive characteristics that you find it very few other assets.
“So were you to utilise them at the right time, they would add significantly to your defensive portfolio. That’s how we approach it.”
About Vimal Gor and Pendal’s Bond, Income and Defensive Strategies (BIDS) boutique
Led by Vimal Gor, Pendal’s BIDS boutique is one of the most experienced and well-regarded fixed income teams in Australia. In 2020 the team won the Australian Fixed Interest category in the Zenith awards.
With the goal of building the most defensive line of funds in Australia, Vimal oversees A$22 billion invested across income, composite, pure alpha, global and Australian government strategies.
Vimal sets the strategy, processes and risk management for the boutique and all funds managed within it.
Find out more about Pendal’s fixed interest strategies here
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Contact a Pendal key account manager here
Here’s what’s driving Australian equities this week according to Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
- Crispin Murray names the big policy shifts driving equities
- Find out about Pendal’s Focus Australian Share Fund here
RECENT trends persisted last week.
On the negative side new daily Covid cases rose in the US as mobility increased with the warmer weather. European numbers also continued to surge higher.
Bond yields were more stable, although there was more selling on Friday.
This is balanced with optimism around the stimulus and pent-up demand as vaccine penetration improves in the US and UK. There are also signs of the wealth effect supporting spending on housing market strength.
The bearish argument is that economic momentum peaks in the next month with strong growth already priced in and the emerging risk of another Covid wave affecting demand.
The bull case is that the market cycle continues, supported by a strong economy, even as the momentum of growth slows. This is supported by the notion that we are in the early phase of the recovery, with corporate earnings picking up and no sign of tightening.
We are in the latter camp at this point, though our portfolio positioning reflects our view that we must be mindful of material risks. We do think market leadership will continue to shift. We are already seeing the more speculative growth names continue to underperform in the US.
The S&P/ASX 300 gained 1.7% last week, while the S&P500 was up 1.6%.
Covid and Vaccines outlook
Localised outbreaks in New York, Michigan and Pennsylvania pushed up total US new daily cases by 8% week-on-week.
In New York an estimated 20% of cases are the E484K mutation (seen in the Brazilian and South African strains) which is less responsive to the vaccination. A further 40% have the B117 (UK strain) variant.
A variant-specific vaccine will be trialled in early summer and may be available by September.
The key risk is that case levels remain elevated due to these strains, which could impact sentiment and activity. This highlights the complexity of re-opening international borders later in the year.
It will be important to track US hospitalisations which tend to follow case numbers with a lag of one to two weeks.
Pressure on the medical system has eased and is not an issue now, given the penetration of vaccinations in the over-65 age cohort.
Vaccination rates in the US should ramp up with increased supply, allowing jabs for 3-4 million people daily. It’s expected that two-thirds of the US population will be vaccinated by the end of April.
Europe’s vaccination rate is now running two months behind the UK. Daily vaccination rates are trending down in France and Germany and rising cases are leading to further lockdowns. This is affecting markets, weighing on the price of oil. Continued issues in Europe could also help support the US dollar and bond market.
Economy and policy outlook
April could be the strongest month for US economic growth that we see in our working lives.
The effective stimulus distributed in March is the equivalent of payments in April 2021. There are signals of strong pent-up demand while the surge in equities and house prices is contributing to the wealth effect.
All this is very supportive of likely consumer spending, underpinning corporate earnings. Data is likely to be strong, perhaps bringing more pressure to bear on bonds.
As this initial surge passes, the question is whether it will signal a temporary high in bond yields. If so, we are likely to see some rotation back to yield-sensitives in the equity market. This is an important question in terms of portfolio construction.
There was debate over the US infrastructure Bill last week with a desire to put more longer-dated stimulus in train to help offset the drag as the current packages expire next year. At this point there is talk of US$3-4 trillion spread over ten years. This may be put to Congress in two packages.
One package could focus on mainly physical infrastructure, which would likely attract bipartisan support. The other, more progressive package could focus on other equality-focused measures and be passed via the budget reconciliation process.
We are also keeping an eye on the debate over tax, which has implications for earnings and specific sectors. The Biden tax proposals equate to about US$2 trillion, including an increase in the corporate tax rate to 28%.
If fully implemented these measure would be a 6% hit to S&P500 earnings.
There are also initiatives to change taxation for companies earning offshore, which may surprise the market. Pharma companies are likely to come in for specific proposals.
Higher taxes are coming but the current package is likely to be watered down. The corporate rate may be lifted to 24-25% with end impact closer to 3-4% of corporate earnings.
Debate over the filibuster is shaping up as a major issue in the US.
If materially watered down this will open the door for far more Democrat policy agenda — leading to greater spending on environmental issues and higher regulation. This could lead to higher US bond yields and a weaker USD.
Markets outlook
US 10-year government bond yields stabilised last week, though they rose on Friday after chatter about further stimulus measures. The USD continues to grind higher, encouraging some rotation to more defensive names.
Currency strength and stable yields are potentially driven by the carry now available in US bonds for foreign investors, given the low cost of capital.
We see a battle emerging between this liquidity support versus the reality of growth and rising inflationary pressure.
The virtuous circle of liquidity that helped support speculative tech names in the US may be unwinding. It looks as though not as much of the stimulus is being invested in the market.
People are also getting outside, meaning there’s less time to day trade.
The proxy here is the ARK Innovation ETF — and by association Tesla — which are down 27% and 30% respectively from their highs. ARK in particular could be hit hard if outflows accelerate.
Australian equity strength was broad based last week. We saw more high-quality defensives join the rally, having lagged year to date.
TPG Telecom (TPG, -7.4%) was the weakest stock in the ASX100 after news that founder David Teoh was stepping down as Chair. The reason was not disclosed. He retains a 17% stake in TPG, with 80% of this held in escrow until the end of June 2022.
Teoh is regarded as the architect of TPG’s historically aggressive approach on pricing. So the news was seen as a positive for Telstra (TLS, +6.3%), which was one of the market’s strongest performers. TLS also outlined a new corporate structure which will enable it to partially or fully divest infrastructure assets such as its mobile towers. This could potentially free up capital for share buy-backs.
Crown Resorts (CWN, +19.6%) received a takeover approach from private equity firm Blackstone and was the best performer in the ASX 100.
Blackstone’s offer is highly conditional and opportunistic in nature. The bid is only in line with the stock’s pre-Covid level. Blackstone is taking advantage of a discount related to the regulatory reviews — but it is conditional on the resolution of those issues.
The market’s view is that this is designed to flush out a joint venture partner that could buy in combination with Blackstone at a higher price. While the bid highlights the under-valued nature of CWN’s attractive assets — which forms part of our investment thesis — there is still a fair bit of water to flow under this bridge before a deal is finalised.
Small cap tech company Pushpay (PPH, +8.7%) — in which we also invest — rose as one of the early venture capital backers sold a block of stock equivalent to 15% of the float to US tech fund manager Sixth Street Advisors. This removed a significant overhang and brings in an investor with a strong track record in backing the likes of Air BNB and Spotify.
Xero (XRO, +6.1%) made a small bolt-on acquisition ($25 million) of Swedish e-invoicing company Tickstar. This is a sensible move in line with the company’s growth strategy in our view.
Among other stocks we invest in, Metcash (MTS, +6.6%) was one of the quality defensives to catch some interest last week.
James Hardie (JHX) rose 5.7% as bond yields stabilised. Anecdotes from US homebuilders remain supportive, suggesting sales could double current levels if supply was available. At this point the prospect of higher mortgage rates is not having a negative impact on demand. Builders are also signalling an opportunity to raise prices further.
About Crispin Murray and Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia.
Crispin’s Pendal Focus Australian Share Fund has beaten the benchmark in 12 years of its 16-year history (after fees), across a range of market conditions , as this graph shows:
Source: Pendal. Performance is after fees and before taxes. *From 01 Apr 05; **as at 28 Feb 21. Past performance is not a reliable indicator of future performance.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about Pendal Focus Australian Share Fund here.
Brazil may be attracting negative headlines, but 2021 looks set to be a period where the cyclical opportunity is strong.
Here James Syme and Paul Wimborne (pictured) — managers of Pendal’s Global Emerging Markets Opportunities strategy — explain why.
-
- Brazil shows a move away from liberalising economic reforms towards a more populist stance ahead of 2022 elections
- But by our reckoning the country’s fundamentals look very good indeed
- Find out more about Pendal Global Emerging Markets Opportunities Fund
THE BOLSONARO government in Brazil has taken decisive action after weeks of increasing tension with parts of the corporate sector.
Most coverage has focused on a decision to replace the CEO of oil company Petrobras (held in the Pendal Global Emerging Markets Opportunities portfolio) after the company decided to increase petrol and diesel prices in line with crude oil prices in the face of government criticism.
President Jair Bolsonaro instead suggested the company should cut fuel prices by 10 per cent.
This management change was poorly received by investors because it reduces headline profitability and calls into question the outgoing CEO’s shareholder-friendly operational and financial strategies.
This trend is not Petrobras-specific though. President Bolsonaro is also pushing utility companies to reduce electricity prices.
In addition, one of the major Brazilian banks, Banco do Brasil, has been under serious pressure to abandon its plans to rationalise its workforce.
Taken in the whole, this shows a clear move by the administration away from liberalising economic reforms, towards a more populist stance ahead of the 2022 elections.
What it means for investors
This has a number of implications for investors.
Coming at a time of rising US bond yields, the effect on the share prices of the companies concerned has been significantly negative. But at a wider level the stock market, local currency bonds and the currency have sold off and Brazilian Credit Default Swaps have increased.
This is partly because of the potential implications for fiscal and monetary policy.
As the Brazilian economy normalises post-Covid, the question as to how to (or even, whether to) end the worsening drift in the trajectory of public debt becomes more urgent.
There is a substantial domestic lobby arguing for prioritising economic support and it’s now more likely President Bolsonaro will move in this direction.
The key question for fixed income investors is the future of the fiscal spending cap.
The cap (given constitutional status in 2016) limits nominal growth in the primary (ex-debt interest costs) deficit to the rate of inflation. This would, over time, reduce the deficit as a proportion of GDP, and its existence anchors Brazil’s fiscal policy and contains bond yields.
In 2020, with serious pressure on government finances, the government was able to avoid the cap by using a parallel “emergency budget” for stimulus.
As that justification passes, pressure to return to a fiscal stance that complies with the cap will conflict with popular (and hence political) pressure to remain fiscally loose.
Impact of 2022 election
As we head into an election campaign (a Brazilian general election is due in October 2022) markets may assume the spending cap will be abandoned.
As fiscally loose, so monetarily tight.
The Brazil Central bank met in mid-March and lifted rates in response to a weaker currency and higher bond yields.
The old adage that elections are good for markets in emerging Asia but bad in Latin America may yet apply.
And yet, it is important not to be too bearish. Policy has to be viewed through the lens of fundamentals and, by our reckoning, fundamentals look very, very good indeed.
Barring a prolonged inflationary spike (end of December unemployment was 14.2%, pretty much the highest it has been in 20 years while capacity utilisation recovered to 80.5% in January, well below the 83-84% levels seen at cyclical peaks) Brazil’s enduring weakness is its balance of payments. This is in turn largely a reflection of trade-related and portfolio flows.
Right now both of those look great.
Brazil’s terms of trade (the ratio of export prices to import prices) are by far the best they have been in 25 years, far above the mid-90s or late-00s peaks.
A year ago soybean spot prices were BRL 40/bushel — they’re now BRL 84. Iron ore has moved from BRL 380/t to BRL 900/t. Sugar has gone from BRL 0.67/lb to BRL 0.92/lb.
This feeds right through to the trade balance.
Through 2015 and 2016 the Brazilian trade balance moved substantially into surplus with exports rising and import compression.
Last year 2020 there was volatility in trade flows as Covid-19 hit domestic and external demand and the past few months have seen economic recovery lift imports.
But there is a close historical relationship between terms of trade and exports, and this points to a substantial lift in exports as we move through 2021.
Meanwhile the non-goods component of the current account has compressed to a deficit of 1.4% of GDP compared with deficits of around 4% at cyclical peaks.
Portfolio flows
Portfolio flows are another driver of the Brazilian economy and Brazilian financial markets.
In mid-2020 we saw large capital outflows from riskier emerging markets, particularly Brazil.
Foreign holdings of Brazilian government debt fell from $US140 billion at the start of 2020 to $US101 billion in April.
But by the end of 2020 we saw strong capital inflows with a better cyclical outlook and a weaker
dollar.
International portfolio flows into Brazilian government debt were $US16 billion in Q4 2020, with half of that coming in December.
Anecdotal information suggests a continuation of that in January and February and a similar pattern in the Brazilian equity market (where trading volumes have shot up in the past year).
Foreign direct investment (FDI) is perhaps the laggard.
Net FDI into Brazil was down 50% in 2020 compared with the previous year. The main trend there is a reduction of large investment flows into sectors such as autos and steel and a pick-up in much smaller flows into sectors like fintech and education.
Political outlook
History suggests a sustained recovery will attract inflows — but the negative impact of President Bolsonaro’s actions must be noted.
Concerns around politics and policy have caused us to be cautious about adding exposure to Brazil. We will continue looking to add opportunistically while the macro environment remains so supportive.
It remains our view that Brazil is a market best seen as offering cyclical opportunities rather than a long-term buy-and-hold case.
There will be periods where the cyclical opportunity is strong — and we believe 2021 is likely to be one of them.
The move higher in bond yields, reflecting a stronger global economy, is causing a drag on Brazilian financial markets in the short-term.
But that doesn’t remove the strong fundamental case for the medium-term.
About Pendal Global Emerging Markets Opportunities Fund
James Syme and Paul Wimborne are senior portfolio managers and co-managers of Pendal’s Global Emerging Markets Opportunities Fund.
The fund aims to add value through a combination of country allocation and individual stock selection.
The country allocation process is based on analysis of a country’s economic growth, monetary policy, market liquidity, currency, governance/politics and equity market valuation.
The stock selection process focuses on buying quality growth stocks at attractive valuations.
Find out more about Pendal Global Emerging Markets Opportunities Fund here.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
One year after the market low, here’s how head of equities Crispin Murray (pictured) drove outperformance for Pendal Focus Australian Share Fund during the pandemic. Chris Adams reports.
THIS week marks one year since the market’s low point during the pandemic.
Since the pre-Covid peak on February 21, 2020, Pendal Focus Australian Share Fund has returned 2.9% after fees (to Mar 19, 2021).
The benchmark ASX 300 lost 2.2% over the same time according to Morningstar.
A key factor in the fund’s 5.11% outperformance against the benchmark has been its ability to perform through each phase of the market last year. This is driven by our approach to portfolio construction.
Pendal Focus Australian Share Fund does not rely on a certain set of macro variables to be in place to perform. This has enabled the fund to deliver outperformance while other more thematic approaches have not performed as well.
A market of rapid rotations
The world has run out of clichés to describe the past 12 months.
We had the impact of lockdown policies, supply chain disruption, fiscal stimulus, monetary policy, China-Australia trade tension, the shift of consumers to online, increased focus on ESG and US Presidential elections.
It’s fair to say we have never seen such a material change to so many structural factors in such a short space of time.
Swift changes in key macro factors prompted often-sudden rotations in market leadership.
Defensives did well in the initial market slump. Though the nature of the crisis meant some sectors previously considered defensive – such as A-REITS – were anything but.
The policy response of slashed interest rates helped growth companies renew their pre-Covid surge.
In November, news of successful vaccines drove a swift rotation to cyclicals and value.
Meanwhile entire industries and business models were structurally disrupted in a matter of weeks. Other companies encountered a once-in-a-generation opportunity.
As a result it’s been an incredibly challenging period for investors.
It has also been a period in which the Pendal Focus Fund showed its mettle.
How our portfolio construction drove outperformance
Relying on one “style” of investing can lead to prolonged periods of underperfomance — as value investors have seen for many years.
Trying to “time” swings in style involves anticipating changes in macro variables and investor sentiment — something that’s incredibly hard to get consistently right.
We address this issue by building portfolios based on company insight. We want a portfolio that can perform regardless of the environment, driven by stock selection.

Our aim is a portfolio that is not hostage to one style or a theme playing out in a certain way. In environments of heightened uncertainty, we want to avoid heroic calls on binary outcomes.
Under our approach we created different segments in the portfolio that worked together, allowing it to perform in different scenarios. Key segments last year included defensives, growth stocks, policy beneficiaries, quality franchises and recovery plays.
The key is to find companies with attractive fundamental features that can help limit the downside if the macro factors are not supportive, while delivering the potential for large upside gains in the right environment.
This requires an understanding of companies and industries drawn from access to management that comes with our 18-strong, highly experienced Australian equity team.
2020 provides a strong case study of why we do it this way:
- We were able to move quickly to identify and avoid companies facing existential threats.
- We were able to take opportunities in companies where we anticipated a better outcome than share prices implied – such as Nine Entertainment and Qantas.
- Pendal Focus Australian Share Fund’s outperformance in periods of negative sentiment was driven by defensive holdings such as Metcash (MTS) and by the portfolio insurance provided by gold miners such as Evolution (EVN).
- Falling bond yields helped our growth exposure via Xero (XRO) – which has then held up well due to company-specific fundamentals as other growth stocks sold off.
- Recent outperformance has been driven by recovery-linked exposures such as Qantas (QAN), Santos (STO) and Westpac (WBC).
- Throughout the period there has been a strong tailwind from policy beneficiaries such as Fortescue Mining (FMG) and JB Hi-Fi (JBH).
- We have also done well as the market recognised the value offered in long-term winners such as Aristocrat (ALL), James Hardie (JHX) and Nine Entertainment (NEC).
The outcome is a portfolio that has outperformed through each phase of the market in 2020.
Outlook
The world is now in a better place than many expected a year ago.
The economic rebound has been strong, helped by a surge in monetary and fiscal policy support. Vaccines are arriving. The world is getting better at living with the virus and mitigating its economic damage.
Nevertheless, risks remain.
The risk of premature policy-tightening cannot be ruled out. Vaccinations are working, but efficacy against new strains must be monitored. Geopolitical risk – particularly around the relationship between China and Australia – is higher than usual.
There has been a rotation from growth to value and cyclicals, but the reality is far more complex than broad style labels.
Within value there are plenty of companies that are structurally challenged and are cheap for very good reason.
Growth stocks may have lost the tailwind of falling real rates, but plenty of growth companies remain attractive long-term investments. It’s interesting to note the market seems to be starting to differentiate between profitable growth companies with cash flow and more speculative, long-duration stocks.
Given heightened macro risk, we believe a strategy that is not reliant on a certain macro outcome offers the best chance for consistent performance.
If value, recovery-related stocks continue to outperform, that part of our portfolio will benefit.
If inflation starts to creep up we have exposures with pricing power that will do well.
If we see a hit to sentiment – either from tighter policy or a deterioration in Covid – then the defensives should step up.
We continue to have exposure to carefully selected growth stocks, where we see fundamental valuation support on the basis of earnings visibility and realistic expansion opportunities.
The upshot is that we believe our balanced approach remains as valid now as it did a year ago. It has served our investors well in the sell-off and has worked in the rebound.
No-one knows what will come next. But we believe our portfolio construction, underpinned by our company knowledge, should give investors confidence that their portfolio is well positioned regardless of the next phase of the Covid saga.
Here’s an overview of Pendal Focus Australian Share Fund performance at February 28, 2021:

Source: Pendal. *Benchmark: S&P/ASX300. Past performance is not a reliable indicator of future performance
About Crispin Murray and Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia.
Crispin’s Pendal Focus Australian Share Fund has beaten the benchmark in 12 years of its 16-year history (after fees), across a range of market conditions , as this graph shows:
Source: Pendal. Performance is after fees and before taxes. *From 01 Apr 05; **as at 28 Feb 21. Past performance is not a reliable indicator of future performance.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about Pendal Focus Australian Share Fund here.
Here’s what’s driving Australian equities this week according to Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
- Crispin Murray names the big policy shifts driving equities
- Find out about Pendal’s Focus Australian Share Fund here
TWO concerns emerged last week. Both bear close watching.
First was the emergence of another wave of Covid cases in Europe. The pace of vaccination has been too slow and Covid variants have taken hold, driving an increase in new daily cases across the EU. There are some emerging signs that the early removal of restrictions in the US may see growth in new cases in some states.
The second issue is growing scepticism over the Fed’s ability to keep rates low for an extended period, despite its reiterated stance. The risk here is of a sharp bond sell-off which contaminates equities.
At this point global equities continue to hold up well. But we note the oil price fell 7% last week. There is a risk this is the first sign of this year’s winning trades rolling over.
On the positive side, earnings continue to support markets. The US economy is taking off, while the Australian economy is doing better than expected — as evidenced by last week’s employment data. This can help sustain equities through a consolidation phase while the market adjusts to higher bond yields.
The S&P/ASX 300 fell 0.8% last week, while the S&P 500 was off 0.7%.
Covid and Vaccines
Overall new daily cases in the US continue to fall — but there are states such as Michigan and Florida where cases have turned higher. The arrival of Spring and the removal of restrictions is expected to lead to a new wave in cases. The issue is how material this will become given the level of vaccines and high levels of prior infection. Very high vaccination rates among the more vulnerable parts of society may mean far less pressure on hospitals.
Europe is more of a concern and a significant new wave is possible. There are renewed lockdowns in Poland and France. Non-essential businesses in Paris have been closed. Growth in concerns here are likely to have played a part in a weaker oil price over the week.
Economic and policy
The market’s essential paradox is that two-year inflation expectations in the US are nearing 3% — beyond the Fed’s 2% target — but the Fed’s guidance is for continued loose policy. The market is increasingly uncomfortable with this notion.
The Fed meeting this week reinforced this paradox with a message of more of the same. It re-affirmed a dovish perspective, with the majority of the FOMC seeing no rate hikes in CY22 and 23. The rationale is they expect strong near-term growth to fade, easing inflationary pressures. Their expectation is 2% inflation for CY22 and only marginally higher in CY 23.
The Fed appears to be comfortable with bonds finding a new long-term equilibrium and do not want to get in the way of it. The Bank of England also met this week and indicated comfort on rising bond yields.
The risk is that this process is not smooth and the sale of bonds becomes disorderly, given the unprecedented coincidence of strong pent-up demand driven recovery, fiscal stimulus and loose monetary policy.
The disconnection in expectations can be seen in the large spread between the Fed’s guidance and the market expectation of hikes implied in overnight index swaps (OIS). By the time the first rate hike is officially expected in Q4 2023, the market implied expectations are for three 25bp rate hikes — the first coming in early 2023.
This can also be seen within the FOMC itself. Five members are expecting three-to-four rate hikes by end CY23 — ie believing what the market is saying — while 11 see no such increases. The fact that this dichotomy exists even within the Fed suggests the market’s current expectation is plausible.
Economist and former US Treasury Secretary Larry Summers provided an interesting perspective last week. He repeated his observation that the US was plugging a 3-4% gap in GDP with 14% worth of stimulus.
He also noted a contradiction in the narrative that this is a new paradigm for progressive policies which will deal with structural challenges such as inequality and addressing climate change – but that the effects of the fiscal stimulus are transitory and will fade in CY22, meaning inflation is not an issue.
The key to this is how well inflation expectations are anchored. The Fed believes they are well anchored. The risk is that this belief is undermined and they are forced to re-anchor through a policy pivot.
This will be the key debate for the next six months. It could make for some choppy moments and heightened sensitivity to near-term signals. The strength of recovery in the US economy will be the key issue to watch.
We note that the basing out of the US dollar index may help with the management of inflation expectations. There are a lot of sectors correlated with the USD, notably resources. Recent USD strengthening partly explains the sell-off in resources stocks and remains an important factor to follow. We expect the USD can remain supported given challenges facing the EU. This could be a headwind for resources, but could also help check the worst fears on inflation and bonds yields.
On the US fiscal side, the focus is shifting to the tax increase which will come as part of the infrastructure bill. The Bill itself is still expected to be about US$2 trillion, with half towards hard infrastructure and the remainder to healthcare, education and research and development.
Half the funding is intended to be from net tax increases, including 28% corporate tax. There will be a lot of disagreement over tax rates within Congress, which may impede progress. But the headlines are likely to add to market concern.
One potential resolution may see the Bill broken up into a bi-partisan infrastructure Bill and then a second one that is more progressive and partisan incorporating tax increases.
We also got important Australian data last week. Employment data was very strong. The unemployment rate fell to 5.8% — 0.5% below expectations. This supports the view that any set-back from the end of JobKeeper will be limited and short lived, as long as no more lockdowns occur. The employment / population ratio is 62.3%, versus 62.7% pre-Covid.
The unemployment rate remains a little higher due to participation rates actually rising. Nevertheless Australia has effectively recovered all jobs and is well ahead of other countries in this regard.
Retail sales data was more subdued following a very strong run. It is a reminder that it is vulnerable to normalisation as opportunities emerge to direct spending to other areas such as domestic travel. The softness was more in the area of food sales, indicating people may be beginning to eat out of home more.
We also had population growth data for end of September which, unsurprisingly, has slowed dramatically. This will eventually begin to cause issues for economic growth and housing demand. But for now it will perhaps allow the unemployment rate to fall further and quicker than expected. We expect immigration will be high on the government’s agenda – and that the last 12 months have probably increased Australia’s attraction to potential migrants.
Markets
Equities continue to be resilient in the face of the bond sell-off. 10-year government bonds are on track for their worst quarter for returns in 50 years. Despite this equities in US are up 4.5%, helped by strength in corporate earnings.
The Australian market fell last week, mainly due to resources stocks falling in sympathy with commodity prices. There was a rotation to more defensive names. Over the calendar year to date resources are now underperforming. Banks are the clear lead sector, while tech is worst.
We saw some of the more speculative tech names affected, which is understandable given the rise in bond yields.
The market was led by stocks that had lagged more recently. Some of the US dollar-sensitive stocks did well. Retailers also recovered, as did gold miners.
There was some news flow on key positions in the portfolios.
Metcash (MTS, -2.5%) delivered a constructive strategy day. The IGA franchise has won market share as a result of changing shopping habits to more regional and neighbourhood centres. They have now moved back into store expansion, rather than closures, while Aldi’s roll-out has ended. This suggests they can hold share in this space.
Meanwhile hardware offers a decent growth opportunity in a consolidated industry. The stock fell in reaction to increased capex in this space, but we see the plans as sensible and likely to produce a reasonable return.
The company upped its payout ratio from 60% to 70%, which can be funded despite the capex and means the yield is running at 5%.
Gold miner Evolution (EVN, +5.1%) announced a mid-sized debt-funded acquisition of a Canadian gold company which is adjacent to their existing Red Lake mine. This and allows them to bring forward production and reduce capex, so was well received.
About Crispin Murray and Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia.
Crispin’s Pendal Focus Australian Share Fund has beaten the benchmark in 12 years of its 16-year history (after fees), across a range of market conditions , as this graph shows:
Source: Pendal. Performance is after fees and before taxes. *From 01 Apr 05; **as at 28 Feb 21. Past performance is not a reliable indicator of future performance.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about Pendal Focus Australian Share Fund here.