
Investors who want to make a difference in the world have far more potent weapons at their disposal than merely selling their shares.
- Screening strategies not enough to drive change
- Investors need a new approach – hold and vote
- Exxon Mobil defeat a clarion call for shareholder power
THIS YEAR’s stunning defeat of Exxon Mobil by Engine No.1, a tiny activist fund that resulted in three new directors on the board of one of the world’s largest fossil fuel companies, is the most public example of the rise of a new type of shareholder engagement.
It is expected to accelerate a dawning realisation among investors that when it comes to public equity markets, there are stronger avenues for change than traditional methods of screening and divesting companies.
If every climate-minded investor sold their coal shares, that would leave control of those companies in the hands of the least climate-minded owners.
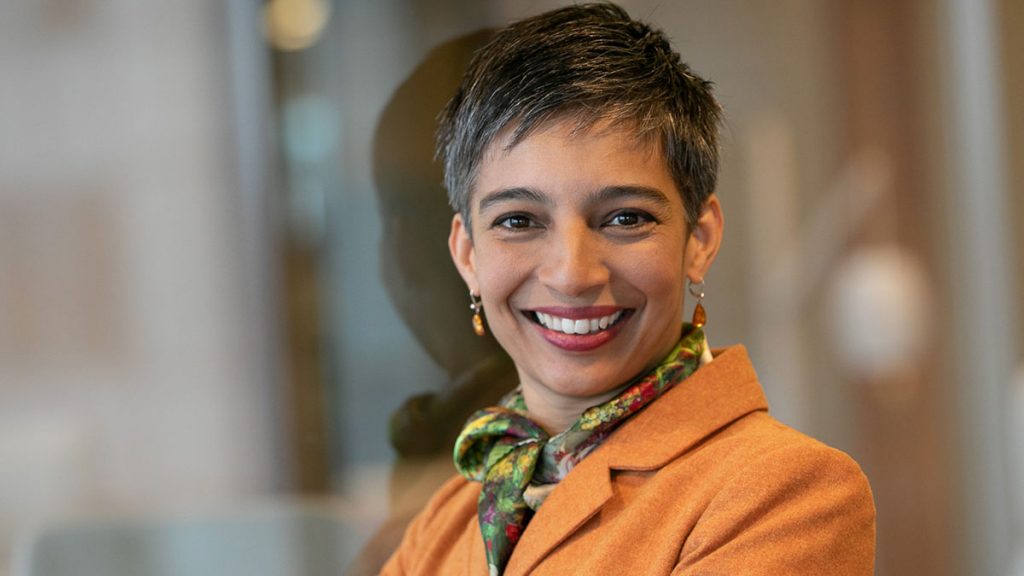
Susheela Peres da Costa
“But while there are good reasons for an investor to not want to be exposed to fossil fuel assets, it’s another thing altogether to assume a company cares who owns its shares.
“It’s worse than having no impact because it makes for a false sense of security.
“Even if every climate-minded investor sold their coal shares, that would leave control of those companies in the hands of the least climate-minded owners.”
Regnan’s work suggests investors who want to make a difference in the world have far more potent weapons at their disposal than merely selling their shares.
Stewardship initiatives, in which institutions use their investor influence for change, are proving to be a powerful lever.
Investor stewardship can also be successful putting resolutions to boards and reigning in unhelpful corporate influence on government policy.
Advocacy is an area where coalitions of smaller investors can have a real effect, directly asking regulators, industry bodies and governments for change.
And investing in disruption to drive change is also an effective strategy.
But what about small investors without access to these avenues?
“Figure out where your power really is,” says Peres da Costa. “Unless you are an enormous institution, big enough to move market prices, you have much more power as a consumer – what products and services you buy, who from, and whether you are vocal about why.
“So, you say ‘I don’t want my shares ever to be voted in favour of a director who is trying to entrench fossil fuels in the economy’. And you check which financial service providers commit to that before you entrust them with your money.

Find out about
Regnan Global Equity Impact Solutions Fund
Peres da Costa points out that this simplifies many of the challenges associated with trying to invest responsibly, by focussing the discussion on what kind of impact investors want to have.
“It’s too easy to get caught up in details when you focus on divestment, or ‘screening’,” Peres da Costa says.
“For instance, should divestment focus on companies that produce fossil fuels? Or firms that burn them, releasing global warming gases into the atmosphere? Are firms that support the fossil fuel supply chain in or out? Coal ports? Gas pipelines? Roadside retailers of petrol?
“Burning fossil fuels is a major part of industries as diverse as energy generation, steelmaking and aviation. Many of the largest organisations involved in fossil fuels are governments; are we divesting airlines and countries too?
“Are all carbon emissions equal? Is coal burnt to make steel for wind turbines worse than lower-carbon oil to air-freight fresh tropical fruit to temperate markets?
“These are often interesting debate topics, but dodge the deeper question most clients are interested in addressing: What does my money do?”
Read more about what investors can do to drive change at The Divestment Dilemma.
About Susheela Peres da Costa
Susheela is Regnan’s head of advisory. She has more than 15 years of domestic and international experience advising institutional investors on responsible investment.
As Head of Advisory, she has assisted small foundations through to the world’s largest institutions, including a successful 18-month project in Switzerland responsible investment leadership for a global full-service bank and strategic advice to the UN-backed Principles for Responsible Investment on upgrading stewardship.
Susheela chairs the Responsible Investment Association of Australasia and is special adviser to the co-chair of the Australian Sustainable Finance Initiative.
About Regnan
Regnan is a responsible investment leader with a long and proud history of providing insight and advice to investors with an interest in long-term, broad-based or values-aligned performance.
Building on that expertise, in 2019 Regnan expanded into responsible investment funds management, backed by the considerable resources of Pendal Group.
Regnan Global Equity Impact Solutions Fund invests in mission-driven companies we believe are well placed to solve the world’s biggest problems, while the Regnan Credit Impact Trust (available in Australia only) invests in cash, fixed and floating rate securities where the proceeds create positive environmental and social change.
Find out about Regnan Global Equity Impact Solutions Fund
Find out about Regnan Credit Impact Trust
For more information on these and other responsible investing strategies, contact Head of Regnan and Responsible Investment Distribution Jeremy Dean at jeremy.dean@regnan.com.
Find out about
Regnan Global Equity Impact Solutions Fund
Pendal’s Sustainable Australian Fixed Interest Fund invests in social bonds that help vulnerable Australians while also aiming to generate strong returns. This is the story of a family helped by Hume Community Housing, which is financed by those social bonds.
Rudy and Judith knew early on that something was different about their twins Steven and Kerry.
When they first took them to the doctor at 12 months of age, they still hadn’t shown any sign of trying to walk or stand up.
“I knew something was wrong,” says Judith.
Steven and Kerry had cerebral palsy: a permanent movement disorder that robs sufferers of the ability to live a normal life. It often requires constant, sometimes lifelong care — usually delivered by loving family members at considerable personal sacrifice.
“Steven and Kerry’s parents have done everything for them for 60 odd years and asked for nothing – asked for no help whatsoever,” says Angela, a direct care worker for the Cerebral Palsy Alliance.

As the years went on, Rudy had to retire early because it was getting too difficult for Judith to take care of Steven and Kerry on her own.
“I was 80 and Rudy was 83 – we knew we had to do something,” says Judith.
Heart-wrenching separation
The idea of being separated from the pair was heartwrenching.
The first time Judith took the twins to respite she admits she “cried her eyes out – it was hard to let go”.
But they knew they had to prepare for the future. It was most important that the twins could be looked after in comfortable accommodation built by someone they could rely on.

Pendal Sustainable Australian Fixed Interest Fund
An Aussie bond fund that aims to outperform its benchmark while targeting environmental and social outcomes via a portion of its holdings.
More than anything Rudy and Judith wanted the twins to be kept together when they could no longer look after them, Angela says.
Angela, who has been a carer for Steven and Kerry for about 15 years, put the family in touch with Hume Community Housing.
Social bonds help vulnerable Australians
Hume is a Tier 1 Community Housing Provider (CHP) which develops affordable housing for vulnerable or low-income Australians with help from investors in Pendal’s Sustainable Australian Fixed Interest Fund.
Hume is well-known for its expertise in developing and managing Specialist Disability Accommodation that caters for extreme functional impairment or very high-support needs.

Hume’s funding comes partly from the federal government’s National Housing Finance and Investment Corporation (NHFIC), which raises money by issuing social bonds to investors such as Pendal.
NHFIC lends out the money raised (more than $2 billion so far) to CHPs at lower interest rates and on better terms than banks — while providing attractive returns to investors.
“NHFIC is very important for financing, because it’s possibly as low a cost for borrowing you could ever achieve,” says Wendy Hayhurst, chief executive of the Community Housing Industry Association.
“And it’s performed very well because it’s got a government guarantee.”
A new home for Steven and Kerry
With help from Angela the twins moved into a Specialist Disability Accommodation property purpose-designed by Hume to meet their high-support needs.
The Cerebral Palsy Alliance worked closely with Hume to ensure the fit-out was purpose-built for the twins’ evolving needs and staffed with familiar faces.

After walking through the Hume property in south-west Sydney – perfectly designed for wheelchair use and built to platinum-level Livable Housing Design Guidelines – Judith felt comfortable with the decision.
But it was still hard to let them go.
“I knew it would be hard to let go of my children,” says Judith. “I thought they’d be lost without me. I was certainly lost without them.”
“[But] I couldn’t be happier. It was perfect for the twins. It kept them together.”
Rudy and Judith could live peacefully knowing the twins were well looked after in “such a lovely place” close to their own home.
After decades of sacrifice, they have also been finally able to do something they have never done before – enjoy a holiday on their own – something Judith admits “they never would have considered if the twins were still at home”.
Pendal thanks Hume Community Housing for their co-operation in producing this article. Hume is a Community Housing Provider with more than 30 years experience in providing homes and services to more than 9000 customers in NSW. For more information go to www.humehousing.com.au
About Murray Ackman and Regnan
Murray is a Senior ESG and Impact Analyst with sustainable investing leader Regnan.
He also provides fundamental credit analysis on Environmental, Social and Governance factors for Pendal’s Income and Fixed Interest team.
Murray has worked as a consultant measuring ESG for family offices and private equity firms and was a Research Fellow at the Institute for Economics and Peace where he led research on the United Nations Sustainable Development Goals.
Find out more about Regnan here
Regnan Credit Impact Trust is an investment strategy that puts capital to work for positive change.
Pendal Sustainable Australian Fixed Interest Fund is an Aussie bond fund that aims to outperform its benchmark while targeting environmental and social outcomes via a portion of its holdings.
- Retailers are resetting business models, adapting to online shopping
- E-gaming, gyms and childcare to boost shopping malls
- Property investors should take a closer look at the once-maligned sector
A SURPRISING resurgence in retailing is underway in the real estate industry as shopping malls reset around food and entertainment, fending off the threat of online vendors.
E-sports computer gaming, gyms, childcare centres and even car dealerships are driving a renaissance at shopping malls, which are emerging strongly from 18 months of pandemic restrictions and lockdowns.
Pendal’s Julia Forrest, a portfolio manager specialising in property for the Australian equities team, says during the reset forced on the sector by COVID-19 retailers closed unprofitable stores and optimised staffing levels.
It also forced landlords to the negotiating table to reset rents at lower but more sustainable levels for the long term.
“The retail sector is probably in a better position now than it was at the beginning of 2020,” says Forrest.
Amid further lockdowns across the country and the threat of a resurgence of the pandemic, the strong outlook for retail is an important and unheralded theme for portfolio construction.
Before the pandemic, the retail sector was under pressure. Sales growth was falling, shops were cutting shifts, discounting was on the rise and some retailers were closing or going into administration.
“We went into 2020 expecting rents to fall but for completely different reasons than COVID,” says Forrest.
“But the rental reset in 2020 was somewhere between 12 and 15 per cent lower.”
“You can be more certain about the cash flows with retailers going forward.”
Julia Forrest
The lower rents, coupled with government subsidies for wages, the closure of less profitable stores, higher productivity as staffing levels were reset and a move to online and omni-channel retailing, has put the sector in a better position than many expected.
At the same time, strong demand for other property assets like office and industrial has improved the relative attractiveness of malls for investors.
“You can be more certain about the cash flows with retailers going forward.”
Omni-channel approach
Forrest says shopping malls are adapting well to the threat of online shopping, moving to an omni-channel approach and lifting the experiences available at a mall.
“There’s e-gaming that has opened in one of the centres in Victoria that’s drawing in young teenage boys, which isn’t the typical target market for malls.
“They are adding childcare centres to the periphery. They’re starting to add car dealerships and things like car care and parts – the kind of thing that you’ve seen in the bulky goods category or large format retail are now moving into malls.”
Forrest says investors should keep an eye on the big asset sales in the pipeline to gauge how valuations are changing.
“The AMP assets, Pacific Fair and Macquarie Centre will probably trade, and they’ll probably trade close to book value.
“That’s a reflection of capital seeking best quality assets with good locations and optionality from repurposing.”
About Julia Forrest and Pendal Property Securities Fund
Julia has managed Pendal’s property trust portfolios for more than a decade. She has 25 years of experience spanning equities research and advisory, initial public offerings and capital raisings.
Pendal Property Securities Fund invests mainly in Australian listed property securities including listed property trusts, developers and infrastructure investments.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Contact a Pendal key account manager here.
Here’s what’s driving Australian equities this week according to Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
SYDNEY’S LOCKDOWN dominated local news last week, but the S&P/ASX 300 fell only 0.5%.
The takeover bid for Sydney Airport (SYD) reminded us of the abundant liquidity — and propensity among long-term investors to look through Covid-related earnings issues, supporting market sentiment.
At a global macro level we saw bonds rally for the first four days of last week. This reinforces the narrative that we are through peak growth and the delta variant is exacerbating a global slowdown.
Sentiment reversed on Friday, perhaps suggesting that sentiment had turned too negative. We expect more sentiment swings through the northern summer as we wait for data on the economy and the effect of the Delta variant.
There are signs of a potential stimulatory shift in Chinese policy. This could be a positive development that supports resources in coming months.
Outlook for Covid and vaccines
The Sydney outbreak has taken a turn for the worse, breaking containment lines. We are now looking at a far longer period of restrictions.
While Covid remains contained to Greater Sydney the economic impact will be material, though not severe for the broader domestic economy.
Growth in new case numbers is tracking worse than Victoria’s second wave last year. On the plus side tightened lockdown measures, higher testing numbers and the ability of contact tracers to identify exposure sites should help. But the higher transmissibility of the Delta variant is an offsetting factor.
The Delta variant is now dominant in the US, prompting further scrutiny. At this point it appears cases will start to rise materially. The key variable is what this means for hospitalisations. Until we have greater visibility the market may continue to worry about the potential for restrictions to return.

The UK continues to run the gauntlet on new cases. So far a surge in infections has not translated into hospitalisations.
There is a growing debate about the effectiveness of vaccines and the need for boosters. Early studies on Delta indicated the mRNA vaccines were very effective — well into the 80% range in preventing Covid.
But data from Israel is concerning. It indicates the effectiveness of Pfizer in preventing Delta infections is in the mid-60% range. This is from a larger sample set than previous studies.
This could be due to the fact that Israelis had their injections four-to-five months earlier, which may suggest waning immunity and a lower efficacy in preventing infection.
The vaccines are still highly effective against severe infections. But this shows why a debate over the need for booster shots is gaining impetus.
Economic outlook
We have had a series of weaker data points for the first time in months. US unemployment, PMI data, unemployment claims and vehicle sales have all softened and money supply growth has slowed.
Much of this can be explained by holidays, shortages of certain products or labour and some hot weather. But it is a trend that needs to be watched. Along with the increasing prevalence of the Delta strain this has triggered a further flattening of the yield curve on concerns for near-term economic growth.
We need to bear in mind the link between market price action and policy.
There is a view that if inflation and growth expectations soften sufficiently – and the yield curve flattens below 100bps – we could see the Fed delay tapering. This moderating factor suggests we may be near the end of the recent rally in bonds, although a move higher is unlikely in the next few months.
In China the State Council signalled a shift in policy to be more supportive of growth. A cut in the reserve requirement ratio (RRR) for banks followed, which can help credit growth.
This is most likely in response to weak consumption. But China faces a similar challenge to Australia: low levels of immunity and a reliance on vaccines that may have limited effectiveness against the Delta strain. This could force the Chinese to maintain restrictions for longer.
Beijing’s move to prop up growth via traditional investment-related stimulus would be supportive of commodities.
Meanwhile the European Central Bank announced its policy framework.
The ECB is taking a less activist approach to inflation than the Fed. They will tolerate an overshoot of inflation targets, but won’t actively try to generate inflation. The wash-out is no real shift in Europe’s more conservative approach.
Markets
Bond yields fell for much of last week on concerns over the economic outlook, before reversing on Friday.
As a result the US 10-year Treasury yield fell only 6 bps to 1.36%. The Australian equivalent fell 12 bps to end at the same yield.
Brent crude fell 2.7% despite the lack of a deal between OPEC and its partners on increasing supply. Concerns over growth — coupled with speculation that OPEC’s cohesion may be waning — are probably at play.
Most sectors in the S&P/ASX 300 fell last week, though the index was propped up by the bid for Sydney Airport (SYD, +33.4%). Otherwise there was a relatively small spread across sectors, with growth lagging after a good run.
The bid for SYD by a consortium of pension funds was last week’s big news. The offer of $8.25 per share was a 40% premium. It values the stock at 25x EBITDA based on post-Covid FY23 earnings, versus a historical trading range of 18-21x.
This represents an enterprise value of $30 billion versus the previous peak of $29 billion. We see this as a very competitive bid in the wake of an uncertain rate of recovery in international travel and the impact of the Western Sydney Airport. There may be a higher offer to follow, but the increase is likely to be small. The bid is conditional on board approval and Unisuper agreeing to roll its 15% holding into the venture.
Tabcorp (TAH, -8.1%) announced a plan to demerge its Lotteries and Keno business by June 2022, effectively rejecting offers for its wagering business. The stock’s fall reflects the high cost of the demerger – a $225 million to $275 million one-off and $40 million ongoing.
Crown (CW, -7.8%) delivered a market update that was softer than expected. Market attention remains fixed on the Victorian Royal Commission, which has now ended and will report in October. The risk of losing its licence – as well as the potential impact on revenue from upgraded compliance procedures – will have an impact on valuations from potential bidders.
Ramsay Health Care (RHC, +0.7%) raised its bid for UK-listed private hospital group Spire. This is unlikely to change the minds of big shareholders who hold a blocking stake to prevent the deal. This leaves the company back where it started, but in a bit of strategic bind, which is reflected in the price.
A2 Milk (A2M, +10.4%) has rebounded on signs of an improvement in volume and pricing in China’s infant formula market. We remain wary. China’s low birth-rate will likely result in lower demand, while local providers continue to gain market share.
Viva Energy (VEA, +5.9%) delivered a well-received update. EBITDA was well ahead of consensus and the non-refining business is back to its previous peak profit level, despite a decline in the aviation business. This demonstrates the industry structure is helping support margins, while the company is also controlling costs. Government moves to protect refining have also removed a great deal of uncertainty.
Here’s our weekly Bond, Income and Defensive Strategies wrap from Pendal portfolio manager Tim Hext (pictured).
THE RESERVE BANK last week started the slow unwind of extraordinary monetary policy.
In recognition of the overall stronger economy, Yield Curve Control will not extend beyond the current April 2024 bond.
When the current $100 billion of Quantitative Easing (QE) ends in September, the pace will fall from $5 billion a week to $4 billion a week. It will be reviewed again in November.
Together with the closing of new borrowing from the Term Funding Facility (in total $187 billion lent) this represents the first steps back toward conventional monetary policy.
In our view the timeline looks something like this:
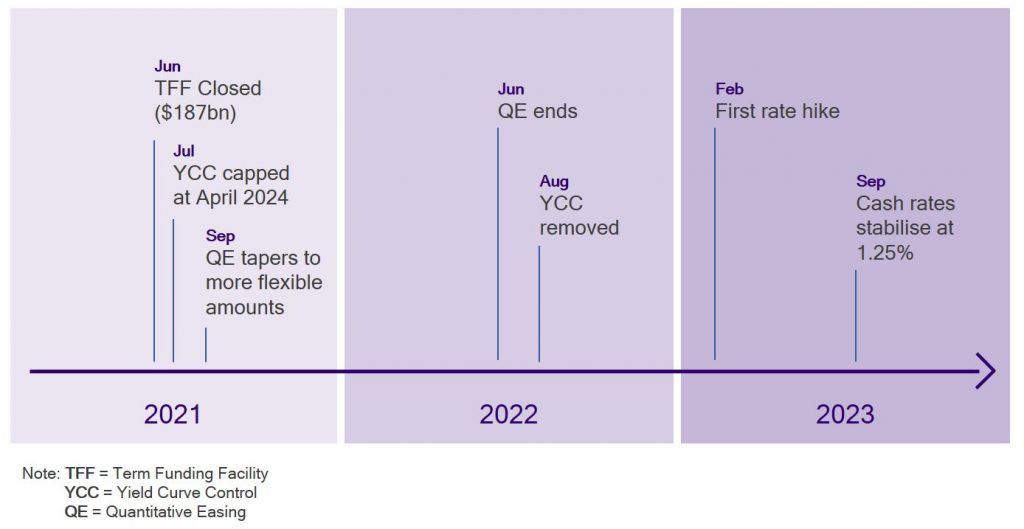
QE will likely taper further once the US Fed starts its own taper later this year.
The end of QE is probably brought forward by recent AUD weakness, relieving RBA concerns that higher rates here would push the AUD above 80c.
Of course there are a number of clear criteria laid out by the RBA to actually hike cash rates.
Inflation must be sustainably within the 2-3% band. For that to happen they believe wages need to be at least 3%, which in turn requires full employment.
The view is full employment is nearer 4% than 5%. We wrote extensively about employment and wages in our last newsletter. (Contact a Pendal key account manager for a PDF copy).
Given our views on inflation and wages we expect rates to lift-off in the first half of 2023. We expect them to stop around 1.25% to 1.5% before staying there for some time.
Of course this is a view into the future. In a week dominated by lockdowns and US bond rallies, bond markets here saw lower yields.
There is a lot more to play out in US employment markets in the months ahead.
Unlike Australia where jobs are now higher than before Covid, the US still has 8.5 million jobs “missing”.
The bulls blame higher welfare payments discouraging people from returning to low-paying jobs. The bears suggest COVID has shown the way for businesses to permanently operate with fewer staff.
The truth is likely a bit of both.
How this plays out in the months ahead will set the tone for bonds markets and eventually equity markets.
We will dive deeper into this topic in the weeks ahead.
About Tim Hext
Tim Hext is a portfolio manager with Pendal’s Bond, Income and Defensive Strategies (BIDS) team.
Led by Vimal Gor, Pendal’s BIDS boutique is one of the most experienced and well-regarded fixed income teams in Australia. In 2020 the team won the Australian Fixed Interest category in the Zenith awards.
The team oversees $22 billion invested across income, composite, pure alpha, global and Australian government strategies with the goal of building Australia’s most defensive line of funds.
Find out more about Pendal’s fixed interest strategies here
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
China’s authorities are re-examining rules around Chinese companies listing outside the country’s stock exchanges. Samir Mehta (pictured) – portfolio manager of Pendal Asian Share Fund – explains what it means for investors
CHINA is reviewing the rules that govern its companies listing on foreign stock exhanges. What does this mean for investors?
Before we consider this, it’s useful to understand three cross-currents affecting Chinese technology businesses and stocks:
1. Regime change under President Xi
The Chinese leader has articulated more forcefully than most that the Chinese Communist Party (CCP) is supreme. Jack Ma found this out to his detriment when he made a speech in which he was critical of regulators. It is acknowledged off the record by people in the know that a large shareholding in Ant Financial is owned by the Shanghai faction (those considered close to ex-President Jiang Zemin – a political rival of the current administration).
2. A clear ideological battle-line drawn under President Trump’s administration in 2018
I do not think this is a clear-cut ideological contest between capitalism (the US) and communism (China). The CCP is a Marxist-Leninist party which uses the tools of capitalism effectively. This ideological divide is more about superpower rivalry, and we happen to have a label attached to it.
3. Data is the real source of the current predicament for governments
The collection, use and security of data are now arranged around national boundaries. Any industry considered a national priority or subject to national security is now wrapped in data nationalism. Accounting oversight for US-listed securities (rightfully demanded by US Congress through the Public Company Accounting Oversight Board) flies in the face of data nationalism.
China reviews foreign listing rules
Chinese authorities are currently re-examining rules around listing outside China’s stock exchanges.
“Once amended, the rules would require firm structures using the Variable Interest Company (VIE) model to seek approval before going public in Hong Kong or the US,” Bloomberg reported recently.
The VIE model was pioneered by Chinese Internet company Sina Corporation in 2001 as a means to list its shares on the New York Stock Exchange in 2001. It set the stage for a flood of IPOs and capital raisings by Chinese companies in US capital markets.
Scroll down for an explanation of the VIE model.
Since 2018 I have considered any Chinese ADRs as risky for exactly this eventuality.
Hence, in the past two-and-a-half years, I have chosen to own stocks listed either on the Hong Kong or the Shanghai/Shenzhen stock exchanges.
I have a large underweight position in China, partly due to valuations, partly because of increased regulatory risks and partly on account of the tightening macro environment.
Following recent events I have to wait and judge whether Hong Kong-listed firms are likely to be dealt with as heavy-handedly as any US-listed Chinese stocks.
Rationally speaking that should not be the case. The Chinese mainland now completely controls Hong Kong – but geopolitics and national security concerns can trump rationality.
The other big risk revolves around data and business models.
In the US technology behemoths operate in loosely defined spheres of influence (Facebook vs Amazon vs Microsoft vs Google). That is not the case in China.
Every large company and upstart challenger wants to encroach upon and compete against incumbents, using not just data but aggressive cash burn and sometimes harsh competitive tactics (monopolising users or suppliers via threats).
Moats matter
This requires a return to first principles – to understand what is the genuine competitive moat for a business.
And we need to analyse whether that moat is now threatened by Chinese government’s imposition of national security priorities. This is not going to be easy.
My fortune in positioning the portfolio with a large underweight in China allows me some breathing space. Markets by definition are fickle and move from euphoria to panic, as we currently observe.
I welcome that wholeheartedly. Consternation concentrates the mind.
Learn more: what is a Variable Interest Company (VIE)?
China’s Sina Corporation pioneered the concept of the Variable Interest Company (VIE) as a means to list its shares on the New York Stock Exchange.
The first Chinese internet company to do so in 2001, Sina set the stage for a flood of IPOs and capital raisings by Chinese companies from US capital markets.
It was an ingenious legal “contract”.
“It enabled Chinese companies to sidestep restrictions on foreign investment in sensitive sectors including the Internet industry,” Bloomberg columnist Matt Levine commented earlier this month.
“The structure allows a Chinese firm to transfer profits to an offshore entity – registered in places like the Cayman Islands or the British Virgin Islands – with shares that foreign investors can then own.”
Those were the heady days of globalisation, marked by China’s entry into the World Trade Organization (WTO). The internet was in its infancy while Asian economies were struggling from the aftermath of the financial crisis of 1997-98.
As that decade progressed, one catchphrase became increasingly popular: “economic decoupling”.
Most economic forecasters and market participants (myself included) hoped for or predicted the imminent cutting of the umbilical cord that joined Asia to the West. That moment of decoupling is upon us, although the contours are vastly different from what we envisaged.
Churchill’s characterisation of the Soviet Union in October 1939 as “a riddle wrapped in a mystery inside an enigma” is an apt description of the VIE structure.
Again quoting Matt Levine at Bloomberg (everyone should read his work):
“I have a soft spot for Chinese VIEs. The idea is that, under Chinese law, it is somewhere between “complicated” and “forbidden” for foreigners to own certain big important Chinese tech companies. This is a problem for those companies if they want to raise capital from foreign investors and list their stocks on foreign stock exchanges. But there is a solution. Ownership of a company is a complicated notion, a vague jumble of rights to elect directors, approve mergers, and claim a residual interest in the company’s cash flows. You could break those things up and sell them separately.
“Write a profit-sharing contract that says: ‘A will pay B all of A’s profits after expenses for the next 100 years, renewable at B’s option,’ and hey that’s a residual claim on cash flows. (Or something more vague: ‘A will pay B an annual consulting fee that B decides in its total discretion based on the economic value of the relationship,’ etc. Not technically a residual claim but what else is it?). ‘B will provide management services to A and A will follow B’s instructions,” hey that’s basically control. ‘B will have the right to appoint a majority of A’s board of directors,’ put it in a contract, it’s not actually stock ownership. Etc. Write some contracts that, bundled together, look like ownership, but aren’t ownership.
“With Chinese companies, this sort of thing is generally called a ‘variable interest entity’. You set up a company in the Cayman Islands that can be owned by anyone. The Caymans company enters into a series of contracts with the local Chinese company, giving it, not ownership, but certain carefully curated economic interests and control rights over the Chinese company. Then you list the Caymans company in the US, and people buy its stock, and they sort of pretend that they’re buying stock in the Chinese company — they sort of pretend that the Chinese company is a subsidiary of the Caymans holding company — even though really they’re only buying an empty shell that has certain contractual relationships with the Chinese company.”
About Samir Mehta and Pendal Asian Share Fund
Samir manages Penda’s Asian Share Fund, an actively managed portfolio of Asian shares excluding Japan and Australia. Samir is a senior fund manager at UK-based J O Hambro, which is part of Pendal Group.
Pendal Asian Share Fund aims to provide a return (before fees, costs and taxes) that exceeds the MSCI AC Asia ex Japan (Standard) Index (Net Dividends) in AUD over the medium-to-long term.
Find out about Pendal Asian Share Fund
About Pendal Group
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Pendal’s Sustainable Australian Fixed Interest Fund invests in social bonds that help vulnerable Australians while also aiming to generate strong returns. This is the story of a family helped by Hume Community Housing, which is partly financed by those social bonds.
There are few things as devastating as a marriage breakdown.
When a parent with three children suddenly becomes single and homeless it can seem like an impossible situation.
Things were grim for Samuel and his family when they found themselves homeless. In desperation, they were forced to live on an overcrowded property with his parents.
Samuel had grown up in social housing and overcome many challenges. Now circumstances threatened to pass on generational disadvantage to his children.
Fortunately, he was put in touch with Hume Community Housing via Uniting’s Doorways for Men with Families program.
Hume is a Community Housing Provider (CHP) which develops affordable housing for low-income Australians with help from investors in Pendal’s Sustainable Australian Fixed Interest Fund.
Hume’s funding comes partly from the federal government’s National Housing Finance and Investment Corporation (NHFIC), which raises money by issuing social bonds to investors such as Pendal.
NHFIC lends out the money raised (more than $2 billion so far) to CHPs at low interest rates and on better terms than banks — while providing attractive returns to investors.
Cheaper financing means CHPs such as Hume can help more people like Samuel and his family.
Lives turned around
Hume runs a housing independence program that helps people like Samuel transition from homelessness to longer stable accommodation.
Hume provided housing to Samuel and his family at a low cost, allowing the single dad to provide for his family and build up a solid tenancy record.
This turned Samuel’s life around – as well as that of his children.
“Hume were incredible,” says Samuel. “They always called in to see me. They cared.”

After an initial meeting Hume quickly sprang into action.
Three days later they phoned and asked Sam to visit one of their locations in Claymore in south-western Sydney.
He accepted the place on the spot.
Samuel began building ties in his new community by fixing bikes for local children.
Soon the whole neighbourhood could watch their kids race their bikes on the street.
“I got all the bikes off the rubbish piles and fixed them up. Every kid in our street had a bike by the end of it and they were all happy.
“Somebody was throwing out a lawn mower, so I fixed it and before long everybody in the street was using it. We interacted more as a community and we became friends. Even men in the street stepped in to support one another if they needed it.”
Help from Hume
Helping with the transition was Hume’s Housing Independence Officer Sedina, who worked closely with Samuel, connecting him to support services and ensuring his family’s wellbeing.
Sedina went above and beyond the call of compassion. At Christmas time Hume told him when the local church was giving out presents for the kids.
“When Sedina would come into the street, even if she was speaking to someone else on the street, she’d get out of the car and talk with the children and say hello and ask if there was anything that needed to be done to the house and if we needed anything,” says Samuel.
Pendal Sustainable Australian Fixed Interest Fund
An Aussie bond fund that aims to outperform its benchmark while targeting environmental and social outcomes via a portion of its holdings.
Hume is part of the thriving Community Housing Provider (CHP) sector which manages more than 35,000 properties in NSW alone.
With help from funding from the National Housing Finance and Investment Corporation, Hume aims to help Australia’s diverse community maintain their tenancies, break the cycle of disadvantage, participate in life, and to reach their full potential.
“NHFIC is very important for financing, because it’s possibly as low a cost for borrowing you could ever achieve,” says Wendy Hayhurst, chief executive of the Community Housing Industry Association.
“And it’s performed very well because it’s got a government guarantee.”
In Samuel’s case it’s been a resounding success. After five months on the Hume program and with a stable rental record, Samuel and his family secured a private rental tenancy closer to his extended family.
You can see the joy on his children’s faces as they play on the swings, knowing they are on the path to a brighter, more secure future.
“To be honest, I was stuffed before coming to Hume,” says Samuel.
“My kids are happy and settled and we’re doing more family-oriented stuff now. Hume helped me to get my life back.”
Pendal thanks Hume Community Housing for their co-operation in producing this article. Hume is a Community Housing Provider with more than 30 years experience in providing homes and services to more than 9000 customers in NSW. For more information go to www.humehousing.com.au.
About Murray Ackman and Regnan
Murray is a Senior ESG and Impact Analyst with sustainable investing leader Regnan.
He also provides fundamental credit analysis on Environmental, Social and Governance factors for Pendal’s Income and Fixed Interest team.
Murray has worked as a consultant measuring ESG for family offices and private equity firms and was a Research Fellow at the Institute for Economics and Peace where he led research on the United Nations Sustainable Development Goals.
Find out more about Regnan here
Regnan Credit Impact Trust is an investment strategy that puts capital to work for positive change.
Pendal Sustainable Australian Fixed Interest Fund is an Aussie bond fund that aims to outperform its benchmark while targeting environmental and social outcomes via a portion of its holdings.