
Avoiding a double-dip recession: portfolio manager Tim Hext (pictured) of Pendal’s Bond, Income and Defensive Strategies team will discuss this in the article below.
My first year in markets was 1989 and my first trade was buying some bank bills at 18.5%. I should have bought a 30-year bond!
Crushing inflation had become a cruel venture, bringing on the recession that Paul Keating said we “had to have”.
Living in Melbourne in 1990 was to witness first-hand an imploding economy. Businesses closing almost every day. Unemployment soaring. House prices collapsing. People struggling. Any job was a good job — forget whether it was inspiring.
Recessions were seen as a natural part of the business cycle.
In the early 1990s, even the most optimistic economist would have expected another recession within 10 years. The odds of a 30-year wait would have been longer than Parramatta or Carlton going without a premiership for decades. The true miracle was avoiding a recession during the GFC. China rode to the rescue and the real economy avoided the fate of financial markets.
Walking around a number of shopping centres and strips in the past month brought back memories from Melbourne in 1990. “For Lease” signs everywhere and shops boarded up. I stopped to look in the windows of closed businesses. Some signs said “Opening Soon When Safe” – but sadly many have closed for good.
Large numbers of retail stores were marginal before the crisis. Rent relief beyond 50% was at the behest of landlords. Some landlords have worked to keep tenants but others have merely added the other 50% to future bills.
Perhaps the crisis has merely accelerated the push to clicks over bricks – and retail will bounce back. If enough workers are still getting paid they will spend it online. Restaurants may survive via delivery. The fleets of electric bikes around my neighbourhood have swollen.
Last quarter I spoke about the shape of the recovery as the economy cautiously began to open up.
Adding to the list of V, L, U and W we now have the Reverse Square Root, the Nike Swoosh, and other shapes showing the speed of the recovery.
This quarter I will look at the progress so far and ask the question: when will we get back to where we were in February? We did not know it at the time, but the high-water mark fell in between the bushfires and COVID.
In February 13,056,700 Australians were employed. This was an all-time high. Australia’s population was 25.5 million. The population increased by 350,000 in the prior year including 210,000 being migrants. A record 66% of Australians over 15 years of age were either working or looking for work, meaning an unemployment rate of 5.1%.
Flash forward to May 30 and 7.5% of jobs had been lost according to tax office data. This equated to 980,000 jobs. At the worst point in April, it was 9% or 1.18 million. These are jobs where people are not getting paid. How many will return with the re-opening of the economy and how many have disappeared permanently? That remains to be seen.
Graph 2 shows the different measures of employment. Since March the Bureau of Statistics has released tax office data in a weekly payrolls report. This data is electronic rather than survey-based like the official labour force numbers. This is a far more accurate measure. It captures the large cohort of workers laid off but waiting for businesses to reopen so they can hopefully get their jobs back.
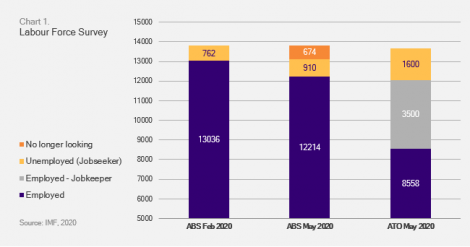
On March 20 Newstart was renamed JobSeeker and increased from $550 to $1100 a fortnight. About 1.6 million Australians are now on JobSeeker, up from 700,000 on Newstart in February. The labour force survey shows 835,000 jobs lost from February to May.
Where it gets interesting is the collapse in the participation rate from 66% to 63%. The labour force survey suggests only 210,000 people joined the unemployment queue with the rest dropping out. This conveniently keeps unemployment at 7.1%, not the 12% other measures are showing.
When asked in the survey “are you looking for work”, it appears for various reasons a large number of people are saying “no”.
JobSeeker numbers reveal the true damage. Numbers suggest everyone who lost a job is now on JobSeeker – even if they tell the Bureau they are not looking for work. The JobSeeker eligibility requirement of “actively looking for work” has been temporarily waived, but will return shortly.
Then there is JobKeeper. This is designed to keep people employed even if they are not working – or are working fewer hours. The $1500 fortnight payment, designed to roughly match the minimum wage, is paid through the employer in arrears. Businesses must have suffered a 30% fall in turnover if less than $1bn or 50% fall if greater than $1 billion. Numbers on JobKeeper are estimated to be 3.5 million after a mistake initially predicted 6.5 million, or half the workforce.
JobKeeper is scheduled to end on September 27 although it may be tightened rather than abandoned altogether. No system is perfect. Some businesses believe they are more viable while closed under JobKeeper, which the government doesn’t want to encourage. For smaller businesses 80% turnover means losing JobKeeper – while also likely remaining unprofitable.
GDP is a volume-based measure. It’s called a chain volume because it’s linked quarter by quarter. There are three approaches to measuring chain volume – income, expenditure and production. Headline GDP is a simple average of the three.
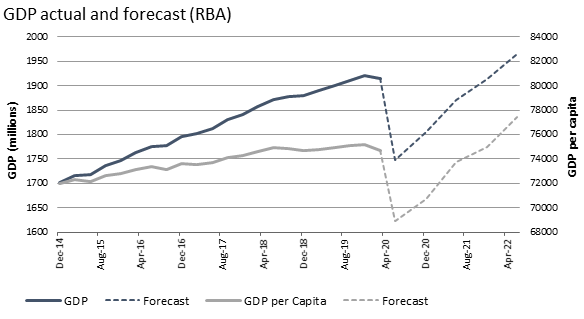
In volatile times like this GDP can be confusing because it’s always reported as a growth number. The real question is how long it will it take the economy to get back to pre-COVID levels. The following graph shows the actual GDP rather than the rate of change. The graph also shows GDP per capita, a better measure of productivity in the economy.

It will take until early 2022 for the economy to return to its December 2019 size, based on estimates from the RBA’s May Monetary Policy Statement.
The RBA has tended to overestimate GDP in the past five years. Health outcomes make forecasting extremely difficult of course, but this assumption looks optimistic.
Viewed from a GDP per capita basis, however, the picture is less dramatic. Almost half of Australia’s GDP growth over the last decade has been due to immigration. Australia’s population growth has now collapsed and is unlikely to resume to pre-COVID levels for a number of years. This may mean GDP per capita has a better chance of improving.
Forecasting medium-term inflation followed some simple rules over the past 25 years. From 1993 to 2012 tradables (40% of CPI) were largely flat. Non-tradables (60% of CPI) were 4%, landing around the 2.5% target. In the last decade, non-tradable inflation started to fall to around 3%, led by health and education. This meant CPI settled closer to 2%.
Even before the crisis non-tradables were beginning to slip to 2% and CPI closer to 1.5%. This was largely due to a fall in housing (rents, building costs and utilities), which we viewed as cyclical, not structural. This meant we entered 2020 sharing the RBA’s confidence that CPI would drift back to 2% over 2020 as population growth and a lack of new building activity kicked in. COVID-19 has shot down that view.
The story of the economy is now one of widespread excess capacity. Shutdowns meant demand and supply were both hit. Coming out of shutdowns there are pockets of demand exceeding supply as global supply chains have been hit. However, in the larger items – particularly labour – excess supply dominates.
Joining this mix is a move to wage freezing. This is led by governments but is also likely in the private sector. The recent minimum wage decision gave a 1.9% increase, down from 3% or higher compared to recent decisions. However, as the pool of labour supply increases in many areas, new employees may come in on lower wages.
The real area of concern for inflation is rents. Rents make up 8% of the CPI basket, large enough to move the dial overall.
In pockets of inner-city Sydney and Melbourne, rents are already down about 6%. The levelling of the population means negative rent growth will spread to wider areas in these cities, which rely heavily on students and international workers for tenants. Other cities and rural areas may be less affected. But if rents were to fall 3% nationally this would feed into a 0.25% fall in inflation. There may also be second-round effects.
Until recently the RBA was happy to forecast and accept 2% CPI as the long-term average, despite a formal 2-3% target. Markets now have that closer to 1.25% over the next decade, after falling as low as 0.5% at one point. From a bottom-up perspective even 1% looks optimistic over the next few years.
CPI will be negative 1% or even lower in the June quarter, largely due to free childcare during the quarter. This will be removed, but an era of frozen costs seems here to stay across wide areas such as education, healthcare and government charges.
Excess supply in the economy will be with us for at least the first half of this decade.
Structural forces already in place were accelerated by COVID-19 and low GDP and inflation have pushed rates close to zero. The RBA believes negative rates do more harm than good, so they have stopped at zero. The stimulus required from monetary policy for a crisis of this scale was not there – otherwise rates would now be -3%.
Unconventional policy has held down term rates but this really only helps around the edges. Put simply, the RBA has done an excellent job from a liquidity role during this crisis – but from an economic stimulus role it has turned up with a knife to a gunfight.
The federal government now has all the firepower. The initial response to the crisis has been excellent overall. Fiscal policy needs to more permanently enter a new era. Ghosts of Tony Abbott’s debt scaremongering still seem to have an influence in Canberra.
Already there is talk of how we are going to pay for all this stimulus and that we are labouring future generations with our debt. You would think the government is a household; with a printing press out back it is not. If Australia is to avoid a lost decade we need to get comfortable with government debt sooner rather than later.
Short rates stuck at zero mean longer rates will also be supported. Any sell-offs in bonds as the economy opens up and data picks up should be bought into. Term premium should not drift higher despite the usual scaremongering around money supply pushing up inflation.
The same voices were out there after Quantitative Easing during the GFC. Once again they will be disappointed. One of the best trades earlier in the decade was harvesting the high carry and roll available. Levels today are not so generous, but still offer good value.
Australia has begun the long, slow grind of re-opening the economy.
Some damage will be repaired quickly while other damage has been terminal. As always, health outcomes partly hold the key to the speed of the recovery. However, the federal government is now front and centre and its actions can either prevent or cause a double-dip recession. The more timid their fiscal policy, the longer, deeper and more painful the slowdown.
Bond markets will remain well supported. Plenty of countries have been down this path before us and so far only the US managed, at least for a while, to emerge from the anchor of zero rates. They look like the exception, not the rule.
The grab for yield is once again upon us. For now it is a trend you must go with rather than fight.
We remain long duration and in portfolios with credit overweight investment grade. These themes have further to run in the quarters ahead.
Tim Hext – portfolio manager with Pendal’s Bond, Income and Defensive Strategies team.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
https://www.pendalgroup.com/about/our-people/sales-team/
Fixed income impact investment is a fast-growing but still relatively new segment of capital markets. Here Pendal portfolio specialist David de Ferranti (pictured above) takes a deep look at impact bonds.
This quarter we saw COVID-19 impact the way businesses organise physical workforces. Social distancing measures closed doors across industries such as the local cafe, a favourite hotel or the office foyer. Despite difficult and ongoing challenges posed by such restrictions, it is encouraging to see new doors opening for some of those most at risk in the current environment.
Those in need of more affordable housing options — such as disadvantaged youth, the homeless and victims of domestic violence — will be among the beneficiaries of significant proceeds raised by a social bond issued in Australia last month. The deal from the National Housing and Finance Investment Corporation (NHFIC) amounted to A$562 million. It was the largest amount raised by a domestic social bond to-date. The issuance was well-received by investors and Pendal’s sustainable fixed interest strategy was able to participate.
In our Beyond the Numbers report we have written about the positive impact Community Housing Projects (CHPs) financed by the NHFIC can have for individuals at risk. Now, during the coronavirus crisis, affordable and social housing providers are even more critical. This is true not only for those impacted by reduced employment options. The benefits also flow to the residential construction sector, which brings broader benefits to the Australian economy amid a very tough economic outlook.
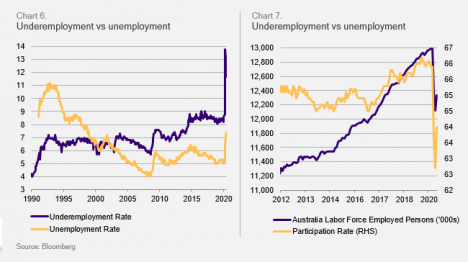
Domestic employment data shows the virus’s severe impact on our labour market. Some 664,000 jobs were lost between March and June this year, bringing the unemployment rate to 7.4%. The percentage of those seeking more hours and categorised as underemployed rose to 11.7% (Chart 6). Many individuals left the labour force altogether, reflected in a lower participation rate. This led to a dramatic drop in the number of total employed across the country (Chart 7).
The government’s JobSeeker and JobKeeper subsidy packages have offered some reprieve to those who have found themselves in financial distress. However, these stopgap measures do not address core issues faced by financially disadvantaged individuals over the longer term. Even with JobSeeker payments, only 1.5% of rentals are considered affordable, while with no JobSeeker rentals in the majority of Australian capital cities are unaffordable.1 Before the pandemic there was already a significant supply shortage of affordable and social housing. Australian Institute of Health and Welfare data shows roughly 140,000 Australians were on a waiting list for social housing, often equating to years in the queue.2
Certain demographics continue to be disproportionately affected by housing-related challenges. This includes women living in regional areas. Roughly one in eight have been homeless in the last five years and one in five know a homeless woman, according to the YWCA’s Women’s Housing Needs in Regional Australia report. When asked what would improve their situation most, about half responded with a reduction or subsidy of housing costs.3
Beyond the negative impact on individual financial situations, COVID-19 threatens further weakness for the residential construction industry, where activity was already on a downward trajectory. New commencements are expected to follow building approvals lower. HIA forecasts a fall in dwelling starts to 134,000 in FY2021, down from a peak of 230,000 in FY2018. This reduction in new supply of homes threatens not just the at-risk individuals noted earlier, but the livelihoods of those in the residential building industry.

The proceeds of the latest NHFIC social bond will not resolve the issues described here. But they will make a significant contribution to the lives of those in need of housing assistance and help keep a number of tradespeople in work. Some 7100 new homes and management of existing properties have been financed by the NHFIC issues to-date.4 The latest deal financed 10 CHPs, which have operations in a range of regions and are targeted at different demographics.
This includes Women’s Housing Limited which received a $9 million loan to refinance existing debt and buy new properties.5 These new properties will house women escaping domestic violence, who will be able to pay a rate much lower than the market rent. This helps essential workers in vital services such as healthcare and hospitals live closer to their workplaces.
The biggest recipient of financing was Sydney-based SGCH, the largest CHP in NSW. Its loan will help support 305 existing dwellings and 235 new homes in Australia’s most expensive rental market. The low rate provided through the NHFIC facility was estimated to save $40 million over its term — funds that can be invested in hundreds of other homes.6
Other recipients included Argyle Housing which supports regional communities via affordable housing. Recent projects have included new homes in Griffith for workers in the agricultural industry, as well as areas with at-risk youth in Wagga Wagga. Housing Choices Tasmania received financing for new developments across the state.
New homes created by these CHPs will make direct and indirect contributions to the residential construction industry. For each $1 million of output for the sector, nine jobs are supported and $2.9 million of output and consumption is created for the broader economy, the NHFIC estimates. This multiplier effect is calculated as the second-largest across all 114 industries in the Australian economy.7 Powerhousing Australia estimates the construction of a standard stand-alone three-bedroom house helps 43 trades and sub-trades gain employment.8
In this landscape of lockdowns, social distancing and housebound workers, a place to call home is of paramount importance. A safe and stable home has become even more critical. Building new homes for at-risk individuals brings security to the recipients and generates broader benefits to the Australian economy at a vital juncture. As investors in these bonds, we believe these outcomes also allow our clients to have a positive impact on fellow Australians when they need it most.
David de Ferranti – portfolio specialist with Pendal’s Bond, Income and Defensive Strategies team.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
https://www.pendalgroup.com/about/our-people/sales-team/
1 https://about.bnef.com/blog/sustainable-debt-sees-record-issuance-at-465bn-in-2019-up-78-from-2018/#_ftn1
1 Rental Affordability Snapshot, April 2020
2 AIHW, Housing assistance in Australia 2019
3 YWCA, Women’s Housing Needs in Regional Australia, 2020
4 NHFIC, NHFIC finalises largest social bond issue from an Australian issuer, 2020
5 Women’s Housing Limited, 2020
6 SGCH, 2020
7 NHFIC, Building Jobs: How Residential Construction Drives The Economy
8 Powerhousing Australia, Australian Affordable Housing Report F2021, 2020
Here’s what’s impacting Aussie stocks at the moment, according to Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
Main points
- Equity and bond markets remain in a holding pattern at an aggregate level, with the S&P/ASX 300 at -0.1% for last week
- A weaker shift in the US dollar was the catalyst for a shift higher in gold and prompted signs of rotation from growth to value
- In the US there are early indications that case-load growth and hospitalisations are peaking in the worst-affected states
- Domestically we saw extensions of the JobKeeper and JobSeeker packages; while the RBA has clearly signalled its intention to continue providing policy support
Australian outlook
So far the Victorian government has refrained from imposing Level 4 restrictions, but the growth in cases remains disappointing.
There are signs restrictions in Melbourne are slowing economic activity, while voluntary behaviour is having the same effect in Sydney.
This in part prompted clear policy signals last week. The federal government extended its packages, however comments from RBA Governor Phil Lowe were of most interest.
Lowe emphasised the view that social costs and degradation from recession and persistent unemployment were too high to allow the normal clearing mechanism of labour and capital markets. Instead, policy makers must do everything in their power to mitigate the effects of this crisis.
This shift in thinking away from a free market approach may be driven by considerations around the social effects of income inequality. It could also be driven by a view that labour markets are too rigid to react in a timely fashion to a shock of this nature.
Regardless, it suggests policy makers will continue to shore up growth, with Governor Lowe suggesting there are several more tools available if needed.
Global outlook
New daily US cases have levelled off over the past week and hospital occupancy rates remain stable in hotspot states such as Florida, Texas and Arizona. If the market starts to believe the health situation is moderating, it should be positive for sentiment.
Nevertheless US economic data was softer. Jobless claims rose week-on-week for the first time since March.
Real-time indicators such as restaurant bookings suggest momentum has stalled after an initial surge. However, the environment is uneven. Demand continues to grow in sectors such as housing.
The next tranche of policy support appears to have been delayed while the Republicans seek agreement on a package. We are now likely to see a gap of a week or two between the end of payments under the previous package and the start of the new.
Elsewhere, the speed and scale of a €750 billion package announced by the EU came as a pleasant surprise given the debate between the “Frugal Four” northern states and southern countries likely to be the main support beneficiaries.
Markets
The weaker US dollar was driven by a combination of factors:
- Worse Covid case load in US vs Europe, and its expected impact on economic recovery
- Positive policy surprise in Europe versus delays in US
- Growing uncertainty about the upcoming US election
- The impression that ineffective fiscal policy in the US puts more pressure on the Fed to ease in various forms.
Weakness in the USD adds to the bull case for gold. It is increasingly evident that virus spread is hampering economic re-opening in the US and is becoming a limiting force on growth.
Unlike places such as China, which have effectively eradicated the virus, it is making it harder to return to pre-Covid levels of economic capacity.
However policy-makers are baulking at allowing this to trigger a significant recession and are falling back to stimulus such as more debt and more money supply growth.
This has several important effects, including question marks over longer-term strength of the dollar. This is seeing strength in the value of real assets. In some ways this is positive because it suggests expectations around policy-supported growth remain reasonable.
A reversal in US dollar weakness would suggest a flight to safety on increased concern.
Inflation expectations have been rising in recent weeks, but have only recovered to pre-crisis levels. Further increases in inflation expectations would require people to start factoring in tighter labour markets, which appears unlikely at this point.
That said, inflation is showing up in areas such as real assets.
Value had a small bounce versus growth in equity markets last week. There is a case for further value outperformance if we see US cases plateau, more fiscal stimulus — and if US tech earnings don’t bring any further upside to already high expectations.
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and a strong track record leading Australian and European equities funds. He manages a number of our flagship funds along with one of the largest equities teams in Australia.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
https://www.pendalgroup.com/about/our-people/sales-team/
Here are the key factors influencing Australian equities this week, according to Pendal’s head of equities Crispin Murray (pictured above). Reported by portfolio specialist Chris Adams.
BOND and equity markets remain in something of a holding pattern. The S&P/ASX 300 gained +1.8% last week despite poor news on the COVID front including tighter restrictions and evidence of a slowing economic recovery.
The focus is now on key developments including:
-
- Imminent fiscal policy announcements in the US and Australia
- Medical strain resulting from the US caseload
- Victoria’s restriction level and NSW’s ability to contain the outbreak
- Upcoming earnings seasons in Australia and the US
Equities and bond yields have been relatively flat for a while and it feels like the above factors could drive volatility at some point in next 4-6 weeks. However it’s very hard to call how that plays out.
Most surveys suggest investors are bearish and expect the next move to be down. This already depressed sentiment could support a break higher if upcoming fiscal packages or management of the second wave of infections is better-than-expected. Higher infection rates make it easy to be bearish – but we caution against the view that a drawdown is inevitable.
The Australian outlook
There are three key issues at play:
-
- Will Victoria implement greater restrictions? The estimated economic effect of the current lockdowns is 0.5% to 1% for Australian GDP. This could more than double if Victoria moves to level 4 restrictions, halting all retail and construction activity. There is a lot of pressure to avoid an extension of restrictions, but ultimately the case load will dictate this.
- To what extent will an increase in NSW cases lead to more restrictions? Any economic impact would be 50% greater than Victoria.
- How would a renewal of NSW restrictions impact fiscal policy? The Victorian situation has increased expectations about the size of a fiscal package due to be announced this week. There is talk of an additional stimulus worth 1% of GDP. This would offset much of the concern over a “fiscal cliff” and highlights the fact that policy makers continue to underwrite the economy and prop up markets.
The US outlook
Hospitalisations are rising dramatically in the US, closing on the previous peak and set to go well past it. This has not yet converted to a material increase in mortality, given a wider spread of cases and better understanding of treatment. Pressure on hospital system is building and risk remains — but health infrastructure is coping so far.
Rising US cases have triggered a behavioural response which should help. Some 77% of American live in areas now requiring masks. Mobility data is signalling that less interaction is occurring, albeit without too severe a retracement in activity.
The most effective models suggest this US cycle in cases should peak in early August at the current rate. If this ends up breaking higher, a more restrictive economic environment is likely to occur.
The vaccine outlook
The market continues to react positively to any positive news flow on vaccines. This triggers sharp rotation away from tech back towards value and cyclicals, which highlights the challenge in constructing portfolios in this environment.
Overall there remains a reasonable degree of confidence on the potential for a vaccine around year-end. Still, we are mindful of a set of subsequent issues, such as how effectively can it be produced and distributed, frequency of dose, people’s willingness to take it and the potential for new variants of the virus to require new vaccines.
Economic outlook
The debate over suppression versus elimination continues to rage. There is a growing push-back against harder lockdowns given the degree of economic impact.
As this plays out, we are mindful that higher case numbers can impact confidence even if governments avoid further restrictions. Surveys suggest Americans have lost confidence in dining out and public entertainment in recent weeks. This is reflected in broader indicators of consumer sentiment, which were not so constructive in recent weeks.
The slowing pace of recovery is likely to influence the next round of US fiscal stimulus, set to be announced soon. Markets are suggesting an expectation that the government will continue underwriting the economy.
Elsewhere, Chinese data remains supportive, while there are positive economic signs emerging in Europe.
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and a strong track record leading Australian and European equities funds. He manages a number of our flagship funds along with one of the largest equities teams in Australia.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
https://www.pendalgroup.com/about/our-people/sales-team/
Some country-level factors are more important than others for Emerging Markets investors right now. Here are the latest insights from James Syme and Paul Wimborne (pictured), managers of our Global Emerging Markets Opportunities fund.
FOLLOWERS of our emerging markets investment process know we group our selected country-level market drivers into five broad groups.
But we recognise some of these are more important than others at particular times.
The current environment is one of these times, where pre-existing balance of payments strengths and weakness have outweighed the effects of monetary and liquidity stimulus applied across emerging markets.
When we look at the liquidity and monetary environment in emerging economies, we are focusing on the rate of increase of monetary aggregates and lending/credit in the economy.
We are then assessing how sustainable that is in light of inflationary pressures and the degree of leverage in the economy.
Generally, faster rates of money/credit creation are supportive of economic activity and asset prices. Typical beneficiaries are the more cyclical industries such as banks and non-bank financials, capital good and autos and real estate, cement and construction.
Similar to developed markets, the response to the COVID-19 crisis in emerging markets has involved an aggressive monetary policy response.
Rates of money-supply increase and bank-lending increase are up substantially in many countries. This might normally imply a positive outlook for risk assets in these markets. But these are exceptional times and we must act accordingly.
To give a sense of the scale of change, consider Brazil.
In the past 10 years policy interest rates in Brazil have averaged 9.6% and consumer price inflation 5.8%, giving an average real policy rate of 3.6%. At the end of June policy rates reached 2.25% (down from 14.25% in 2016), with consensus inflation expectations at 2.75% for the next 12 months.
Meanwhile, M2 money supply growth reached 23.2% in the year to May, compared to a 10-year average of 10.4%.
At first glance, this is a super-bullish environment for equity investors in Brazil.
However in extreme circumstances, as Keynes noted, monetary policy can amount to no more than pushing on a string.
These are extreme circumstances, and these monetary policy settings have failed to return Brazil to growth.
Although real rates are negative and money creation abundant, loan growth has reached a disappointing 9.2% year-on-year. (In the 2007 boom, when money supply also grew rapidly, bank lending grew 28.8%).
GDP growth in 2020 is predicted to be -6.5%, a forecast that continues to worsen. Similarly, 12-month forecast earnings for the Brazilian equity market (using the Bovespa index) are 36% lower than the start of 2020.
Similar pattern in other emerging markets
Brazil is an extreme case. But there is a similar pattern in other emerging markets where weak current accounts have meant high exposure to external sources of financing, which have proved difficult to support in the current crisis.
Mexico, South Africa, Turkey, Indonesia, the Philippines and India are among other markets with sustained current account deficits that have high levels of money creation but extremely weak economic outlooks.
Markets with generally strong current accounts have been able to maintain stronger levels of economic growth (and even stronger levels of banking lending growth) from a far less aggressive monetary response. These include China, Korea, Taiwan, Malaysia and Thailand.
Even in these unprecedented times, the big risk beta in emerging markets remains largely unchanged.
It remains our view that a diversified emerging market equities portfolio needs selected exposure to both groups of countries – even if one is doing better than the other.
While we have significant exposure to Korea and China, we also retain exposure to India, where corporate earnings expectations have held up better than other countries in the high-risk group.
We also have exposure to Mexico, which we believe is a high-quality market with significant opportunity in more defensive names.
COVID-19 is a shocking new development this year, but it is playing out across emerging markets very much along established lines that we have seen many times before.
James Syme and Paul Wimborne are senior fund managers and co-managers of Pendal’s Global Emerging Markets Opportunities fund.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
https://www.pendalgroup.com/about/our-people/sales-team/
As the COVID-19 pandemic continues to impact the global community, we remain focussed on taking proactive measures and precautions to ensure the health and safety of our employees, while maintaining our ability to service our clients and manage our business.
Our JOHCM and Pendal Australia staff have been working from home since mid-March 2020. Pendal Group has comprehensive Business Continuity Plans in place for all of our offices allowing us to continue to operate uninterrupted in these circumstances. Additionally we remain in regular dialogue with our core suppliers to ensure there is no disruption to services.
The Group has supported staff working from home through the use of technology and ongoing support programs. As restrictions are wound back and depending on the jurisdiction and government advice, employees where they can and are comfortable to do so are starting to return to the office, although this is a gradual and controlled process.
We continue to prioritise communication with our clients, keeping them informed through market updates and thoughtful insights on how to navigate through these uncertain times. I encourage you to visit the Market Insights, Education and Resources page on our website for the latest information.
These are unprecedented times for all of us and the situation remains fluid. We closely monitor the local and World Health Organisation updates and practices in local jurisdictions and where required we will take further sensible and informed action.
Our hearts and thoughts goes out to everyone who has been directly impacted and especially those families who have had to endure the loss of loved ones. We wish you and your family the best of health.
If you have any questions or concerns, please do not hesitate to reach out to your Pendal Group contact.
Emilio Gonzalez
Group Chief Executive Officer
Pendal’s head of equities Crispin Murray (pictured) outlines how the latest COVID-19 developments are impacting the outlook for Australian equities.
Quick take-outs
- Markets held up relatively well despite worse COVID-19 case and hospitalisation data last week.
- Australia’s probability of suppressing the virus has taken significant step back, impacting Real Estate Investment Trusts and domestic cyclicals
- Liquidity is still clearly prevalent as the NASDAQ hit new highs, driven by the FANGMAN stocks (Facebook, Amazon, Netflix, Google, Microsoft, Apple, Nvidia) and others. Tesla is up some 60% in two weeks. The Chinese market has also broken out – Ali Baba is up 21% in two weeks.
- Commodities are performing well, reflecting their real asset status
- The on-going disconnect between economy and markets continues. This is a distortion created by fiscal stimulus propping up spending and central bank actions underwriting government and corporate bonds – and effectively equities.
This accelerates structural trends supporting growth stocks in the market, with their higher weightings in indices, momentum created by passive funds, active funds forced into growth – and now day traders.
The key is to build portfolios that are able to hedge enough of this rotation. An important part of that is positioning right now in real assets, notably gold.
Australian focus is on Victoria
The big issue for investors is rationalising the fact that markets are still behaving relatively well despite negative headlines and case surges.
The focus is on Victoria – which represents 25% to 30% of national GDP – and assessing the risk of this surge affecting consumer confidence in other States.
It is right to be concerned about the near-term effect on the market. But we can see in Brazil and the US that markets can easily disconnect from poor COVID case data. These markets continue to rally as case numbers spike.
The number we are paying closest attention to right now is the positive test rate, which has continued to rise.
However, there is a ramp-up in the amount of testing in Victoria, which is critical in preventing new outbreaks from building. When this number rolls over it will be the first sign that things are improving.
US health system stability is a key issue
A key question in the US is the severity of strain on hospitals and the associated impact on death rates.
Hospitalisations are moving higher with a two-week lag. It’s becoming apparent that the south of US is effectively following the Swedish approach of “controlled spread”. It is unlikely we will see a significant reinstatement of lockdowns.
The US hospital system is still largely coping – Phoenix and Houston are the two worst-affected areas. Elective surgery has been suspended in Texas and some big city hospitals in Florida and California. Capacity is still available though.
Some of the market’s apparent ambivalence can be explained in favourable statistics (which will need to be watched carefully).
For example the US death rate for hospitalised patients has dropped from 20% to 10%. The rate peaked at 25% in New York and has since dropped to between 5% and 10%.
Treatment techniques have also changed, leading to fewer patients on ventilators – down from 25% to 15%. A slower rise in death rates may result from wider use of facemasks, more testing, improved awareness of safety protocols in nursing homes and younger patients.
Global growth signals
It’s clear the economic V bounce is slowing in the US. But other global growth signals are holding up reflecting China’s recovery (copper), strong housing (lumber prices) and ample liquidity.
In fact, liquidity is overwhelming other factors. The world’s two biggest economies, the US and China, have increased money supply 18% year-on-year. This drives financial assets and supports parts of the economy such as housing.
The Chinese market has broken through a five-year down-trend and US mortgage rates are making new lows as a result.
Bull case vs. bear case
The bull case narrative for August/September centres on these potential outcomes:
- Decelerating cases in US
- Death rates remaining lower
- Vaccine progress
- Large US fiscal stimulus
- Resumption of Fed balance sheet expansion
Meanwhile the bear case scenario looks like this:
- US economy goes into second effective shutdown as death rates follow hospitalisations
- Consumer confidence slumps
- US economy stalls as the market loses confidence in policy-makers’ ability to do enough
- Growth stock premiums begin to unwind
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and a strong track record leading Australian and European equities funds. He manages a number of our flagship funds along with one of the largest equities teams in Australia.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
https://www.pendalgroup.com/about/our-people/sales-team/
Pendal has announced a new appointment to its Bond, Income and Defensive Strategies (BIDS) team.
Philip Treharne joins the team as a Quantitative Analyst from July 20.
Philip is a highly skilled quantitative researcher and investment analyst with extensive experience in portfolio management, research, modeling and trading.
In a previous role as a senior investment analyst at a systematic investment fund Philip specialised in strategy development and portfolio risk management.
Philip holds a PhD in Applied Maths from Cambridge University in England.
At Pendal Philip will reunite with another recent BIDS team appointment, volatility analyst Thomas Ciszewski.
The pair, who worked together at Deutsche Bank and SouthPeak Investment, will collaborate on key initiatives to ensure Pendal’s BIDS products are optimised for the new economic and market environment.
These appointments mean the BIDS team now operates with a dedicated equity volatility skillset.
Philip will report to Vimal Gor, Head of Pendal’s Bond, Income and Defensive Strategies team.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
Which fiscal factors will impact investors in the months ahead? Here’s a quick snapshot from portfolio manager Tim Hext (pictured) of Pendal’s Bond, Income and Defensive Strategies team.
MELBOURNE’s second virus shut-down was the story of this week — and will no doubt cause slower-than-expected growth this quarter.
An increase in cases was expected as economies re-opened, but the speed with which this wave hit parts of the Victorian capital was a surprise.
Nevertheless, unlike the massive initial shock in March, markets barely skipped a beat.
Equities saw some moves within sectors, especially those exposed to the Melbourne economy. But overall equity and bond markets were almost unchanged.
The government will again play a key role in buffering the impact.
We have written a lot in recent months about the transfer of economic control from monetary to fiscal policy. Economists have turned their gaze from Martin Place in Sydney to Langton Crescent in Canberra.
A number of key markers will be laid in the months ahead. JobKeeper and JobSeeker are due to end in late September. We expect more colour in the weeks ahead on how they may be extended or adjusted.
Then a budget is due in October. The need to encourage investment should see more aggressive schemes and tax breaks introduced.
The big fiscal question is whether tax changes will be brought forward. The government has two big tax cuts scheduled for July 2022. The 19c tax cap is due to be raised from $37,000 to $45,000 and the 32.5c cap from $90,000 to $120,000.
This would bring significant tax relief to most taxpayers. Given the current environment these could be brought forward.
Another, more controversial tax cut is due in July 2023. This would establish a single tax rate of 30c for $45,000 to $200,000 — a massive cut for middle and higher income earners. Whether the Senate agrees to bring this one forward may be more controversial because it favours higher income earners.
Tax cuts would put more money in taxpayers’ pockets. But would they have the confidence to spend it rather than save it?
As always, lower income earners have a much higher propensity to spend — so it could be argued keeping JobSeeker at a higher level beyond September would be more help.
Other ways of injecting activity into the economy may be more difficult, short of handing out coupons rather than cash. Infrastructure is already operating at capacity and housing will not be helped by the static population.
Either way fiscal policy will be left doing the heavy lifting.
Graphic: Bloomberg
In regard to bonds, we continue to watch the massive excess capacity gap and attempts to close it.
The RBA expects GDP output to take until mid-2022 to return to pre-crisis levels — but even that looks optimistic.
Inflation will see the first negative annual print since the 1960s in late July. It will bounce back, but when combined with wage freezes, low population growth and sluggish housing, the medium-term outlook is not promising.
We remain comfortable that bonds will continue to do their defensive job in portfolios.
Tim Hext is a portfolio manager with Pendal’s Bond, Income and Defensive Strategies team.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about our investment capabilities:
https://www.pendalgroup.com/about/investment-capabilities
Contact a Pendal key account manager:
Pendal’s head of equities Crispin Murray (pictured) outlines how the US experience with COVID-19 and the latest vaccine developments are impacting the outlook for Australian equities.
Quick take-outs
- Despite negative sentiment from increased COVID-19 cases, equity markets continued to rise
- Economic data has been supportive, but there are early signs of a slowing in the V bounce
- We’ve seen some positive vaccine news flow
- Locally it’s an important week for sentiment with the risk that stocks leveraged to economic recovery could be impacted by the Victorian lockdown
As bad as it feels with the negative news flow around rising COVID cases in Australia and parts of the US, the market hasn’t responded as some may have expected — and has continued to grind higher. We are now at a juncture where:
- We could see a more significant leg down if case load data continues to worsen;
- But if evidence emerges that virus management has improved, we could get squeezed higher — bearing in mind that overall market positioning has turned more defensive.
Our portfolios are positioned defensively — but not aggressively so. We have stated several times in this weekly Australian equities note that a balanced portfolio with a good mix of recession insurance and recovery plays is very important in this unpredictable and fast-moving environment.
US Economic data surprises to the upside — but there’s evidence of the V stalling and no improvement in US case numbers
Published economic data continues to be positive.
Jobs data is strong, which has supported the market. On the employment front “Hours Worked” (+8.3%) and “Household Employment” (+6.6%) surprised to the upside. Similarly, the PMI diffusion indices are heading in the right direction indicating a stronger growth momentum than many anticipated.
We are now looking at an 8% drop in US Q2 GDP versus an 11% to 12% drop — as most estimates suggested we were facing a few months back. Still a lot to make up, but significantly better. Clearly interest rates will continue to be supportive.
However there is still some evidence that things are slowing. Markets must gauge not only the economic effect of the lockdowns, but a perception of risk that is deterring consumer spending.
A recent University of Chicago study concluded that sentiment — rather than the lockdowns themselves — are the biggest headwind. We know that only around half of the stimulus has been spent so far. This is something to keep watching in the US and Australia.
There are signs of this slowdown coming through in the last week in the worst-affected states of Florida, Texas, California and Arizona — which make up about a quarter of the US population. Restaurant bookings in the Open Table app tapered off quite sharply last week after a post-lock-down recovery.
Cases in the US continue to rise and hospitalisations are increasing — though they remain below the previous peak and deaths are still low. In Florida overall numbers are worse, though there is less strain on hospitals. In contrast, Phoenix and Houston are close to ICU capacity. We are now seeing “surge plans” implemented in many of these cities such as LA, including the deferral of elective surgery.
The data shows some smaller US states have seen improvements — but not the major states such as Florida, Texas and California.
Vaccine news flow is positive
One positive consequence of rising cases is the acceleration of some Phase 3 trials. There is some talk of the first batches being available before year-end.
The three main trials are:
- Moderna
- Aztrazeneca (in partnership with the University of Oxford)
- Pfizer (four variants of a vaccine in development)
Pfizer has just released results of Phase 2 trials on one of its vaccines, which indicate a) the drug is safe to use and b) it is triggering an immune response. This means it can progress to the final Phase 3 trial, which will be 30,000 patients. The rate of new cases actually helps determine the efficacy of the vaccines.
In the best-case scenario, the drug will be approved by October. Pfizer estimates it could produce 1.2 billion doses in 2021, which would equate to 600 million treatments. This shows the problem likely will not be solved by a single vaccine. To meet demand we will likely need several vaccines to be approved.