
The Australian Sustainable Finance Intiative – helping steer the Australian economy through a critical decade
A sustainable and resilient economy – one that prioritises human well-being, social equity and environmental protection – is the foundation for ensuring Australia’s prosperity throughout the 21st century. That’s why the leaders and senior executives of Australia’s major banks, superannuation funds, insurance companies, financial sector peak bodies, civil society and academia are coming together to set out a roadmap for realigning the finance sector to support greater social, environmental and economic outcomes for the country.
The Australian Sustainable Finance Initiative, launched on 27 March, is an unprecedented collaboration to help shape an Australian economy that prioritises human wellbeing, social equity and environmental protection, while underpinning financial system stability, in what it says is a ‘critical decade’ ahead.
Pendal is proud to represent the investment management industry on this critical initiative. Over the past decade we have seen growth in a number of groups individually advocating for greater cohesion with business, financial, social and environmental imperatives. Bringing the wider financial industry together through the Australian Sustainable Finance Initiative means we will now have a truly collective approach to developing a comprehensive roadmap that will address the many present and future challenges.
The Roadmap development process will be overseen by a Steering Committee consisting of senior financial services, academic and civil society representatives. Richard Brandweiner, CEO Pendal Australia, has been appointed to the Steering Committee. Richard is looking forward to contributing to this important initiative, drawing upon his deep experience in the fields of impact investing and responsible investment practices.
Richard is a passionate advocate for responsible investment and delivering societal outcomes. He shares his expertise through current appointments on the NSW Social Impact Investment Expert Advisory Group and as Vice-Chair of the Australian Advisory Board on Impact Investing.
Find out more about the Australian Sustainable Finance Initiative.
In this second of our two-parts series, Samir Mehta looks at the oligopolistic paints industry as an example of disruption risk and continual reinvestment to support future growth.
In Asia, there is one difference when compared to developed markets. Good long-term growth opportunities for several companies are still robust, albeit frequently interrupted by macroeconomic challenges. Take India as a case in point. After disruptions due to demonetisation and the introduction of a GST, we now confront geopolitical tensions. I have no opinion of how this situation will resolve, but suffice to say that in the past, saner heads have prevailed. Results for the quarter ending December 2018 are almost through. Companies that managed the disruption of GST and demonetisation well were rewarded handsomely by the market; P/E multiples for the better-managed firms remain high.
Take Asian Paints (AP) for example. On the face of it, the stock has always appeared expensive on both an earnings as well as price-to-sales multiples. In my opinion, there is a logical reason for this: the structure of the paint industry. The world over, the paints industry is an oligopoly. Even in America it has yet to be disrupted by the internet giants. In India, too, the industry is a cosy oligopoly, with AP the clear market leader. As of March 2018, total industry revenues were estimated at approximately Rs500bn (US$7bn), of which AP reported revenues of Rs166bn (US$2.3bn). The unorganised sector (small mum-and-dad chemical plants that have low-end paints with no brand resonance and poor distribution) still account for 30-35% of total sales. That share is likely to fall over the next decade, in my view. This will partly be driven by trends of rising incomes and aspirations of customers who gravitate to branded offerings, but moreso due to the introduction of the GST in 2017 and lowering the GST slab to 18% compared with 28% in prior years.
The world over, the paints industry is an oligopoly. Even in America it has yet to be disrupted by the internet giants.
To illustrate the hold the four big companies AP (52,000 dealers), Berger (23,000), Kansai Nerolac (21,000) and Akzo (14,000) have on the market, it is instructive to look at the progress of a couple of firms that entered the industry early this century. Indigo Paints started in 2000 and Kamdhenu Paints opened in 2008. It is difficult to get exact data of these unlisted firms but, from public data sources, Indigo has approximately 12,000 dealers while Kamdhenu has 4,000. After 18 years in the business, sales for Indigo are approximately Rs5-6bn pa. To put that in perspective, the top four firms collectively spent Rs13bn in advertising and promotions in 2018.
The cost of painting an apartment varies from 1-3% of the cost of purchasing the apartment. Paints are integral to decoration and aesthetics of the house. There is an umbilical link to the health of the real estate industry. In the past 7-8 years, home prices in India have, on average, remained flattish. A big bull market in property prices, which began in 2001/2, created an overhang of supply. Even in tough years, paint volumes have averaged growth of 6-8% pa. Fortunately in the past couple of years, the Indian government has refocused its efforts on the housing sector. Providing subsidised rates of interest for affordable housing, changing GST rates for finished and unfinished homes and recognising that building and construction industries can provide ample employment opportunities. The industry is working with the National Skills Development Corporation to impart skills in its effort to train painters and increase engagement with architects. Current penetration levels of paints in India is low. Housing demand in India is likely to grow steadily as income levels grow and joint families splinter over time. As the industry leader, AP is using its cash flows to create capacity well in advance of anticipated demand. In the past five years, AP has invested Rs46bn in capex compared with just Rs20bn in the five years prior. Its A&P spend remains around 4% of sales, even on a much higher sales base.
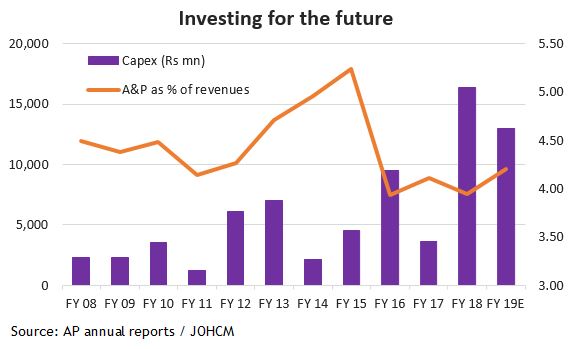
“My view on the persistence of industry growth and confidence in Asian Paint’s industry positioning and execution abilities overcomes the concerns that the company has always appeared expensive on both an earnings as well as price-to-sales multiples.” Samir Mehta, Senior Portfolio Manager
Given this dynamic, my view on the persistence of industry growth and confidence in AP’s industry positioning and execution abilities overcome the concerns about valuation. Unlike Heinz, this company’s focus remains on the growth potential that lies ahead in the decades to come. It has invested in distribution, brand and capacity and is continually increasing its lead over competitors. The free cash flow for the firm in the next five years could possible double (or more) if demand for property starts to pick up in India. Even when the economy was slowing and inflation was high, AP demonstrated it had pricing power. It continues to toggle between retaining margins and reinvesting in the business. Overall, I do not foresee a fate similar to Heinz. On the contrary, AP’s approach to business might be one that Heinz is forced to veer back towards.

Read more about the Pendal Asian Share Fund

Fund Manager commentary for the month ended 28 February 2019 covering market reviews, Pendal fund performance and our outlook for the period ahead.
Access the monthly commentary here.

Our investment process is designed to exploit what we believe is a market inefficiency that results from the structure of the emerging market equity investment community. Specifically, we believe the dominance of bottom-up, company-focused investors in the space creates an effect where markets alternatively ignore, and then over-react to, top-down developments. That creates shorter-term over – and under – valuations that are powerful opportunities for top-down focused active investors.
In this instance, us.
The sell-off and selective recovery in emerging markets in 2018 has created, we believe, multiple instances of this that we are actively rotating capital into. One of those instances is Dubai in the United Arab Emirates (UAE). The UAE is a federation of seven Emirates, with the two largest, Abu Dhabi and Dubai, dominant. The two are very different in nature: Abu Dhabi, backed by its hydrocarbon exports, has a conservatively managed, twin-surplus economy, with an expensive and low-beta equity market; Dubai, lacking hydrocarbons, relies on trade, tourism and investment, which makes the equity market high-beta, with close links to the local real estate market.
Dubai has had a series of real estate booms and busts in the last 20 years and is undergoing a slowdown at present. Through its currency peg, the UAE effectively imports US monetary policy, which has coincided with oversupply of development properties to push both real estate prices and related stocks down significantly. Even with a more benign US monetary outlook, the residential property market may take some time to recover. However, property companies exposed to the tourist trade through retail, entertainment and hospitality assets have similarly de-rated.
Emaar Malls
Dubai-listed Emaar Malls is a unique retail property operator, with one of the highest quality portfolios in the world. The company is the owner (not leaseholder) of a variety of retail properties in Dubai, most notably the Dubai Mall. The Dubai Mall is the largest and most-visited retail and entertainment destination in the world and is located right in the centre of downtown Dubai. Emaar Malls also operates four other large malls and some other smaller retail properties in the Emirate. In 2018, Emaar Malls’ 6.7 million (!) square feet of gross leasable area attracted 136 million (!!) visitors, a 5% increase on 2017, which in turn drove an 8% increase in EBITDA and a 7% increase in net earnings. Meanwhile, despite the super high-quality nature of its asset portfolio, Emaar Malls is surprisingly under-levered, with a net debt/EBITDA of 1.4x (peers are typically levered anywhere from 3x to 12x).
So, have investors over-reacted to the slowdown in the Dubai economy? In our view, absolutely. At the time of writing, Emaar Malls is on an operating yield of 12.5%, (compared to a typical level for global peers of 5-9%). From another viewpoint, Emaar Malls had, at 31 December 2017, independently-valued investment properties worth AED 54.0 billion, new assets coming into operation in 2018 and net debt at 30 September 2018 of AED4.0 billion, but a market capitalisation at the time of writing of only AED 22.8 billion. It is our strongly held opinion that there is no sense to these valuations, and we have accordingly been building a portfolio position in Emaar Malls.
Emaar Properties
Similarly, Emaar Malls’ parent, Emaar Properties, has also sold off to an extent that seems irrational. As well as its stake in Emaar Malls, the other key subsidiaries are also listed, allowing a valuation to be calculated for Emaar Properties’ core hospitality and entertainment assets. At points in recent weeks, the implied value of the core assets has been negative.
With these two holdings we acquire both a highly defensive and a more cyclical holding, both at valuations that imply company-level distress or national crisis. We feel there is nothing happening in Dubai beyond a downturn in the property market, and have a high degree of confidence that both these investments will, in time, prove to be highly profitable as the emotions of the Dubai-facing investor community inevitably swing from excessively negative to overly positive.
No use buying the best house in a bad neighborhood
Be a part of the world’s fastest growing economies

The 8th of March each year marks International Women’s Day and today we take the opportunity to delve into a growing segment of the Responsible Investing market – gender equality bonds. With the teams at Regnan and Pendal coming together following Pendal taking full ownership of Regnan, we are pleased to provide a collective review of this emerging area of the bond market.
This article provides an update on the gender bonds market and considers what the next evolution might hope to achieve in advancing women’s equality and empowerment.
View the article
Pickle: any brine, vinegar or spicy solution used to marinate food; synonym – predicament: a condition or situation that is difficult, unpleasant, embarrassing or comical.
The annual results of Kraft Heinz and the commentary on what has happened to its business in the past couple of years has several lessons for those who invest in quality businesses.
With the imprimatur of Mr Buffet, the deal to combine Heinz and Kraft was a landmark transaction. An almost ruthless approach to cutting costs by the new owners was the new mantra for managing businesses with moats and steady revenues. In February 2017, it even made a hostile bid to acquire Unilever; today Kraft’s market cap is less than Hindustan Lever, its Indian subsidiary.
So what went wrong?
– To start with the easy part: leverage. It is one of the defining moves employed by private equity firms – financial engineering (in the garb of attaining the ‘right’ debt:equity mix). This led a stable business to take on significantly more debt. In itself that might not be wrong, but when a business faces challenging conditions, management teams face mounting pressure to remain within debt covenants to the detriment of investments in the future.
– Second, was the zero-based budgeting approach to cost cutting. Popular at one time amongst business consultants, it drove management by the mantra of ‘why should you spend?’ Perhaps that question is justifiable for administrative costs, but if applied to all costs this might defeat the purpose of managing and rejuvenating a steady cash-generative business.
– Finally, disruption in business conditions. The world over, retail chains were the first to feel the impact of online disruption; food and staple brands are increasingly feeling the effects now. The changing tastes of millennials, niche new brands that can scale thanks to influencer endorsement marketing strategies and help from online platforms for nationwide delivery are challenging incumbents.
It is critically important to reinvest continually into the business to maintain existing brands and create new ones. That ultimately is the crux of the ‘moat’ of quality branded businesses. In Kraft’s case, perhaps the high debt and focus on cost cutting left management with little room to focus on what should have been the core capital allocation decision.
In next week’s edition Samir compares the Kraft Heinz experience with India’s paint industry, to show the importance of balancing cost cutting initiatives and investing for the future.
Read more about the Pendal Asian Share Fund
Vimal Gor, Pendal’s Head of Bond, Income & Defensive Strategies, says there’s just one fundamental driver of all asset prices: liquidity. In this exclusive interview with Livewire Markets, Vimal discusses:
– liquidity and the implications of a tightening credit cycle
– why the US / China relationship has become too much of a focus
– a slowing global growth outlook and how this is feeding into his bearish outlook
– why the world simply can’t handle higher interest rates
– the asset class most likely to deliver a positive return in 2019
– the asset class most likely to deliver a poor return in 2019.
Watch the full interview
Read more about the team and our capabilities
“They don’t ring a bell at the top of the market…they don’t ring a bell at the bottom either”
James Syme, Senior Portfolio Manager
2018 was a difficult year for emerging markets, with a number of country-specific challenges leading to weakness in both equities and currencies.
In this quarterly update, James Syme reviews the Strategy’s performance over the past quarter and provides:
– a perspective on country-specific impacts from US economic policies;
– the underlying dynamics in China beyond the trade narrative; and
– the signs to look for ahead of a upturn in emerging markets
View the video here.
Further reading:
Be a part of the world’s fastest growing economies
Fund Manager commentary for the month ended 31 January 2019 covering market reviews, Pendal fund performance and our outlook for the period ahead.
Access the monthly commentary here.
“As US monetary policy moves through the stages of fewer hikes-pause-cuts, the prospects for economic growth and market recovery in emerging markets improve. We expect strong returns from some of these markets in 2019, and have seen a strong start to the year in some of them.” James Syme, Senior Portfolio Manager, JOHCM
Federal Reserve Board Chairman Jerome Powell
There are two powerful sources of qualitative information that can help investors in emerging markets assess how US monetary policy (which is one of the key global drivers of EM equity returns) might evolve. The first of these two is the quarterly results and outlook commentary from globally-facing US companies. These comments give an immediate view of the state of demand in various economies around the world, and how those demand conditions might be feeding back into the US economy (and, in turn, how US monetary policy might evolve). The second is from speeches and comments from the leadership of the Federal Reserve, particularly where those comments reference emerging markets.
Corporate reporting
It has been our view for over a year that the G7 policy-driven slowdown in emerging economies would feed back into the developed world through weaker orders and revenues for EM-facing companies, until either weakness in financial markets and/or weakness in economic statistics caused a policy re-think in G7 capitals. Over the last twenty years, sustained weakness in emerging market currencies has led, or been coincident with, a fall in US and G7 activity measures, such as industrial production and manufacturing PMI. We expect the EM sell-off in 2018 will show up in developed market corporate and economic data in 2019.
Looking at some of the company results published so far in 2019, there are certainly signs of weakness, with China very much a focus of it. This trend includes Apple (“while we anticipated some challenges in key emerging markets, we did not foresee the magnitude of the economic deceleration, particularly in Greater China. In fact, most of our revenue shortfall to our guidance, and over 100 percent of our year-over-year worldwide revenue decline, occurred in Greater China”), Caterpillar (“Construction activities remained at low levels in Latin America… weakness in the Middle East… sales in Asia/Pacific declined due to lower demand in China”), Nvidia (“deteriorating macroeconomic conditions, particularly in China”) and Disney, where a trend of very strong results from parks and resorts was broken by “lower operating income at Shanghai Disney Resort… primarily due to lower attendance”).
Fed commentary
We can also see the Federal Reserve paying increasing attention to emerging markets. Notably, Chairman Jerome Powell held the view in May 2018 that “the normalization of monetary policies in advanced economies should continue to prove manageable for EMEs”, but by September 2018 was claiming that “when our economy is strong and we’re raising rates, that puts upward pressure around the world and can affect countries, particularly countries that have external dollar borrowing… The performance of the emerging market economies really matters to us in carrying out our domestic mandate”, which pre-figured the move to the Fed being “patient” with rate hikes.
“The performance of the emerging market economies really matters to us in carrying out our domestic mandate.” Fed Chairman Jerome Powell
This growing evidence of weakness in the cyclical part of EM does not create an automatically bearish outlook for the asset class though. One of the key sensitivities in the asset class is to bond yields and the strength of the US dollar; markets more exposed to this tend to be the more domestically-driven, current account deficit markets such as India, Indonesia, Turkey and most of Latin America. As US monetary policy moves through the stages of fewer hikes-pause-cuts, the prospects for economic growth and market recovery in these markets improve. We expect strong returns from some of these markets in 2019, and have seen a strong start to the year in some of them. In addition, the more cyclical end of EM (predominantly Asian exporters) does contain some markets that are clearly already pricing in a sharp slowdown – we would highlight the strong performance (+21.7% at the time of writing) of Samsung Electronics since its “disappointing” results on 8 January as an example of a stock already pricing in the worst. We remain substantially overweight India and Korea and continue to rotate the portfolio into more domestically-driven markets that can benefit from the Fed’s new-found caution.