Mainstream Online Web Portal
LoginInvestors can view their accounts online via a secure web portal. After registering, you can access your account balances, periodical statements, tax statements, transaction histories and distribution statements / details.
Advisers will also have access to view their clients’ accounts online via the secure web portal.

Brenton Saunders: Why ASX mid-caps are becoming fertile ground for M&A
Takeover interest in ASX mid-caps can help highlight undervalued companies. Pendal portfolio manager BRENTON SAUNDERS explains what is attracting buyers
- Cyclical pressure creating valuation opportunities
- M&A activity can validate strategic value
- Find out more about the Pendal MidCap fund
CORPORATE activity is rising among Australian mid-caps — a segment Pendal portfolio manager Brenton Saunders describes as a “sweet spot” for larger companies seeking attractive opportunities.
“One of the reasons mid-caps do well, and better than some of the other sectors of the market over time, is just because there’s elevated corporate activity in the space,” says Saunders.
“These are companies that aren’t super big, they’re typically still growing quite quickly, and often they’re fairly progressive and entrepreneurial at that stage of their development.”
Three factors appear to be driving mergers and acquisitions (M&A) interest in mid-caps: cyclical pressure creating valuation opportunities, operational underperformance attracting private capital, and structural or regulatory change increasing strategic value.
Cyclical pressure, underlying value
Cyclical industrials with durable market positions but temporarily depressed earnings or valuations are attracting potential buyers.
Saunders points to Reliance Worldwide as an example of how housing market weakness and cost inflation can weigh on a high-quality, cash-generative business.
Reliance sells plumbing materials and retail items in the US, predominantly through major hardware retailers such as Home Depot and Lowe’s Home Improvement.
Global investment firm Brookfield made several offers for Reliance, which has now accepted a bid valuing it at $4.1 billion.
“Reliance had been cyclically battling with the fact that the US housing market has been experiencing very high interest rates. The company had also been battling with fairly high procurement and materials inflation,” explains Saunders.
“It had earnings downgrades over the past couple of years for mostly those top-down reasons and less to do with the company specifically.
“But that got it to a point where the dividend yield on top of the share buyback that they’ve been doing just got more and more attractive. In our view, it is still a very high-quality and cash-generative company.”
Hear more on the midcap space from Brenton:
Private capital eyes operational upside
Cleanaway illustrates how operational challenges can attract private capital.
The waste management company has agreed to a $9.3 billion takeover by Swedish private equity firm EQT. The offer represents a 34.5 per cent premium to Cleanaway’s three-month volume-weighted average share price to 12 August 2026.
Saunders says Cleanaway’s subdued valuation before the offer largely reflected scope to improve operational execution.
“Consensus earnings estimates for the company just kept getting marked down weighing on the share price,” he says.
“The downgrade cycle that this company found itself in was more self-inflicted than it was necessarily a function of the macro overlay or anything else.”
Pendal MidCap Fund holds positions in both Reliance and Cleanaway.
Regulatory change unlocks strategic value
Japanese financial services firm Daiichi Life’s $7.8 billion bid for annuities provider Challenger highlights a third driver: regulatory changes that make Australia more attractive to international buyers.
From mid-2026, the Australian Prudential Regulation Authority (APRA) introduced new capital requirements for decumulation products, such as annuities.
Find out about
Pendal MidCap Fund
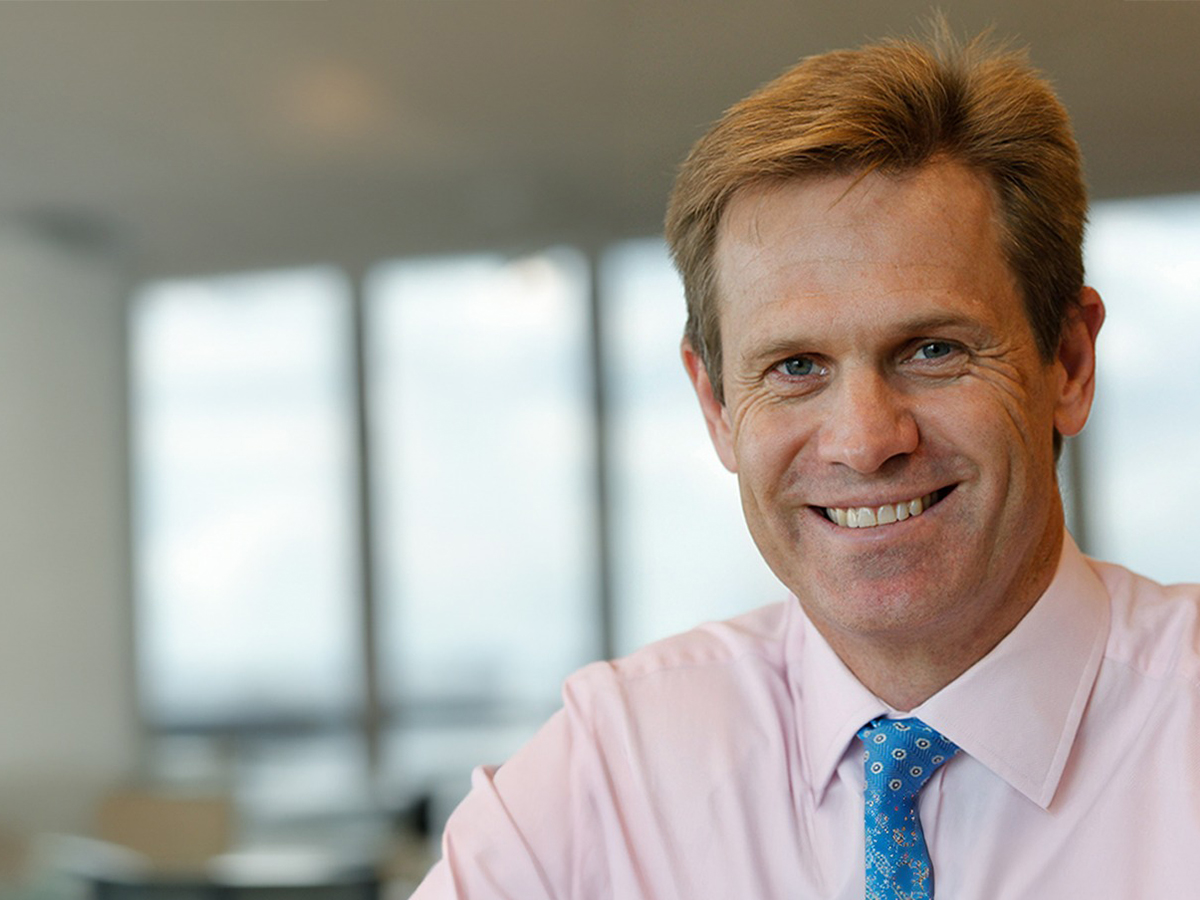
Brenton Saunders, Portfolio Manager
The changes aimed to make annuities less capital-intensive to write, potentially attracting new providers to a market with limited participants.
An annuity is a contract with an insurance company that provides a guaranteed income stream, either immediately or in the future, and is often used in retirement planning.
Challenger (ASX:CGF) is one of the few Australian investment management companies offering annuities.
Once the changes were made clear, Saunders and Pendal analyst Graeme Petroni predicted Challenger would likely attract the attention of a larger international player.
Pendal MidCap Fund also holds a position in Challenger.
“Australia always had a different and more onerous version of capital requirements for annuity companies, and it created some inefficiencies around the amount of capital and assets that these companies had to carry against their annuity liabilities,” explains Saunders.
“This made them very susceptible to having to sell the most volatile parts of their investment portfolio at the worst times.
“The capital requirements have effectively been aligned with companies globally, which means that international companies are now much more inclined to look at this market as a target market for annuities – and the big players in that are typically the Japanese and the US companies.”
Together, these examples highlight how active investors can identify strategic value in mid-cap companies before it is reflected in share prices.
About Brenton Saunders and Pendal MidCap Fund
Brenton is a portfolio manager with Pendal’s Australian equities team. He manages Pendal MidCap Fund, drawing on more than 25 years of expertise. He is a member of the CFA Institute.
Pendal MidCap Fund features 40-60 Australian midcap shares. The fund leverages insights and experience gained from Pendal’s access to senior executives and directors at ASX-listed companies. Pendal operates one of Australia’s biggest Aussie equities teams under the experienced leadership of Crispin Murray.
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
This information has been prepared by Pendal Fund Services Limited (PFSL) ABN 13 161 249 332, AFSL No 431426.
PFSL is the responsible entity and issuer of units in Pendal Midcap Fund (Fund) ARSN: 130 466 581. A product disclosure statement (PDS) is available for the Fund and can be obtained by calling 1300 346 821 or visiting www.pendalgroup.com. The Target Market Determination (TMD) for the Fund is available at www.pendalgroup.com/ddo. You should obtain and consider the PDS and the TMD before deciding whether to acquire, continue to hold or dispose of units in the Fund.
An investment in the Fund or any of the funds referred to in this web page is subject to investment risk, including possible delays in repayment of withdrawal proceeds and loss of income and principal invested.
This information is for general purposes only, should not be considered as a comprehensive statement on any matter and should not be relied upon as such. It has been prepared without taking into account any recipient’s personal objectives, financial situation or needs. Because of this, recipients should, before acting on this information, consider its appropriateness having regard to their individual objectives, financial situation and needs. This information is not to be regarded as a securities recommendation.
The information may contain material provided by third parties, is given in good faith and has been derived from sources believed to be accurate as at its issue date. While such material is published with necessary permission, and while all reasonable care has been taken to ensure that the information is complete and correct, to the maximum extent permitted by law neither PFSL nor any company in the Pendal group accepts any responsibility or liability for the accuracy or completeness of this information.
Performance figures are calculated in accordance with the Financial Services Council (FSC) standards. Performance data (post-fee) assumes reinvestment of distributions and is calculated using exit prices, net of management costs. Performance data (pre-fee) is calculated by adding back management costs to the post-fee performance. Past performance is not a reliable indicator of future performance.
Any projections are predictive only and should not be relied upon when making an investment decision or recommendation. Whilst we have used every effort to ensure that the assumptions on which the projections are based are reasonable, the projections may be based on incorrect assumptions or may not take into account known or unknown risks and uncertainties. The actual results may differ materially from these projections.
For more information, please call Customer Relations on 1300 346 821 8am to 6pm (Sydney time) or visit our website www.pendalgroup.com