
How to find income without the yield traps | Why country dynamics matter in emerging markets | How investors can find ‘Yield Royalty’ in Australia
Unemployment is rising faster than the Reserve Bank expected. Pendal’s head of government bond strategies TIM HEXT explains what this means for rate cuts and bond investors
- Unemployment is rising faster than RBA expected
- Investors should look to lock in term rates
- Find out about Pendal Government Bond Fund
- Browse Pendal’s fixed interest funds
THE latest rise in unemployment to 4.9% (4.8% trend), along with the loss of 43,500 jobs, came as a surprise to most economists.
None more so than those employed at the Reserve Bank, who were not expecting this kind of number before the end of next year.
The RBA had been anticipating “a stable near-term outlook for labour demand” according to the minutes of its board meeting earlier this month.
Perhaps the three rate hike dissenters on the RBA board were reading the consistent headlines of layoffs rather than listening to the Reserve Bank staff.
Within the data there are some interesting observations.
Firstly, the unemployment rate rose despite a lower participation rate (66.6% from 66.8%), which is unusual and highlights the scale of job losses.
Secondly, the job losses in the last two months have largely been part time, meaning the underemployment rate is rising slower than the unemployment rate.
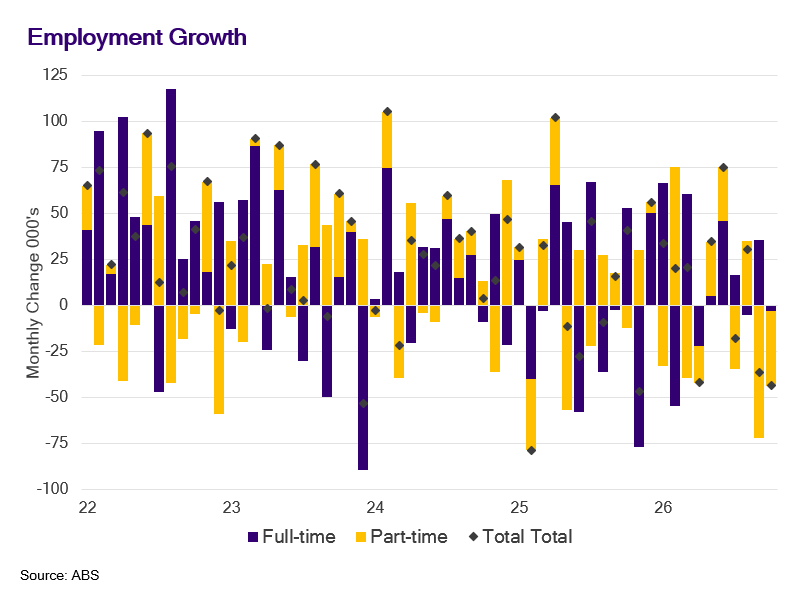
Thirdly, hours worked fell by 0.2% and are only 0.7% higher than a year ago, despite 1.5% population growth.
The one bright spot is that GDP is holding up better than jobs, indicating productivity gains.
The flipside of this is that maybe we are beginning to see early signs of everyone’s fears – AI and other technology outsourcing might see improving productivity but largely via a lot less workers.
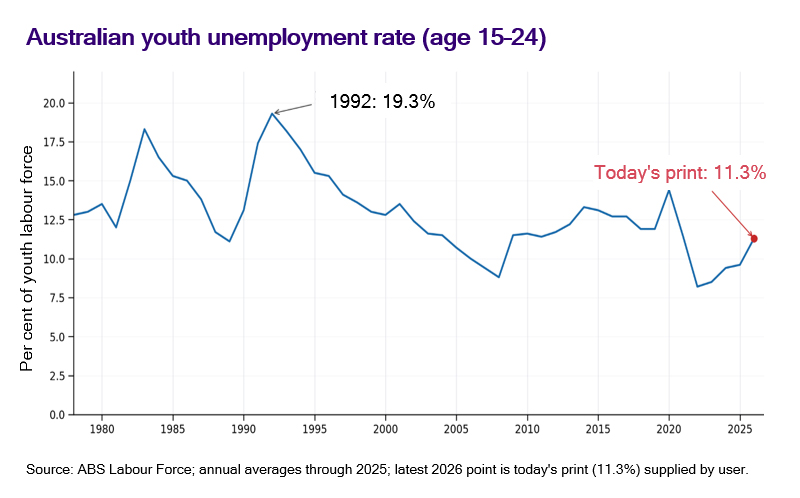
Finally, of special concern is the rise in youth unemployment. According to the Australian Bureau of Statistics (ABS), in the post COVID period youth unemployment averaged 9.2%.
It is now 11.3% and rising. The long-term average over the last 50 years is 13%, so its disappointing to be back near there.
Implications for monetary policy
Labour force data has been notorious for month-by-month volatility, but the trend and momentum here is clear.
The Reserve Bank is achieving much earlier than expected what it set out to do with the five rate hikes this year – freeing up capacity to counter inflation. Unemployment began the year at 4.1%.
I won’t begin a tirade around sacrificing jobs rather than reining in government spending to tackle inflation, but the trouble with starting a fire is it can get out of control.
The virtuous employment circle since COVID is now fast becoming a vicious circle. Job losses reduce confidence that reduces consumer spending that in turn leads to further job losses. All with rate hikes fuelling the fire.
Markets now have a full rate cut priced for August next year, and one and almost two cuts by the end of 2027, removing the two recent rate hikes.
If rate cuts begin next year the cycle will be deeper than just two cuts.The Reserve Bank will be cautious until inflation starts turning.
Q4 this year will remain high but by mid next year it is likely trimmed mean inflation will be around 0.7% per quarter from current levels nearer 1%.
Investment implications
Although bonds are now almost 0.5% off the yield highs, 10-year bonds are still around 5%. Investors should continue to look for opportunities to lock in term rates as the cycle begins to turn.
While the RBA may be cautious about rate cuts, if we begin to see signs of a recession caution will disappear quickly as the RBA focuses on its dual mandate – price stability and full employment.
Floating rate notes and term deposits will see returns fall sharply with cash rates. Fixed rate bonds will finally start to perform their role as insurance.
Find out about
Pendal Government Bond Fund
Tim Hext, Head of Government Bond Strategies
If you’d like to hear more about how Pendal’s Income & Fixed Interest team is positioning for this environment, please contact us through our accounts team
About Tim Hext and Pendal’s Income & Fixed Interest boutique
Tim Hext is a Pendal portfolio manager and head of government bond strategies in our Income and Fixed Interest team.
Tim has extensive experience in banking, financial markets and funding including senior positions with NSW Treasury Corporation (TCorp), Westpac Treasury, Commonwealth Bank of Australia, Deutsche Bank, Bain & Co and Swiss Bank Corporation.
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.
Find out more about Pendal’s fixed interest strategies here
About Pendal
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
In 2023, Pendal became part of Perpetual Limited (ASX:PPT), bringing together two of Australia’s most respected active asset management brands to create a global leader in multi-boutique asset management with autonomous, world-class investment capabilities and a growing leadership position in ESG.
After a tough stretch for small caps, a rotation is changing which sectors lead the market. Pendal investment analyst DAMIEN DIAMANT explains where investors can find opportunities now
- Investors rotating from crowded into unloved sectors
- Small caps look attractive versus large caps
- Find out about the Pendal Smaller Companies Fund
THE current rotation underway on the ASX is seeing investors exit the overcrowded sectors and begin to shift into stocks that had previously been out of favour.
“A lot of capital is exiting these crowded sectors and heading into some of the unloved sectors,” says Diamant.
Through October and into November, investors sold AI-linked stocks, contractors, defence and resources.
They moved into consumer cyclicals, financials, REITs and healthcare. Retailers Premier Investments (+17 per cent) and Lovisa (+16 per cent) led the way, along with market-sensitive financials such as Netwealth and Pinnacle.[1]
Many of these stocks were “at the bottom end of the performance charts a year ago”, notes Diamant.
REITs and healthcare back in favour for small cap investors
The market had largely priced in the RBA’s Melbourne Cup Day hike, and investors are now betting that rates have peaked.
Read: Cup Day hike, split field: Is the RBA done?
That’s helping rate-sensitive sectors recover. Charter Hall rose 11 per cent, while healthcare has also had a bit of a resurgence, with healthcare distributor EBOS up 10 per cent.[1]
Resources, especially gold, led the market last financial year, but that rally is now slowing.
Uranium miner Deep Yellow fell 35 per cent1 and Capstone Copper also lost ground. For small cap investors, this shift matters.
With “resources struggling,” the industrials part of the market is starting to outperform, according to Diamant.
[1] As at 9 November 2026
Midterms: Headwind and tailwind for small caps
The US midterm elections sent mixed signals. Democrats gaining ground in Congress is seen as a negative for the AI trade, because it may become more challenging to get data centre projects up and running. But with the result now known, some uncertainty has lifted.
“History has shown that equity markets have responded quite well off the back of elections being done,” Diamant says, adding that this is usually a seasonally stronger time of year for equity markets.
What it means for small cap investors
Rate fears are easing and the performance gap between small caps and large caps is at historic highs.
Diamant believes this makes small caps very attractive on a valuation basis, particularly relative to the ASX 100.
As active managers, the Pendal Smaller Companies team has been getting on the front foot by trying to position the portfolio into some of the poor performing parts of the market.
“We had moved ahead of time, and more recently we have allocated more capital into some of these sectors that are starting to do well,” explains Diamant.
“We’ve taken money off the table in some positions that have contributed materially to returns over the last 12- 24 months, particularly in the contracting space.”
Find out about
Pendal Smaller Companies Fund
Patrick Teodorowski & Lewis Edgley,
Portfolio Managers
Frequently asked questions about small caps
Where are small cap investors looking now?
They’re moving into sectors that were out of favour a year ago, including consumer cyclicals, financials, REITs and healthcare. Through October and November, money came out of crowded areas such as AI-linked stocks, contractors, defence and resources.
Are resources still leading the small cap market?
No. Resources, especially gold, led last financial year, but that rally is slowing. Uranium miner Deep Yellow fell 35 per cent, and industrials are starting to outperform.
Is now a good time for small cap investors?
Pendal investment analyst Damien Diamant believes small caps are primed for a better period, particularly relative to the ASX 100. Rate fears are easing, and the performance gap between small and large caps is at historic highs.
About Lewis Edgley and Patrick Teodorowski
Lewis and Patrick are co-managers of Pendal Smaller Companies Fund.
Portfolio manager Lewis Edgley co-manages Pendal’s Australian smaller companies and micro-cap funds and conducts analysis on a range of smaller companies. He joined the Pendal Smaller Companies team in 2013 as an analyst, before being promoted to the role of portfolio manager in 2018. Lewis brings 20 years of industry experience with previous roles spanning equities research, as well as commercial and investment banking roles at Westpac and Commonwealth Bank.
Portfolio manager Patrick Teodorowski co-manages Pendal’s smaller companies and micro-cap funds and conducts analysis on a range of smaller companies. He joined Pendal in 2005 and developed his career as a highly regarded small cap analyst. Patrick holds a Bachelor of Commerce (1st class Honours) from the University of Queensland and is a CFA Charterholder.
About Pendal Smaller Companies Fund
Pendal Smaller Companies Fund is an actively managed portfolio investing in ASX and NZX-listed companies outside the top 100. Co-managers Lewis Edgley and Patrick Teodorowski look for companies they believe are trading below their assessed valuation and are expected to grow profit quickly. Lewis and Patrick together have more than 40 years of investment experience.
Find out about Pendal Smaller Companies Fund
Find out about Pendal MicroCap Opportunities Fund
Find out about Pendal MidCap Fund
About Pendal Group
Pendal is a global investment management business focused on delivering superior investment returns through active management.
In 2023, Pendal became part of Perpetual Limited (ASX:PPT), bringing together two of Australia’s most respected active asset management brands.
Pendal Global Property Securities Fund (APIR: RFA0051AU ARSN: 108 227 005) (the Fund)
On 9 October 2026, we advised that we had commenced a review of the Pendal Global Property Securities Fund (the Fund). This review is now complete, and, as a result, we have made the decision to terminate the Fund, effective on and from Tuesday, 17 November 2026.
Why is the Fund terminating?
Following AEW Capital Management, L.P.’s decision to cease as investment manager of the Fund, we reviewed whether a suitable replacement investment manager could be appointed. Given the Fund’s relatively small size and limited prospects for significant growth in funds under management in the foreseeable future, we concluded that appointing another specialist global property manager was not feasible.
Having considered the available options, we believe that winding up the Fund and returning the proceeds to investors is in the best interests of investors.
How this affects you?
Applications, transfers and withdrawals in the Fund will not be accepted after 2:00pm (Sydney time) on Tuesday, 17 November 2026 due to the Fund’s termination.
What happens next?
Following the Fund’s termination on Tuesday, 17 November 2026, we will begin to wind up the Fund. The assets of the Fund will be sold and the net proceeds of winding up will be paid to all investors in proportion to their unit holding.
What does this mean for you?
Your pro-rata share of the net cash proceeds from this termination will be paid directly to your nominated bank account on file on or around the week commencing Monday, 23 November 2026 or shortly thereafter.
If the Fund pays a final distribution, it will be paid to you prior to the termination of the Fund and included in your 2027 AMIT Member Annual (AMMA) statement. This statement will set out all the taxable components from distributions that you received/were attributed to you during the financial year ended 30 June 2027. It will be issued to you following the end of the financial year.
Questions?
If you have any questions, please contact our Investor Relations Team during business hours on 1300 346 821.
Here are the main factors driving the ASX this week, according to Pendal’s ANTHONY MORAN. Reported by portfolio specialist Chris Adams
THE big stories last week were the hot US consumer price index (CPI) inflation data, which set off a rally in bond yields, and the Jensen Huang scandal at Nvidia.
Global markets were reasonably strong despite these events, driven by a recovery in the tech/AI sector which bounced off lows from the previous week, assisted by positive news on the Anthropic IPO and a strong Coreweave result.
The S&P 500 gained 2.5%, the Nasdaq lifted 2.3% while Japan’s TOPIX 500 rose 6.3% and Korea’s KOSPI Composite advanced 4.6%.
The S&P/ASX 300 lagged with a 0.9% gain, given the relative scarcity of AI/tech stocks.
The October US CPI data saw 10-year US bond yields rise 30 basis points (bps) to 5.16% and the US dollar rally, which generally weighed on commodity prices.
The Australian dollar weakened 1.4% against the US dollar, due to the rise in US bond yields and perception the Reserve Bank of Australia (RBA) may be done hiking.
AI/Tech bounces back despite Nvidia issues
Nvidia was off 14% for the week following the revelation of CEO Jensen Huang’s alleged affairs, including one with a suspected Chinese agent. Huang resigned, with the CFO becoming the acting CEO.
The scandal shone a spotlight on allegations that Nvidia has supplied chips to China via intermediaries to bypass US export controls. This raises risks of penalties for breaching the law, as well as a hit to Nvidia’s revenue if these China sales are cut off.
There are also concerns that the acting CEO may see the company step back from its role as a key capital provider to the AI sector, as she has previously expressed some scepticism about the extent of its use of circular financing.
Despite Nvidia’s woes, tech/AI stocks had a strong week with the PHLX Semiconductor Index (SOX) up 8%, rebounding from last week’s seven-month low due to a few factors:
- The sector was perceived as being technically oversold, with the Information Technology sector trading at a price/earnings discount to the broader S&P 500 for the first time in a decade.
- A strong result from neocloud Coreweave which beat expectations, raised guidance and, importantly, had a benign perspective on the company’s financing risk. The stock gained 15%.
- Other chip manufacturers are expected to benefit from Nvidia’s issues e.g. AMD was up 19% for the week
- The Anthropic IPO is reportedly off to a good start with strong book coverage. This will be a big test of whether public markets will put the same valuation on these companies as venture capitalists have.
But financing concerns are still bubbling away with QTS Data Centres (owned by private equity firm Blackstone) cutting an AI debt sale size by 60% after failing to garner sufficient interest.
The Tech outperformance was reflected in Australia, where the sector rose 2.0% and was the week’s best performer. Xero (XRO, +8.8%) was the best performer in the S&P/ASX 100 after a good result.
The Nvidia result this week is likely to be very important for setting the sector’s near-term direction.
US policy & macro
October’s CPI came in hotter than expected; its third consecutive upside surprise.
The core measure was up 0.3% month/month versus 0.2% expected while headline was +0.4% versus 0.3% expected.
The hot print will fuel the debate as to whether the pass-through cost from energy – diesel as well as oil – will turn out to be both larger and longer-lasting than most in the market and the Fed have anticipated.
Goods inflation was +0.2% month/month, but Services was the main culprit at +0.4%.
Within the Goods segment there are signs that tariff impacts are persisting for longer than expected within categories most exposed to tariffs e.g. furniture, household appliances. For example, television prices were +3.3% month/month.
However, this should cease being a headwind in CY27.
The pass through of higher energy prices, via transportation and input costs, may also be affecting Goods inflation – as well as the ongoing impact of higher tech component pricing amid the AI boom.
Tariff effects may simply be rolling over more slowly and cost pass-through may be slightly larger than expected because of very strong demand conditions at the aggregate level in recent months; jobless claims continue to run at a low level, and broad demand indicators are strong.
Core Services ex Housing is running hot with transportation being a big driver, suggesting higher oil prices are bleeding into the Core measure. Among the sub-categories hotels rose 0.7% month/month, airfares 0.4%, and motor vehicle insurance 0.7%.
Housing inflation eased slightly, driven by slowing primary rent inflation. There were mixed signals on the outlook, with the rent index up but other housing market indicators softening.
While higher energy prices are driving hot inflation, Goldman Sachs estimates that the impact of oil price passthrough on inflation is at a peak level this quarter and will start diminishing soon.
However, US Federal Reserve Governor Christopher Waller flagged a Fed staff research note with estimates that imply a much larger and more persistent impact of oil and diesel prices on core PCE in the post-pandemic period.
The CPI print seemingly locked in a rate rise for the December 9th meeting and the market now expects another at the January or March meetings. The forward curve is currently pricing in 2.5 rate increases by March.
Prior to the CPI release Waller flagged the potential for a 50bp increase if the CPI was hot again, while Dallas Fed President explicitly called for at least two more 25bp rate hikes.
Essentially, the view is that current elevated inflation is being driven by some large factors such as tariffs, the oil price shock and AI-related cost pressure.
There is good reason to believe these will ease in CY27, although this is not a given.
Goldman Sachs is currently expecting a first rate cut in the December quarter of 2027.
The weakness in US housing across a range of metrics is likely to keep a lid on the occupancy cost contribution to CPI.
US existing home sales declined 9% year/year in October and hit the lowest level since 2010, while the lack of sales is leading to US existing home inventories rising to their highest level since 2015.
The culprit is higher bond yields which are driving up mortgage rates. A reprieve in October has been followed by a renewed spike last week after the hot CPI and signs of a still resilient US economy.
US housing weakness is yet to show up the earnings of exposed building materials companies like James Hardie (JHX) and Reece (REH), but at its recent 2Q result JHX highlighted a slowdown in volume growth was imminent.
Australia policy & macro
Commonwealth Bank’s (CBA) quarterly update last week showed a 7bp rise in home loan arrears in the September quarter, taking the rate of customers more than 90 days late on their mortgage to 0.8%.
While small in absolute terms, this is the highest level since 2012.
In contrast the loan loss rate, while ticking up 3bps in the quarter to 11bps, is still at historically low levels. This warrants watching closely.
Most banks don’t adjust monthly mortgage repayments lower when interest rates fall, as they did three times last year, but they do adjust them higher when they rise beyond their prior high-water mark.
In effect, this has meant that the three rate rises to date in 2026 have merely offset last years’ cuts and not impacted the cash flows of a large proportion of borrowers.
However, the September and November hikes will result in higher mortgage payments for this cohort, starting from next month.
This is something to bear in mind given the relief rally in stocks like JB Hi-Fi (JBH) on the back of a “rate rises are done” narrative.
It’s not catastrophic, but nor are we out of the woods just yet.
The Barrenjoey Economics Australian Financial Condition Index, at -1.8, suggests conditions are expansionary again for the first time since June. This comes after a final 0.1 reading for October (which was lower than the mid-month read of 0.6, driven by falling rates in the second half of the month).
This move occurs despite the November rate hike from the RBA (and five hikes in seven meetings this year) and largely reflects falling long-dated yields – onshore and offshore – and is a reminder that it is more than the cash rate that sets financial conditions.
Credit and money supply remains expansionary, with growth in business credit offsetting weakness in lending to the housing sector.
Last week saw a material re-pricing of rate cut expectations, with the dovish commentary that accompanied the most recent hike seeing the market now pricing a rate cut as more than likely by September 2027 and fully priced by the end of that year.
Cyclical stocks responded enthusiastically. A key question for equity investors is how far equities will buy into the rate cut story in 2027, even if activity is still slowing.
Analysis shows the relationship between rate expectations and cyclicals is strong and clear: when markets price cuts, cyclicals see a sustained rally, and when that pricing reverses, they fall.
In the short-term REITs, consumer discretionary and industrials have run ahead of the yield curve, so some pullback is possible, particularly as near-term data is likely to remain too hot.
But the medium-term trend of outperformance from cyclicals could persist even as economic data and domestic company results soften.
Find out about
Pendal Focus Australian Share Fund
Crispin Murray, Head of Equities
Other macro
UK GDP growth came in at 0.7% quarter/quarter in Q3. This was its fastest pace in two and a half years amid robust household consumption as well as public sector spending and investment.
The UK economy is proving more resilient to the Iran war-driven energy shock
AI-related investment has been a key driver of UK growth over the year. Estimates suggest AI-related categories have contributed about a fifth of growth in total gross value added in the economy this year to date.
Markets
Evercore’s Hedge Fund Survey had some interesting takeaways last week; net exposure has actually been increasing as the S&P 500 has pulled back since mid-October.
The sectoral moves are particularly interesting, with technology and healthcare being cut, while energy and consumer discretionary are seeing the biggest up-weightings.
In commodities, US dollar strength drove some softness during the week. Gold (-4.6%) fell on the CPI beat, while oil was down a touch (Brent Crude -2.5%) on no material developments in the Iran war.
Lithium spot prices are down 40% since September on the back of fears around a deterioration in demand in 2027. This in turn is due to the EU-China agreement limiting imports of Chinese EVs, cuts to Chinese battery export rebates and concerns that strength in utility battery demand may not persist in 2027.
Growth in battery shipments is still expected to be up 20-30% in 2027, but not as strong as prior expectations. This also comes against a backdrop of increasing supply in 2027 as mothballed capacity comes back on.
Given the extent of the weakness in the commodity price and related share prices, it is one to keep a watch on for renewed curtailments of supply.
The S&P/ASX 300 gained 0.9% but underperformed global markets due to less exposure to AI/tech.
The Aussie tech sector (+2.0%) was the strongest performing for the week, while we saw consumer exposed stocks, both discretionary (-0.1%) and staples (-0.7%) take a breather after a strong pop last week on the dovish tilt from the RBA.
Resources (+1.5%), energy (+1.5%) and industrials (+2.0%) were all stronger, being helped by the weaker Australian dollar and expected benefits of an end to rate cuts helping cyclically exposed stocks.
The key takeaways from bank reporting season were:
It is difficult to justify valuation premiums, but the unwind of regional AI trades is supporting share prices.
- Mortgage credit growth is likely to remain depressed through to mid-2027.
- Business lending growth remains ~10% but is guided to slow.
- There is increasing competition for loans and deposits, resulting in flat/falling margin despite rising rates.
- Early credit quality stress at NAB, which could be a lead indicator for the broader sector.
- Capital ratios are starting to fall, with optimisation exhausted.
- Low single digit revenue growth is prompting cost discipline, but the net result is small consensus downgrades.
About Crispin Murray and the Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has over three decades of investment experience and leads one of the largest equities teams in Australia. Crispin’s Pendal Focus Australian Share Fund is a high-conviction equity fund with a two-decade track record across a range of market conditions.
Pendal is an Australian investment management business focused on delivering superior returns for our clients through active management. Pendal is part of Perpetual Group.
Why do emerging markets go right or wrong at the country level? Pendal senior fund manager JAMES SYME discusses the key factors to consider when investing in emerging markets
- Learn more about Pendal Global Emerging Markets Opportunities Fund
WHEN assessing investments in emerging markets, economic and political cycles, valuations and currencies are all factors that should be considered, argues SYME.
In this video, Syme explains why the Pendal Global Emerging Markets Opportunities team reviews every market every month to find the strongest cyclical opportunities and steer clear of overvalued ones.
He also delves into why a weaker US dollar, and today’s crowded AI trade make emerging markets an important way for US-heavy investors to diversify.
Find out about
Pendal Global Emerging Markets Opportunities Fund
About Pendal Global Emerging Markets Opportunities Fund
James Syme, Paul Wimborne, Ada Chan and Roshni Bolton are co-managers of Pendal’s Global Emerging Markets Opportunities Fund.
The fund aims to add value through a combination of country allocation and individual stock selection.
The country allocation process is based on analysis of a country’s economic growth, monetary policy, market liquidity, currency, governance/politics and equity market valuation.
The stock selection process focuses on buying quality growth stocks at attractive valuations.
Find out more about Pendal Global Emerging Markets Opportunities Fund here
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
Here are the main factors driving Australian equities this week, according to investment analyst JACK GABB. Reported by head investment specialist Chris Adams
EQUITY markets initially rallied, then fell heavily, after the Democrats flipped both the House and Senate in the US midterms.
The S&P finished the week down 2.7% while the Nasdaq lost 3.4%. Losses were steeper in Asia; Japan, Taiwan and Korea were all down 9-12%.
In contrast, Australia was a relative and absolute standout, with the S&P/ASX300 up 1.4%.
Tech (-7%) and energy (-12%) stocks drove the decline in the US.
Brent crude oil fell 16%, gold rose 5%, bonds rallied on haven demand (US 10-year yields -5bps) while credit spreads widened with the yield on CoreWeave bonds rising by about 1% to about 16%.
Huge volatility saw big unwinds of growth and momentum trades, with significant hedge fund de-grossing exacerbating moves.
It’s been a challenging couple of months for hedge funds. A number were said to be returning capital last week.
Attempts were made to offload datacentre loans – ING was reported to be selling a US$500 million portfolio.
Consumer, real estate and healthcare stocks gained in the US on the midterms result.
Australia, which has at times been the source of funding for other markets, was the relative and absolute outperformer, with tech (+8.8%) benefitting from the sharp move higher in NextDC following the investment by Goodman Group and Digital Realty.
Energy stocks and most major mining companies fell (similar to the US), but real estate, consumer and gold stocks rose.
The RBA hiked, as expected, but a more dovish outlook drove down future hike expectations. Most economists now predict the RBA is done.
Expectations for a US Federal Reserve hike next month rose 5% to about 78%.
In terms of currencies, Australia was again standout, though the AUD was the worst-performing major currency after the RBA move, dropping 2.3%. The USD was little changed, up 0.4%.
US midterms
Leaving aside the politics, the outcome of the midterms was significant.
Broadly speaking, here are the key trends:
- Exacerbation of pre-existing concerns around the AI trade
Fears over a clamp-down on data-centre development drove tech stocks lower. Concern centred on Texas, where the incoming Democrat governor has called for an immediate moratorium on development. About 30-40% of proposed US data-centre developments are planned in the State, so the disruption has the potential to be significant. For context, Jefferies has cut its forecast for total US capacity additions by 8% over 2026-2030.
- Emphasis on voter concern around the Iran conflict and cost of living
Expectation for an Iran resolution rose, which saw oil sell off. There was renewed speculation over tariff changes, particularly given the Democrat majority in the Senate gives them a stronger voice on trade, notably around the US-Mexico-Canada free-trade agreement. However, control still rests with the Executive.
- Spending
Healthcare and real-estate stocks benefitted from a belief that more support will be forthcoming. On the flipside, the outlook for US debt arguably worsened. This is a tailwind for gold, albeit its move higher was more a function of the drop in oil.
- Grift
Democrats are reportedly planning on investigating several of the administration’s deals. Who this ultimately affects is unclear, but there are risks for the mining sector given the significant number of critical minerals deals.
It is important not to overstate the potential impact here.
Many of these issues have been apparent for some time. Changes at the state level may be significant, but at the federal level the ability to enact change without executive support is limited.
US macro and policy
Expectations for a December rate hike jumped around during the week, before Friday’s labour market data saw them rise 5% higher to 78%.
Despite that, longer term expectations fell.
Labour market data was a clean sweep for the hawks on monetary policy. October nonfarm payrolls rose 165k (versus 70k expected), with August and September both revised higher.
The unemployment rate dropped to 4.1% (versus 4.2% expected) and average hourly earnings rose 0.4% month/month (versus 0.3% expected).
Combined, the data appears to clear the way for a December hike, though consumer price index (CPI) data tomorrow will also be key.
While inflation is still rising (potentially peaking in December), inflation expectations are falling, with the University of Michigan 1-year inflation expectations down 0.4% to 4.3% (versus 4.6% expected) and 5-10 year expectations 0.1% lower to 3.4% (versus 3.5% expected).
Importantly, credit conditions also continue to tighten, particularly for the tech sector.
As a case in point, Meta sold US$25bn in bonds on Tuesday, i.e. just before the Thursday’s tech selloff. Their notes due in 2056 priced at a yield premium of 2.2% above Treasuries, ~0.9% wider than a comparable note sold in April.
Australia macro & policy
The RBA hiked as expected after the deputy governor’s hawkish comments last month. But a 6-3 voting split resulted in a more dovish interpretation that was further boosted by edits to the policy statement.
In her speech, Governor Michelle Bullock noted higher inflation was now “baked in” to forecasts for next year, implying the bar for a further hike was higher.
This was further reinforced by the policy statement dropping the wording “including increasing the case rate target further if needed”.
The statement also said earlier rate hikes “have tightened financial conditions” and “the economy is slowing, housing price have fallen significantly, and the unemployment rate has risen”.
Taken together, the consensus view is that the tightening cycle is over – though we’ve seen previous predictions prove premature.
This view is reflected in implied rates, which have shifted lower. Markets are now pricing in >50% chance of a cut by this time next year.
The knock-on impact was that the AUD was the worst-performing major currency last week, ending down 2.4% against the USD.
That isn’t helpful for the outlook for inflation.
The reason given for the three dissenting votes was potential downside risk given housing market weakness, an unemployment rate drifting up and no sign of accelerating wage growth – all in response to previous rate rises. Hence there was an argument to wait for more data.
Perhaps more importantly, in the past 12 months there have now been five rate hikes.
Per the RBA, the impact of the last two (May, September) are yet to flow through, thus now was “probably” a good point to take stock.
The RBA now sees Australian CPI peaking at 4.5% in Q4, declining to 2.7% next year.
The Reserve revised up unemployment rate expectations from 4.5% this quarter to 4.7%. End 2027 unemployment is seen at 4.9% and end 2028 at 5.1%.
The drop in oil prices last week provided a further tailwind to the RBA’s dovish tilt.
Brent fell 16% to US$98/bbl which, while still above the Q2 and Q3 average, represents a material drop. The RBA sees the Middle East conflict as a key inflation driver.
Consumer and real-estate stocks rallied on the perceived RBA pivot (and household spending actually rose 0.6% month/month in September versus 0.0% prior and 0.2% expected). But caution is still warranted given the coming months will “feel like a recession”.
As we heard from the banks last week, stress is appearing in customer cash flows, with a jump in watchlist loans prompting NAB to lift collective provisions.
David Jones entering into administration is also a timely reminder of retail challenges.
Find out about
Pendal Focus Australian Share Fund
Crispin Murray, Head of Equities
Commodities
The midterms had a meaningful impact on commodities with oil the standout, down 16%, on hope anti-war election sentiment translates to a normalisation of flows through the Strait of Hormuz.
Positively, Australian fuel stocks remain healthy. Diesel inventory stands at 31 days, jet fuel at 28 days and petrol 41 days.
Gold, which for much of this year has traded as the inverse of oil, rose 5%, also benefitting from its safe-haven status.
The new US Congress will be sworn in on January 3, while the US is likely to hit its US$41.1 trillion debt ceiling in February.
It’s worth noting that gold price rose 12% and 17% in the three months prior to debt ceilings in 2011 and 2023.
Copper has been a clear beneficiary of data centre spending, even if modest in terms of actual demand, and fell 4%. It is now just shy of its 200-day moving average.
Uranium, rare earth and spodumene prices were little changed, with Democrat control of Congress unlikely to translate to material policy changes in the near-term.
There was renewed speculation of potential tariff changes given cost-of-living concerns in the election, but U.S aluminium premiums actual rose 3% during the week.
Day-to-day control of tariffs remains with the Executive, although Democrat control of the Senate does give them a stronger voice on trade, particularly around the U.S-Mexico-Canada free trade agreement.
Iron ore rose 2%, with sentiment gradually improving as we enter a seasonally stronger period. The risk of supply cuts – either driven by current low prices or by disruption from the impasse between Fortescue and China Mineral Resources – also pose a potential tailwind.
Markets
US stocks staged a slight comeback after Thursday’s crash, with some trading desks and strategists calling it a bottoming-out post-washout.
However, the rebound was modest, with sentiment still fragile given on-going concerns around capex, funding and the data centre build out.
Any further drop in oil and/or bond yields could help, but the likely Fed hike in December still looms.
Ultimately, sentiment around AI-related stocks is likely to continue to dominate, which means the near-term focus will be on results from the likes of CoreWeave and Nebius, as well as any news on the Anthropic IPO – where the implied valuation fell US$300bn last week.
Looking further out, the likelihood is inflation peaks in December, which means the Fed hike, if taken, could look like a policy mistake.
That risks exacerbating a slowdown, particularly if AI sentiment sours further. In that deflation-esque scenario, cyclical assets could suffer and defensives outperform, unless or until the Fed pivots.
In Australia, tech and consumer stocks led gains, with NextDC (NXT, +77.2%) the standout. Gold, consumer and property stocks also rose, while energy and utilities fell.
Financials underperformed, with the results from National Australia Bank (NAB, -3.6%) and Westpac (WBC, +0.6%) driving small earnings downgrades.
About Jack Gabb and Pendal Focus Australian Share Fund
Jack is an investment analyst with Pendal’s Australian equities team. He has more than 14 years of industry experience across European, Canadian and Australian markets.
Prior to joining Pendal, Jack worked at Bank of America Merrill Lynch where he co-led the firm’s research coverage of Australian mining companies.
Pendal’s Focus Australian Share Fund has an 18-year track record across varying market conditions. It features our highest conviction ideas and drives alpha from stock insight over style or thematic exposures.
The fund is led by Pendal’s head of equities, Crispin Murray. Crispin has more than 27 years of investment experience and leads one of the largest equities teams in Australia.
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
How can investors find ‘Yield Royalty’ stocks that pay reliable dividends? Pendal Imputation Fund co-portfolio manager OLIVER RENTON explains
- Dividend certainty can support higher company valuations
- Franking credits encourage higher Australian payout ratios
- Find out about Pendal Imputation Fund
WHEN a company turns a profit, its managers and board have several important decisions to make.
How much to retain on the balance sheet as cash or use to pay down debt?
What proportion to reinvest in the business?
How much should be returned to shareholders as dividends?
All of these choices tell us a lot about a company’s mindset and its confidence for the future.
But for investors chasing yield, it’s the dividend strategy that investors should pay particular attention to, especially:
- The dividend a company pays relative to its profit, known as the dividend payout ratio (DPR), and
- The dividend relative to the company’s share price, known as dividend yield, or just simply yield.
When comparing yield for various listed companies, investors might well ask: ‘Which are Australia’s reliable, dividend-paying “Yield Royalty” and how can I identify them?
Here is Pendal’s approach:
Yield Royalty
Investors looking for Yield Royalty may often think about the stocks that never (or hardly ever) cut their dividend.
These companies have historically demonstrated relatively consistent dividend payments.
The ability to consistently pay reliable dividends is a signal that demand for a company’s products, its business model and capital structure are all resilient against fluctuations in various economic cycles.
For example, the oldest investor-owned public utility in the US, The York Water Company (NASDAQ: YORW), has provided a continuous dividend dating back to 1877.
Consumer goods giant Procter and Gamble (NYSE: PG) has raised its dividend for 69 straight years.
Australian-listed companies have some impressive statistics also.
There is some speculation that Westpac (previously Bank of New South Wales) may be the longest dividend-paying company in the world, dating back to 1800s.
Washington H. Soul Pattinson has been listed since 1903 and paid a dividend every year since then.
Hear more insights from Oliver:
A proud record
Australia can’t compete with other global markets in terms of sheer depth of listed companies, but we have a proud record when it comes to dividends.
A nuance of the Australian market is “imputation”, which basically means getting a tax credit for company tax that has already been paid.
Australian companies naturally have higher payout ratios due to the tax advantages that accrue to domestic shareholders in the form of fully franked dividends.
Thought higher payout ratios do mean there is less room for error against an economic cycle or some other event which temporarily stresses the business.
How to find Yield Royalty
So which Australian companies can be considered Yield Royalty and how do you identify them?
In an Australian context we define Yield Royalty as those companies that have not cut their dividend for five straight years, and only once in the past 10 years.
This period includes the Covid-19 pandemic, which placed a lot of short-term pressure on many businesses.
Within the ASX100, these companies meet the criteria:
- Aristocrat [ALL]
- APA Group [APA]
- CAR Group [CAR]
- Charter Hall [CHC]
- Computershare [CPU]
- Medibank [MPL]
- Northern Star [NST]
- Pro Medicus [PME]
- Scentre [SCG]
- Steadfast Group [SDF]
- Sonic Healthcare [SHL]
- Washington H. Soul Pattinson and Company [SOL]
- Technology One [TNE]
It’s an interesting mix.
Many are clear leaders in their respective markets, though that’s not always the case.
We would argue many of these take a sustainable, longer-term view as to how they run their respective businesses.
These companies have strong dividend track records, but only a minority actually pay a yield greater than the broader market.
Being classed as Yield Royalty should reflect positively on a company’s rating and how it’s valued more generally.
Certainty or confidence about the forward prospects of a dividend stream, as guided by history, is inherently linked to a lower discount rate and a higher valuation.
Find out about
Pendal
Imputation Fund
Oliver Renton, Co-Portfolio Manager
Case study: Medibank
For the Pendal Imputation Fund we think about which companies might be considered Yield Royalty in the future.
We also consider which stocks may drop out of this basket – and the implications for how the market may perceive and value these companies as a result.
A stock in this basket that we do own in the Pendal Imputation Fund is health insurance provider Medibank [MPL].
Medibank has grown its dividend for six years in a row including nine of the past 10 years.
Medibank has a forecast dividend payout ratio of 80 per cent and is forecast to pay out almost all its free cash flow in the form of dividends over the next couple of years.
These payout ratios are quite full but supported by a conservative capital position which should provide buffer in more difficult times, should they arise.
The short-tail nature of private health insurance means regulatory capital requirements are relatively low, certainly as compared to general insurers.
In addition, return on tangible equity is high supporting this relatively full dividend payout ratio.
Management and the board run a conservative and sustainable business, taking well-considered, long-term decisions.
MPL has a strong track record of managing hospital partnerships and government relationships which stands them in good stead.
The company handled Covid windfalls in a measured way, opting to deliberately return excesses to customers which built trust, brand and competitiveness.
We think the conservative, sustainable way this company is managed – backed by historical delivery – warrants a premium rating.
Medibank also has one of the healthier franking credit balances in the market and pays fully franked dividends.
Case study: Sonic Healthcare [SHL].
One stock we don’t own in the Yield Royalty basket is Sonic Healthcare [SHL].
SHL has a stated progressive dividend policy – it is paying a relatively high dividend yield of 5.5%, partially franked.
Dividends increased by 4% pa in the five years leading up to Covid.
SHL and other pathology operators did very well through the pandemic, which saw the company lift dividends by 7% in FY21 and 10% in FY22.
The subsequent years have not been as kind. Margins have been squeezed by labour cost inflation on one side and tight government budgets on the other.
Dividends have continued to increase against a backdrop of earnings that have fallen about 60% since FY22.
This has resulted in the dividend payout ratio exceeding 100% in FY24 and FY25.
The company also re-geared its balance sheet through M&A, such that it’s less prudent to fund dividend increases by taking on more debt.
With speculated funding cuts in two of SHL’s largest markets in Germany and US – as well as persistently high labour cost pressures – there is a real prospect that earnings remain under pressure.
Ultimately the company may need to make the hard decision to walk away from its policy and cut its dividend.
Yield Royalty and Pendal Imputation Fund
Pendal Imputation Fund has about 8 per cent of its portfolio in ‘Yield Royalty’.
This is a higher proportion than the broader market, but we remain selective in deciding who makes it in.
Yield Royalty is just one of the various ways Pendal Imputation Fund thinks about yield and how yield is expressed in the portfolio.
Others include:
- Bond Proxies: stocks that have bond-like attributes and should therefore trade as such; preferred in a falling interest rate environment
- “Rock-Solid Dividends”: Stocks that give us confidence on their dividend prospects based on dividend history, capital position, cash flow generation profile, tight range of market estimates and high historical returns.
- Growth-At-the-Right-Yield: Stocks that give you favourable yield per unit of growth.
- Dividend Growers (DG): companies that might not have high yields today but impressive dividend growth track records that compound over time
In future articles we will delve further into these factors.
About Oliver Renton and the Pendal Imputation Fund
Oliver is an investment analyst and portfolio manager with Pendal’s equities team.
Starting his career with Pendal in 2004, Oliver has also worked with Pendal’s quantitative services, product and performance and attribution teams.
He holds a Bachelor of Commerce from the University of New South Wales, where he was awarded the Australian Institute of Banking and Finance Award in his penultimate year, and is a CFA Charter holder.
Pendal Imputation Fund is an actively managed portfolio of Australian shares which we believe will provide a higher yield than the market average.
With dividends and franking credits taking on renewed relevance for Australian investors, Pendal investment analyst OLIVER RENTON explains why tax effective yield matters when inflation and cost-of-living pressures are high
- Find out about Pendal Imputation Fund
IN THIS video podcast, Oliver Renton explains how imputation strategies seek to optimise tax-effective income while maintaining exposure to the growth potential of equities.
He explores who these strategies may suit, how they compare with term deposits and fixed income, and the risks investors should keep in mind.
Renton also outlines why active management can be particularly important when investing for yield, helping investors look beyond headline yields and avoid potential “yield traps”.
Here’s an excerpt from the video podcast:
“Broadly speaking, an imputation fund is purposely looking to optimise the overall tax effective yield profile of that fund.
“Yield appeals to different investors in different ways and tax effective yield is no different.
“For an income fund, I think [active management is] even more important.
“Active management should, and we think does, have the ability to rule out those stocks that are maybe perceived as yield traps, stocks that are structurally impaired or challenged.”
Find out about
Pendal
Imputation Fund
Oliver Renton, Co-Portfolio Manager
About Oliver Renton and the Pendal Imputation Fund
Oliver Renton is an analyst focused on the Health Care and Utilities sectors. Starting his career with the business in 2004, Oliver has also worked with the Quantitative Services, Product and Performance and Attribution teams.
The Pendal Imputation Fund is an actively managed portfolio of Australian shares. This fund is designed for investors who want the potential for long-term capital growth and tax effective income, diversification across a broad range of Australian companies and industries and are prepared to accept higher variability of returns.
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
Here are the main factors driving the ASX this week, according to head of listed property PETER DAVIDSON. Reported by head investment specialist Chris Adams
- Find out about Pendal Property Securities Fund
AI ENTHUSIASM faded quickly last week amid softer results from Amazon and Alphabet.
This helped drive a sharp reduction in bond yields. The US 10-year yield fell 9 basis points (bps) to 4.91% and is on track for one of its largest monthly falls in nearly three years, as the tech sell-off sent investors scrambling for the safety of Treasuries.
The US Federal Reserve held rates steady, while Australian CPI data pointed to a likely RBA hike on Melbourne Cup Day.
Oil was steady (Brent crude +0.8% to US$117.64) while gold (-2.6%) fell to a 12-month low and Bitcoin (-5.2%) fell on cyber security fears.
The S&P 500 fell 0.6% while the S&P/ASX 300 gained 1.4%.
In the local market, long-duration heavy-capex stocks weakened, and China-related concerns weighed on commodities.
Markets now await the US midterms and a possible resumption of conflict in the Middle East.
Interest rates and outlook
The Fed, European Central Bank (ECB) and Bank of Japan (BoJ) each met last week and kept rates steady as expected.
- The Fed held at 3.75-4.00% in a 10-2 vote, with two members favouring a 25bp hike.
- The ECB held at 2.5%, warning that energy costs leave December’s meeting as a live decision. Christine Lagarde confirmed her February departure as President.
- The BoJ hold likewise offered little comfort on inflation.
- The Reserve Bank of New Zealand surprisingly also paused, despite very clear expectations for a rate hike.
A December hike is a live option for most, if not all, of these central banks – so it was a pause in the rate hike cycle, rather than the all-clear.
The Bank of Canada (BoC) was the odd one out, hiking 25bps to 2.5%, as expected. This was its first increase since July 2023, to stop high energy prices spilling into broader inflation. BoC Governor Tiff Macklem flagged that further hikes may be needed but said they will proceed carefully; the next decision is on 9th December.
The Fed’s statement kept its tightening bias, while Chair Kevin Warsh’s press conference leant modestly dovish, indicating that September’s hike was filtering through financial and credit conditions, and the next intermeeting period would bring more data.
He stressed that the pause neither softened the inflation target nor promised another hold.
Markets are pricing roughly 71% odds of a December hike and just 58bps of tightening over the next year.
Warsh’s line about tighter interest rates getting “in the cracks” of the economy signals a Fed in wait-and-assess mode, not one that is done.
December remains very much live, but the Fed wants more data before it moves – potentially a tacit admission it doesn’t like what it is seeing – so the call hinges on whether the numbers turn after the US midterms.
Traders also note there were only two dissenters, which suggests the hawkish camp is narrower than feared and that December will be decided by the data, not by a hawkish revolt on the Committee.
Macro and policy Australia
Inflation remains stubbornly high.
Last week’s consumer price index (CPI) showed headline inflation jumping from 4.0% in August to 4.3% in September, while the trimmed mean edged up to 3.6% and its six-month annualised pace hit 4.0%, the fastest in the short history of the series.
The quarterly trimmed mean rose 1.0%, ahead of the RBA’s 0.8% forecast.
That leaves the RBA odds-on to lift the cash rate to 4.85% on Melbourne Cup Day, an 18-year high. Markets are pricing an ~81% chance of a hike, and 25 of 28 surveyed economists, including all of the big four banks, agree.
The hike could come with hawkish guidance, as sticky services inflation, higher oil and the RBA’s view that the labour market is tighter than it had judged push its inflation forecasts higher.
The peak for this cycle is drawing closer, but the market needs clear evidence of slowing in the official data – especially building approvals, household spending and job vacancies – before calling a top.
Yet while inflation is running hot, the housing market is cooling quickly.
Prices are already correcting as higher rates bite – and falling house prices are a reliable dampener on household confidence.
With October trading updates from JB Hi-Fi, Bunnings and Coles already pointing to softer spending, the housing slowdown should weigh on activity and do some of the RBA’s heavy lifting for it.
Macro and policy US
Headline personal consumption expenditures (PCE) inflation accelerated to 3.6% year/year in September.
Core PCE – traditionally the Fed’s favoured measure – rose 0.32% month/month (consensus 0.3%), lifting the annual rate from 3.01% to 3.12%.
The markets see room for two more Fed hikes by next September.
Q3 real GDP grew 3.4% annualised, ahead of the 3.2% consensus and the fastest pace in a year. Strong consumption did most of the work, with AI-led equipment investment also a key driver.
However, momentum faded late in the quarter, with the monthly personal income report showing real spending flat month/month in September.
The US consumer has split in two, and housing-linked demand is rolling over. Earnings results last week painted a K-shaped consumer under affordability strain.
UPS, for example, called out the “K curve” in spending directly and a payments network said its highest-spending cohort is still growing fastest.
October’s confidence gains were confined to households earning US$100,000+. Further down the ladder, the signs are weaker: Hershey trimmed its sales outlook to the bottom of its range as stretched households tightened their belts, and Nielsen IQ had Halloween candy sales down 6.7% in the month to 17th October.
Housing and repair/remodel remain the economy’s soft underbelly.
This can be seen in appliance manufacturer Whirlpool cutting guidance for the third time this year on soft North American volumes, while among homebuilders D.R. Horton guided for lower revenues.
The upshot is the top end of town is propping up the aggregate numbers, while everyone else trades down and rate-sensitive categories do it tough.
The market is positioned for a Democratic sweep in the Midterm elections. Polls favour Democrats in both chambers, and sentiment largely reflects it.
Two outcomes matter;
- If Republicans hold the Senate, with key races inside the margin of error, that’s a tailwind for equities into year-end.
- If Democrats win a bigger Senate majority than expected, perhaps 53+, 2028 worries and the prospect of higher corporate taxes could add incremental pressure on valuations.
Markets are bracing for renewed US strikes on Iran once the midterms are out of the way, but diplomacy is still in play.
The US has reportedly told several Gulf states to prepare for a short, intense campaign after the election, with strike options being readied.
The diplomatic push has picked up in parallel: Saudi, Turkish and Pakistani delegations met Iran’s leaders in Tehran early in the week, Qatar tabled a new seven-day framework, US Vice President JD Vance reportedly wrote to Iran’s leadership, and Semafor reports talks towards a temporary peace deal. Tehran insists its conditions be met first.
With Brent already pushing towards US$118/bbl, the risk for equities is a short, sharp energy shock, or any disruption to flows through Hormuz, reigniting inflation fears.
AI and technology
The AI trade rolls on, but where the spoils land is getting harder to pick, and even early movers like Google are feeling the heat.
The question is not demand, but returns on investment. In the current US earnings season, markets are increasingly focused on returns and cash generation
The cloud businesses for hyperscalers Microsoft, Alphabet and Amazon continue to surge with demand reportedly outstripping capacity.
- Microsoft’s Azure grew 48% and is guided to accelerate to 49–50%, with commercial remaining performance obligations (RPOs – essentially the backlog) up 73% to US$677 billion.
- Google Cloud more than doubled, up 103% to US$30.7 billion, on a US$561 billion backlog.
- Amazon’s AWS grew 39% to US$46 billion, its fastest in 19 quarters, with a US$578 billion backlog and 40%+ growth pencilled in for both 2027 and 2028.
Updates from Asia reinforced the demand story, as Korea’s SK Hynix reported a more than seven-fold rise in quarterly operating profit, with high bandwidth memory (HBM) and dynamic random-access memory (DRAM) capacity sold out through 2029.
HBM demand is running at twice available supply, lifting Korean semiconductor stocks and the KOSPI (+3.3%).
However, the hyperscaler core businesses told a softer story.
- Alphabet’s search advertisement growth was its slowest in five quarters, falling to +12% from +17% in Q2, missing the +15% consensus. Management blamed FX, tough comps, softer retail and media spending, and weaker monetisation of AI Mode queries, conceding they monetise at a lower rate. So far AI has driven genuine incremental growth rather than cannibalising existing businesses, but this print has put the cannibalisation worry back on the table.
- Amazon online stores grew just 2% and the ad business 11%, its slowest on record, with advertising revenue missing by about 6%. The retail businesses also came in light, though a Prime Day timing shift didn’t help.
Meta, by contrast, has moved more aggressively to weave AI into its advertising business, driving stronger engagement and revenue growth. Its ad revenue is now approaching Google’s, and some analysts expect it to overtake Google globally by the end of 2026.
Ad growth remains strong by historical standards, but the slowdown at Google and Amazon has sharpened investor focus on the profitability of AI investment and the importance of keeping ad revenues ticking over.
The net effect was a sharp reversal in stock prices.
- Alphabet suffered a record fall, wiping out nearly US$500 billion as US$9.1 billion of cash burn compounded the search miss.
- Amazon slid on Friday (-5% on the week) as AWS fell short of elevated expectations and US$77 billion of quarterly capex left a US$42.4 billion trailing-12-month free cash outflow.
- Meta is down 10% since reporting, and even Microsoft gave back its post-result pop.
Oracle’s Investor Day initially eased funding concerns, noting customer-provided hardware, prepayments and vendor financing are reducing upfront capital needs. They are expecting free cash flow to turn positive in 2H28 and reach US$30 billion+ in FY29, and incremental capital raises are capped at US$20 billion through FY30.
The rally soon reversed, though, suggesting financing is only part of the equation.
The pain ultimately spread well beyond the hyperscalers. Intel fell sharply on memory costs and weak PCs while ServiceNow dropped 27% on a softer RPO guidance.
The upshot seems to be that AI demand and adoption are not in question, but any slip in the core business gets punished, given lofty expectations.
AI-related capex also remains in focus. Alphabet (US$195–205 billion) and Amazon (~US$220 billion) held capex guidance, and Microsoft’s trim to ~US$170 billion was down to third-party delays.
All three flagged more to come in 2027 and, in combination with Meta, are tracking towards roughly US$750 billion this year.
The market saw this as a disciplined approach to capex and the AI-hardware related stocks were firmer over the week.
Funding worries remain. In the past few weeks Meta has raised US$37.5 billion of equity, with up to US$60 billion more planned for 2027.
SpaceX lined up a US$40 billion GPU lease, Broadcom a US$63 billion custom-chip special purpose vehicle, and Anthropic is proposing to raise $100 billion in cash.
At this point, we continue to see three key risks to the rollout of AI:
Cyber: AI-powered attacks or a model malfunction in a critical function could raise defence costs, fuel the political backlash and trigger tougher regulation. The road ahead may be bumpier than markets are pricing.
Financial: the late-1990s internet boom showed that transformative technology can still fuel bubbles and misallocated capital, and higher bond yields have sharpened scrutiny of capex, despite some relief from the recent flight to quality.
Political: in the US, fewer than 30% of people support the current pace of deployment, citing power grids, electricity bills and jobs. The president remains firmly behind the rollout, but the rest of the body politic is more cautious. Policy could turn less supportive after the midterms, and more so if a Democrat wins in 2028.
Find out about
Pendal Property Securities Fund
Peter Davidson, Head of Listed Property
Markets
Bond yields
Since the Iran conflict erupted, longer-dated sovereign yields have come under sustained pressure globally. Ten-year yields are up 175bps in France, more than 100bps in the US and the UK, and 75bps in Japan, Germany and Canada.
However, this has reversed recently. Yields have fallen even as oil has risen, and the stock-bond correlation has turned negative amid the tech sell-off.
If volatility in equities and credit persists, the flight-to-quality bid could hold up in the near term.
US earnings
Earnings growth in the “S&P 493” is on pace to beat the Mag 7 for the first time since ChatGPT kicked off the AI boom, reflecting a strong US economy driven by onshoring/manufacturing and a firmer consumer.
Australian equities
Banking system data for September showed mortgage growth is soft but stable at ~3% (one-month annualised) as weaker investor lending is offset by a partial owner-occupier recovery.
Banks are hoping this marks the lows, but renewed rate hikes will likely hurt the Spring selling season.
Business credit remains strong at +15% (one-month) and +10% (three-month) annualised.
About Peter Davidson and Pendal listed property strategies
Peter Davidson is Pendal’s head of listed property.
Peter has held financial markets roles spanning portfolio management, advisory and treasury markets over more than three decades.
Specialising in the Property, Retail, Insurance and Infrastructure sectors, he has previously held roles with Midland Montagu Australia, Daiwa Securities and has served as the non-executive director of the Industry Superannuation Property Trust.
Pendal is an Australian investment management business focused on delivering superior investment returns for our clients through active management.
Pendal Property Securities Fund invests mainly in Australian listed property securities including listed property trusts, developers and infrastructure investments.
About Pendal Group
Pendal is an Australian investment management business focused on delivering superior investment returns for our clients through active management.