
Volatility in global markets is set to continue, but it can work in your favour. Here are a few tips from Pendal’s Michael Blayney
- Inflation rising, equity and fixed income markets volatile
- Investors should stick to their long-term strategies
- Niche opportunities available in equities
GLOBAL inflation, rising energy prices, Evergrande and the Chinese property market, big swings in equity markets around the world, rising bond yields, trillion-dollar-spending US packages in doubt.
It’s a tricky time to be an investor. And that’s before geo-politics and Covid risks are considered.
For investors, it’s about having a strategy and sticking to it, says Michael Blayney, Pendal’s head of multi-asset.
“The recent sell-off has been nothing compared to last March, but people are getting a bit more concerned about inflation,” Blayney says. “Bond yields are rising and equities are a bit weak.
“In these circumstances you have to have a sensible investment process which you anchor all your decisions to.
“The alternative — managing your portfolio based on what’s in the headlines — is a good way to lose money,” he says.
It’s about ensuring an investor’s asset allocation is based on their long-term strategy.
“When times get tough you stick to your strategy. When markets are doing well, you take some profits. When markets are lower you can top up your holdings. The volatility can work in your favour,” he says.
Blayney expects more volatility in global markets.
Find out about
Pendal Multi-Asset Funds
“This massive fiscal and monetary stimulus can’t go on forever. At some point you have to reintroduce a level of restraint…. and as we go through that, there will be choppiness in markets.
“We’re not expecting a massive market correction but it is an environment where it pays to have a little bit of extra cash in your portfolio so you can jump on opportunities when they emerge.”
The best investors manage their portfolios through volatility.
“At the moment, bond markets are expensive. Not ridiculously but they are still somewhat expensive,” Blayney says.
“You’ve also got increasing inflationary pressures and the winding back of very, very easy monetary policy. You put all that together and you have negative momentum in the bond market. So for us, we are invested a little bit less in government bonds at the moment.
“In terms of growth assets, it’s about saying ‘let’s take on a bit of risk but try and find places which aren’t directly in the most ferocious part of the storm’,” he says.
“For example, if you have bond yields rising and you look at the tech names which have been very, very expensive in part propped up by the low-bond yields, that part of the market has more risk attached to it.”
Good, niche opportunities
“Instead look for some good niche opportunities like United Kingdom equities and some emerging markets. Mexico is an example because it’s been cheap for a long time,” Blayney says.
“We also invest in dividend futures in Europe which is a bit unusual because it’s linked to the dividend component rather than the price component of a stock.
“And then there’s the assets that can provide a slow and steady yield — things like listed renewables and some other forms of listed infrastructure.
Blayney says value and small cap stocks have been outperformed by technology stocks in recent years, meaning there’s opportunity for them to catch up.
“You need to take exposure to some of these sorts of assets to keep some growth in your portfolio without being exposed to overvalued stocks, that are vulnerable to a correction.”
About Pendal’s multi-asset capabilities
Pendal’s diversified funds provide investors with a variety of traditional and alternative asset classes and strategies.
These include Australian and international shares, property securities, fixed interest, cash investments and alternatives.
In March 2024, Perpetual Group brought together the Pendal and Perpetual multi-asset teams under the leadership of Michael O’Dea.
The newly expanded nine-strong team will manage more than $6 billion in AUM and create a platform with the scale and resources to deliver leading multi-asset solutions for clients.
Michael is a highly experienced investor with more than 23 years industry experience, including almost a decade leading the team at Perpetual.
Brenton manages the Pendal MidCap Fund and natural resources portfolio, drawing on over two decades of expertise across precious metals, derivatives, investment banking, and private equity to invest in large and small cap mining companies.
Brenton has worked with Randfontein Estates Gold Mine & Harmony Gold as a mine geologist and Executive, and at JP Morgan, Deutsche Bank, Craton Capital, Macquarie Funds Group, and Taurus Funds Management in research and asset management roles.
Graduating with honours, he holds a Bachelor’s degree in Science (Geology) and a Master’s degree in Science from the University of Johannesburg. He is a member of the CFA Institute and has previously served on the International Accounting Standards Board.
George’s investment management career spans over three decades with Pendal and its predecessor firms. He is responsible for management of credit, fixed interest and short term income portfolios, including Pendal’s highly regarded Sustainable Australian Fixed Interest Fund, Short Term Income Securities Fund and Credit Impact Trust.
George holds a wealth of experience in portfolio management and credit analysis. He has also worked across numerous fixed income, credit and money market portfolios in portfolio management, credit analysis and dealing roles. Prior to this George worked in an accounting role for three years.
In 2019 George was awarded the Alpha Manager status by Money Management’s parent, FE fundinfo, in recognition of his career-long performance in the asset management industry. George was one out of 11 Australia-based investment professionals included in this list of esteemed professionals across multiple asset classes, after being assessed on his ability to create risk-adjusted alpha (outperformance) over his entire track record.
George obtained a Master’s degree in Business (Finance), a Bachelor’s degree in Business (Accounting & Finance) and a Graduate Diploma in Applied Finance and Investment.
Here are the main factors driving the ASX this week according to our head of equities Crispin Murray. Reported by portfolio specialist Chris Adams
MOUNTING fears of stagflation — higher inflation and slowing growth — weighed on equity markets last week.
The S&P/ASX 300 fell 2.12% and the S&P 500 was off 2.19%.
Several factors are driving concern. These include persistent supply chain bottlenecks, the potential impact on export volumes from Chinese power shortages and a more hawkish tone on inflation from Fed Chair Powell.
OPEC’s decision not to add any additional supply to the oil market beyond already-planned increases — despite evidence demand is re-accelerating as the Delta Covid wave fades — added fuel to this fire.
In response to stagflation fears, equities and bonds have sold off, while commodity prices have risen.
In equity markets, higher bond yields have prompted a rotation away from growth stocks towards re-opening plays and companies offering protection against inflation.
At this point we don’t expect this issue to de-rail markets. But we wouldn’t be surprised to see the rotation away from growth continue.
Powell’s hawkish turn
After a relatively dovish tone on inflation at Jackson Hole, Powell was slightly more cautious in the September Fed meeting. He was more hawkish still in his presentation to the European Central Bank’s (ECB) Sintra conference last week.
This reflects inflationary data persistently coming in higher than expected and evidence that its drivers are shifting away from short-term factors.
In particular, the Fed Chair noted tension between the Fed’s goals on inflation and employment. He also noted “transitory” inflation may last longer than expected.
Powell later moved to soften the message, but the market is dwelling on the uncertain outlook.
The sub-plot is Powell’s likelihood of a second term.

Pendal Focus Australian Share Fund
A high-conviction equity fund with 16 years of strong performance in a range of market conditions
Some suggest this is in question due to the recent Committee trading scandal — and that the narrative has as a result shifted to the inflation risks to be addressed, rather than the story of growth.
Powell is regarded as one of the more hawkish potential leaders of the Fed.
Any shift at the top of the Federal Open Market Committee will reinforce market expectations that inflationary pressures will be accommodated.
The inflation question
The Fed’s favoured inflation measure — US Core personal consumption expenditures (PCE) — rose 0.3% for the month and is running at 3.6% year-on-year.
Notably, some of the “Covid bounce-back” categories are no longer big drivers. This is evident in the quarterly annualised growth of 2.7% in the Core PCE — the highest since 2008.
There are two broad forms of inflation to consider:
- Cost pressures building from input prices and shortages, as we are seeing now. This usually resolves itself via reduced demand as prices rise or products are unavailable. But through this process we have a period of higher inflation and lower growth, which is not a good combination for equities.
- Expectations of inflation translating into rising real wages as workers leverage labour shortages. This enables higher spending which reinforces inflationary pressure. This is a far more sustained inflation — the wage-price spiral — which ends only when central banks slam on the brakes.
At this point we are witnessing the first form of inflation.
The hope is that it fades quickly as supply chains are restored and demand is fulfilled, easing inflationary pressure without any impact on growth.
The concern is that if supply chain issues persist too long and we get significant energy price spikes in the Northern hemisphere winter, it will drive a more severe impact on the global economy.
An additional fear is that current labour shortages in a number of countries — combined with central banks maintaining their current aim of higher real wages — would see inflation entrenched via wages.
For example the current wage negotiations at US equipment manufacturer Deere & Co will be worth watching, with employees threatening their first strike since 1986.
There is a long way to go, but risks have risen.
This all puts central banks in a tough position.
Either they react through tightening policy as we are seeing in countries such as South Korea and potentially New Zealand.
Or they hold the line as the US is doing, which risks fuelling continued strong demand, exacerbating the issue.
China’s inflation impact
The market has been focused on China’s role in the inflation question. The focus last week was power outages which have led to curtailed output in some industries.
There are three factors at play here:
- The most significant factor is Beijing’s policy of less energy-intensive growth – ie electricity consumption growing slower than GDP. Nine provinces have missed targets for electricity consumption, prompting those governments to limit power supply. This is a self-inflicted issue, but tied to a signature policy for China’s leadership.
- The shortage of coal supply. This is partly driven by the ban on Australian exports and compounded by Covid-linked supply issues with Mongolia and Indonesia. Environmental policies are limiting efforts to ramp up domestic supply.
- At the margin, a dryer-than-usual wet season has reduced hydro-electric generation.
Power shortages are flowing through to higher prices in inputs such as cement and aluminium.
They are also limiting output in a number of processing industries and retail suppliers, exacerbating supply shortages.
Beyond the role this plays in potential inflation, we need to be mindful of Australian companies with exposure to Chinese supply chains.
The current situation limits China’s ability to stimulate in response to slowing growth, with potential implications for the ASX’s miners.
Covid and vaccines
Delta seems to be waning as a market issue. New daily case trends are improving in developed and emerging markets. This is flowing through to better activity levels in countries affected by restrictions.
The main news was the approval of the Merck / Ridgeback oral antiviral pill which roughly halved hospitalisation and morbidity rates among Covid patients in trials.
Ease of use and manufacturing scalability make this a real potential tool in the response to Covid.
A similar product from Roche / Atea and also from Pfizer due to report trial results soon.
Markets
US 10-year bond yields were only 1bp higher last week, but rose 18bps over the course of September.
Commodities continued to climb higher. Brent crude was up 1.5% and iron ore 4.4%. Even without a material shift in yields, this was enough to support the continued rotation away from growth stocks.
As a result technology (-5.94%) and healthcare (-5.62%) underperformed. Concerns over China weighed on the miners, but the energy sector (+4.48%) showed signs of life on the back of a stronger oil price.
About Crispin Murray and Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia. Crispin’s Pendal Focus Australian Share Fund has beaten the benchmark in 12 years of its 16-year history (after fees), across a range of market conditions.
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Find out more about Pendal Focus Australian Share Fund here.
Shareholder-initiated resolutions will be a standout feature of this year’s AGMs as investors step up activism on ESG issues such as climate change and executive pay, says Regnan’s Susheela Peres da Costa
- Shareholder-initiated resolutions again a feature of AGMs
- Boards more willing to lend support
- Find out about Regnan’s impact investing solutions
ACTIVISM has long been a feature of annual general meetings held by ASX-listed companies
But an increasing sophistication in the way resolutions are prepared and drafted is leading to more engagement from shareholders and boards.
There are even recommendations from some companies that shareholders vote in favour of activist proposals, says Susheela Peres da Costa, head of advisory at Regnan, a leader in impact investing and ESG (Environmental, Social and Governance).
It’s a major development — and it highlights how portfolios can deliver real results on climate change and other ESG issues when holding companies in portfolios instead of divesting, says Peres da Costa.
“There’s a few reasons for this seismic shift,” she says.
“One is that the advocacy groups have become more sophisticated in understanding the language of shareholders and have a greater appreciation for what is actually within companies’ powers to do.
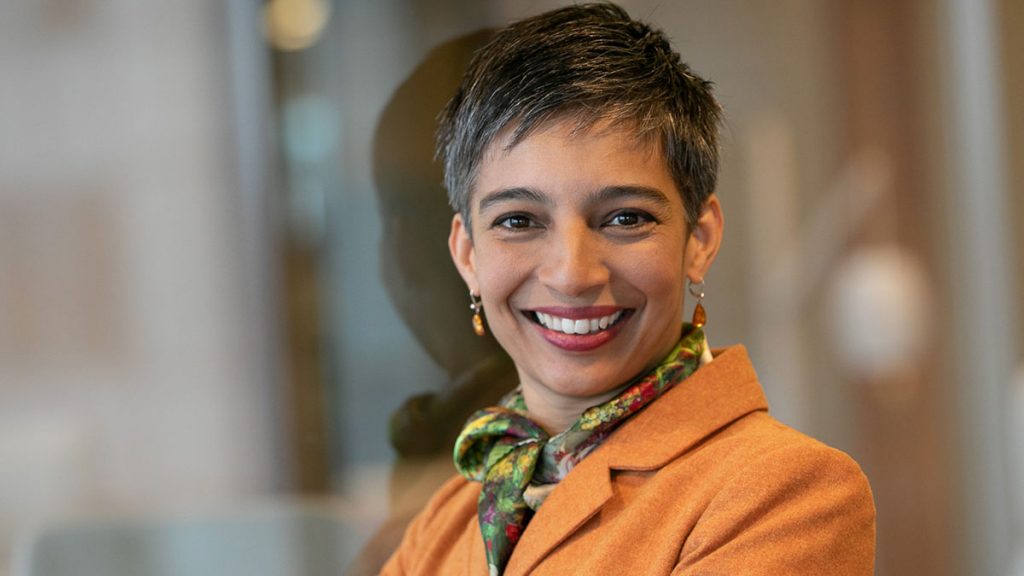
“But also, investors have become more comfortable about casting their votes based on the substance of the resolution before them — rather than fearing it will be seen as a protest.
“Having a company like BHP recommend that shareholders support a resolution brought by an advocacy group turns that kind of thinking on its head.”
At BHP’s upcoming annual meeting, activists have proposed the mining giant rethink its membership of industry associations that do not support the Paris Agreement’s climate goals. The BHP board agrees and has recommended shareholders pass the resolution.
“That was unthinkable just a few years ago,” says Peres da Costa
A similar resolution has been put to miner South32 which has also recommended shareholders vote in favour.
In the past, activist resolutions were often dismissed by companies and institutional shareholders declined to take proposals from activists seriously.
“Investors have also changed their approach,” says Peres da Costa.
“Big institutions are increasingly recognising that using their votes in a principled way can communicate their position more clearly and transparently than relying only on private meetings behind closed doors.”

Find out about
Regnan Global Equity Impact Solutions Fund
In Australia, successful shareholder resolutions are often drafted by non-government organisations with roots in the not-for-profit sector.
Campaigner Market Forces grew out of the Friends of the Earth climate group. Researcher and shareholder advocate Australasian Centre for Corporate Responsibility is partly funded by industry super funds.
Resolutions may have started as way for activists to make a protest, but increasingly institutional shareholders are co-sponsoring shareholder resolutions being put to boards.
The lesson for investors?
“Stewardship does drive change. It is working, and success breeds further success,” says Peres da Costa.
“It may not get the cut-through that divestment does, but shareholder engagement and voting can really change things in the world. Changes that companies make after a successful shareholder resolution are proof.”
About Susheela Peres da Costa
Susheela is Regnan’s head of advisory. She has more than 15 years of domestic and international experience advising institutional investors on responsible investment.
As Head of Advisory, she has assisted small foundations through to the world’s largest institutions, including a successful 18-month project in Switzerland responsible investment leadership for a global full-service bank and strategic advice to the UN-backed Principles for Responsible Investment on upgrading stewardship.
Susheela chairs the Responsible Investment Association of Australasia and is special adviser to the co-chair of the Australian Sustainable Finance Initiative.
About Regnan
Regnan is a responsible investment leader with a long and proud history of providing insight and advice to investors with an interest in long-term, broad-based or values-aligned performance.
Building on that expertise, in 2019 Regnan expanded into responsible investment funds management, backed by the considerable resources of Pendal Group.
Regnan Global Equity Impact Solutions Fund invests in mission-driven companies we believe are well placed to solve the world’s biggest problems, while the Regnan Credit Impact Trust (available in Australia only) invests in cash, fixed and floating rate securities where the proceeds create positive environmental and social change.
Find out about Regnan Global Equity Impact Solutions Fund
Find out about Regnan Credit Impact Trust
For more information on these and other responsible investing strategies, contact Head of Regnan and Responsible Investment Distribution Jeremy Dean at jeremy.dean@regnan.com.