
Deep, country-level analysis is critical in emerging markets investing, says Pendal’s James Syme. India and Mexico are two examples of countries with hidden strengths
- Conventional wisdom says India, Mexico should slow
- Hidden depths to their economies leave them well placed to grow
- Find out about Pendal Global Emerging Markets Opportunities Fund
LOOKING beyond the headlines is critical in investing, especially when assessing emerging markets, says Pendal’s James Syme.
India and Mexico are two current examples of countries with unexpected, hidden strengths.
Rising inflation and higher commodity and energy prices are traditionally a negative for commodity importing countries like India and Mexico, says Syme, who co-manages Pendal Global Emerging Markets Opportunities Fund.
Yet he likes both countries due to domestic factors that leave them well placed to weather global economic changes.
“Mexico is a major oil producer, but a significant commodity importer that trades on the strength of its manufactured exports to the US.
“India has a long-standing vulnerability to commodity prices both through inflation and the current account balance.
“So why are we positive on these two markets?”
The reason is hidden in the domestic data.
For India, it’s the unsung strength of its computer service exports. For Mexico, it’s the record remittance income from citizens working abroad.

Find out about
Pendal Global Emerging Markets Opportunities Fund
“It’s easy to overlook the strength of India’s computer services exports. There’s no single trade number that captures things like IT services, software product development, business process outsourcing, data services, engineering services and the like,” says Syme.
“But there’s a central bank survey. In 2013, Indian exports of these types of services were $62.6 billion but in 2021 they were $133.7 billion.
“Because the listed companies make up so much of that market you can almost get a feel for how they are doing by extrapolating from the 20 largest listed business.
“And this year, ending March 2022, should be a really good year.”
This matters because in 2013, India’s oil imports — the key economic vulnerability traditionally feared by investors — exceed its IT services exports by $100 billion.
But in 2021, the deficit was erased.
“A significant part of India’s oil import bill is now being paid by its IT services exports — and they continue to grow significantly.

Sustainable and
Responsible Investments
Fund Manager of the Year

“The India of today and the India of ten years ago are not the same country.”
A similar story in Mexico
Syme tells a similar story about Mexico.
As a commodity importer and manufactured goods exporter, Mexico should struggle in times of rising input prices.
But the overlooked factor is the huge and growing remittances being sent home by Mexicans abroad.
“Lots of countries have income from citizens who work abroad, but for Mexico, remittance income is really big. Family remittances were $52 billion in calendar 2021.”
These remittances almost entirely come from the US, where tight labour markets, especially for low paid workers, are proving “exceptionally positive for the Mexican economy”, says Syme.
“One of the main things Mexico exports is Mexicans. Being adjacent to the US is Mexico’s secret strength.
“Like IT services in India, it’s been a story of steady growth. In 2021, remittances in Mexico were up 25% on the calendar year before.
“It doesn’t show up in the trade balance — but we think you have to take it into account.”
About James Syme and Pendal Global Emerging Markets Opportunities Fund
James Syme is a senior portfolio manager of Pendal’s Global Emerging Markets Opportunities Fund with Paul Wimborne.
The fund aims to add value through a combination of country allocation and individual stock selection.
The country allocation process is based on analysis of a country’s economic growth, monetary policy, market liquidity, currency, governance/politics and equity market valuation.
The stock selection process focuses on buying quality growth stocks at attractive valuations.
Find out more about Pendal Global Emerging Markets Opportunities Fund here
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Rising oil and gas prices mean boom times for emerging market energy exporters such as Brazil, Mexico and Russia, says Pendal EM manager JAMES SYME
- Rising oil prices are lifting energy exporters
- Boom times for countries that sell energy
- Brazil, Mexico and Russia the picks
GLOBAL equity investors should look to Brazil, South Africa and Russia in 2022 as rising oil and gas prices deliver widespread economic growth to emerging market energy exporters, says Pendal’s James Syme.
Shifting attention to commodity exporters would be a change for many global investors who have been enamoured with China’s internet sector and the big semi-conductor stocks in recent years.
Syme — who co-manages Pendal Global Emerging Markets Opportunities Fund — agrees that has been the right approach for the past decade.
“But the Chinese economy is not particularly strong at the moment, and while it’s been a long time coming back for some of these other emerging markets, everything is starting to look good,” he says.
The oil price at around US$90 a barrel is at its highest levels since 2014 amid surging demand, while European near-term gas futures — which normally trade between EUR 10-20/MWh — recently spiked above EUR 180.
Syme says it’s not surprising that energy prices are rising as a long period of low investment in new capacity is followed by a sudden post-Covid resurgence in demand.
Western Europe has been reducing domestic gas production for environmental reasons, lifting its reliance on Russian gas. Germany has been steadily decommissioning nuclear power, including shutting three of its last six nuclear plants on December 31.
Find out about
Pendal Global Emerging Markets Opportunities Fund
And recent weather patterns have also played a role. Over the past few years Europe has had unseasonably cold winters and warmer than usual summers — which both lift energy use — while relatively windless autumns have capped power production at wind plants.
At the same time, Russian domestic demand for gas is rising and Russia’s gas exports to other countries, including China, have been increasing.
‘Boom times’
“Rising energy prices and the resulting inflationary push are going to be an economic and political problem for energy consuming nations,” says Syme.
“But for the countries that sell energy, this is fantastic.
“It’s just boom times.”
Syme says the boom is not limited to energy, with many other agricultural and mining commodities also seeing price rises, which benefit Brazil and Russia, and other commodity exporters like South Africa.
“And we haven’t really seen the reaction in terms of what that might mean for domestic stocks or currencies that we would expect to see.
“That’s why we continue to have positive view towards some of these markets and think they’re overlooked.”
Higher commodity prices flow directly through to economic growth in exporting nations.
Sustainable and
Responsible Investments
Fund Manager of the Year
More export earnings mean companies can lift capital investment, hire more staff and pay higher wages, boosting consumption. Higher exports also improve a country’s current account balance and support its currency.
The resulting growth flows through to tax revenue, allowing governments to lift spending or cut taxes.
“It’s positive across the board,” says Syme.
Natural gas is also benefiting from its potential role as a bridge in the transition to lower carbon emissions.
“Both in terms of production and consumption, the carbon emissions per unit of energy for natural gas are lower than oil and much, much lower than coal.
“Notwithstanding the geopolitics, Europe could significantly reduce its carbon emissions if it switched power generation from coal to natural gas.”
So where to focus investment attention?
“We think this is a good time to own Latin America, where we prefer Brazil and Mexico” says Syme.
“We also think it’s a good time own South Africa and Russia.”
About James Syme and Pendal Global Emerging Markets Opportunities Fund
James Syme is a senior portfolio manager of Pendal’s Global Emerging Markets Opportunities Fund with Paul Wimborne.
The fund aims to add value through a combination of country allocation and individual stock selection.
The country allocation process is based on analysis of a country’s economic growth, monetary policy, market liquidity, currency, governance/politics and equity market valuation.
The stock selection process focuses on buying quality growth stocks at attractive valuations.
Find out more about Pendal Global Emerging Markets Opportunities Fund here
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
One of 2021’s takeaways is that Covid is cyclical, says Pendal’s JAMES SYME. That means investors should be on the look-out for opportunities among over-sold reopening stocks
- Sell-off in the reopening trade provides opportunities
- Strong balance sheets with attractive valuations will reward investors
- Find out about Pendal Global Emerging Markets Opportunities Fund
ONE of the big lessons of 2021 for investors is that Covid is cyclical.
“It has these short-term cycles,” says James Syme, who co-manages Pendal’s Global Emerging Markets Opportunities Fund.
“Things get bad and then they get good and then they get bad again. And when things are getting bad, it’s not the end of the world.
“The speed of that cycle is much faster than a business or interest rate cycle. It’s measured in less than a year. That’s one of the key take-aways of 2021.“
When investing in this type of environment, it’s important to stick to fundamentals, and not get too swayed by trends, he says.
“If you buy good businesses with strong balance sheets at attractive valuations, you’re doing the right thing. We’re investors. We aren’t trading stocks.”
Opportunities among over-sold re-openers
Global conditions may not be optimal for emerging markets right now, but there are opportunities to be found partly because the recent selloff in the re-opening trade has been overdone says Syme.
“A combination of tightening monetary policy by the US Federal Reserve, a stronger US dollar and a slowdown in China creates a difficult environment.

Find out about
Pendal Global Emerging Markets Opportunities Fund
“If you think about what fuelled the boom in emerging markets from 2002 to 2008 it was relatively soft US monetary policy and a huge boom in China,” Syme says.
But there are opportunities, in part because Syme believes the selloff in the re-opening trade has been overdone.
“We always think about the opportunity in emerging markets, rather than the opportunity of emerging markets,” he says.
“Leisure, airlines, hotels and even bits of retail have been sold, and that’s accelerated in the last month by fears about the new Omicron variant of Covid-19.
“But I think some of the sell-off is too much. We are going to get back to normal at some point.”
Where the opportunities are
Syme has been considering reopening opportunities, and recently added a Korean entertainment business to the fund he manages, Pendal Global Emerging Markets Opportunities Fund.
In Brazil, the fund holds an airline and a brewer.
He still sees opportunities in emerging markets that are reliant on commodity prices.
“Commodity prices remain elevated, notwithstanding some have come off a bit,” he says.
Sustainable and
Responsible Investments
Fund Manager of the Year
That helps other parts of commodity producing economies, he says, nominating retail in South Africa, where mineral exports have been extremely strong.
There are also opportunities for the reopening trade in the Middle East.
“We own a real estate name in the UAE which is a beneficiary of higher oil prices. Because it’s in Dubai, it also benefits from the normalisation of travel and tourism,” he says.
Syme acknowledges the risk that the short-term performance of some of these stocks may disappoint.
“But the next couple of quarters of cash flow may not reflect the overall value of the business.”
He emphasises the need to find opportunities within emerging markets and some bourses he remains underweight.
“In Russia we’re concerned about political risk and the Ukraine.”
About James Syme and Pendal Global Emerging Markets Opportunities Fund
James Syme is a senior portfolio manager of Pendal’s Global Emerging Markets Opportunities Fund with Paul Wimborne.
The fund aims to add value through a combination of country allocation and individual stock selection.
The country allocation process is based on analysis of a country’s economic growth, monetary policy, market liquidity, currency, governance/politics and equity market valuation.
The stock selection process focuses on buying quality growth stocks at attractive valuations.
Find out more about Pendal Global Emerging Markets Opportunities Fund here
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
Trouble in China is obscuring strong performances in other emerging markets, demonstrating the importance of a country-by-country approach in this asset class, says James Syme
- India, Mexico and South Africa performing well
- With each Covid wave economic impact lessens as economies adjust
- Find out about Pendal Global Emerging Markets Opportunities Fund
INVESTORS in emerging markets have experienced challenges in recent months, but the underlying story is more nuanced.
Falls in the MSCI Emerging Markets Index since February’s peak are almost entirely dominated by shares in China and South Korea — masking strong performances in countries as disparate as India, Mexico and South Africa.
This demonstrates the importance of taking a country-by-country approach to emerging markets investing says James Syme, who co-manages Pendal Emerging Markets Opportunities Fund.
“As we always say, even if emerging markets as a whole is not an opportunity, there’s always going to be individual opportunities within the emerging markets sector,” says Syme.
India is booming
Much of the news coverage of India in 2021 focused on its steep Covid second wave, which in May was killing more than 4000 people a day.
But Covid has subsided and economic stimulus has supported an economic boom.
“Now, we’ve got capital inflows, a rising stock market, rising property prices — India is in this fantastic boom.
Find out about
Pendal Global Emerging Markets Opportunities Fund
“Valuations are challenging — but that represents the fundamental strength of the economy.”
India’s strength is even more impressive given the strong US dollar, high oil price and higher US bond yields, which would normally be expected to lift inflation, blow out the trade deficit and be a drag on Indian stocks.
But inflation in India is contained, coming in at 5.3 per cent to August, versus more than 10 per cent in other emerging markets like Brazil, and the trade deficit is rising slower than economic growth.
“So India looks great. It’s one of our favourite markets and one of our biggest overweights.”
South Africa stronger
Similarly, South Africa has emerged from its political unrest in July to perform more strongly. Its mining sector is growing strongly and the domestic economy is recovering from Covid.
“Traffic stats, credit growth, vehicle sales — they all look pretty strong and there have been big upgrade in growth estimates from the central bank,” says Syme.
Fears of rising Covid cases knocking emerging markets economies off course were misplaced.
“It’s becoming more manageable. With each successive Covid wave, companies and populations and governments learn how to cope.
“The first wave was terrible. There was no toilet roll, no eggs and no one knew what to do.
“Now, if you get another Covid wave every one knows what to do — the kids go home, the lessons are on Zoom, the parents work from home, food delivery picks up again. People adapt.
“With each wave, the economic impact is less because economies adjust to deal with it.”
About James Syme and Pendal Global Emerging Markets Opportunities Fund
James Syme is a senior portfolio manager of Pendal’s Global Emerging Markets Opportunities Fund with Paul Wimborne.
The fund aims to add value through a combination of country allocation and individual stock selection.
The country allocation process is based on analysis of a country’s economic growth, monetary policy, market liquidity, currency, governance/politics and equity market valuation.
The stock selection process focuses on buying quality growth stocks at attractive valuations.
Find out more about Pendal Global Emerging Markets Opportunities Fund here
Pendal is an independent, global investment management business focused on delivering superior investment returns for our clients through active management.
COST OF LIVING pressures are creeping in, with more to come.
I’ve lost track of how many politicians have promised to “ease the squeeze”, but with an election early next year it’s probably getting dusted off.
So far the official data is not fully reflecting this, although food and fuel prices should see another healthy headline inflation number for Q3 when released in late October.
All this has happened with subdued demand.
As mentioned many times over the past 18 months this has been — and remains for now — supply led.
However talk of transitory is misleading — unless three years is now considered transitory.
When NSW reopens shortly, high savings and incomes should see a surge in demand, pushing prices higher again.

Find out about
Pendal’s Income and Fixed Interest funds
Supply will be slower to come back, partly mandated (eg restaurant dining numbers) and partly due to businesses having closed.
Good luck finding a restaurant booking in December. I would imagine proprietors take advantage of this with pricing. Who would blame them after the last 18 months ?
After a subdued September, due to a rare fall in risk assets, market inflation expectations are returning this month, once again nudging 2%. We expect to see 2.5% by year end.
Wagse remains the missing piece for medium-term inflation.
Everyone is reporting worker shortages but so far companies are looking to short-term measures to attract and keep staff — a sign-on bonus here, flexible conditions there.
However the dam wall of ten years of low wage growth is at risk of bursting.
I know if I worked in affected industries — from healthcare to construction to hospitality — I’d be taking advantage of a sellers (workers) market for labour. A recent increase in strike action suggests this realisation is dawning.
At risk of sounding like a broken record, higher inflation is not guaranteed, but insurance remains cheap.
About Tim Hext and Pendal’s Income & Fixed Interest boutique
Tim Hext is a Pendal portfolio manager and head of government bond strategies in our Income and Fixed Interest team.
Tim has extensive experience in banking, financial markets and funding including senior positions with NSW Treasury Corporation (TCorp), Westpac Treasury, Commonwealth Bank of Australia, Deutsche Bank, Bain & Co and Swiss Bank Corporation.
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.
Find out more about Pendal’s fixed interest strategies here
About Pendal
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
In 2023, Pendal became part of Perpetual Limited (ASX:PPT), bringing together two of Australia’s most respected active asset management brands to create a global leader in multi-boutique asset management with autonomous, world-class investment capabilities and a growing leadership position in ESG.
Higher inflation, resilient growth and rising oil prices have forced the RBA back into action. Pendal head of cash strategies STEVE CAMPBELL explains where to from here
- Inflation pressures remain stubbornly high
- More rate hikes may follow
- Find out about Pendal’s cash funds
THE Reserve Bank of Australia (RBA) has raised the cash rate by 25 basis points to 4.60% at its September meeting.
Following the RBA’s August meeting, the market priced in only a 15% chance of a rate hike at the most recent meeting. So what changed?
Expectations for a rate hike increased following the release of the July monthly inflation data in late August. The data showed trimmed mean inflation rising by 0.5% for the month and 3.6% over the year. The annual number was higher than expected and saw the market price a rate hike at the RBA’s next meeting in September as being 50/50.
The national accounts then showed economic growth increasing by 0.4% in the second quarter and 2.1% over the year. The quarterly number was slightly better than expected. The RBA’s Statement on Monetary Policy (SoMP) had forecast annual growth of 1.9%. The market moved to price a hike at 69%.
The icing on the cake has been the increase in the oil prices. The Brent November contract rose from $82 to a peak of $105 in mid-September. The price has subsequently come back however bond yields remain elevated, as do bowser prices.
The Australian three-year government bond rate peaked at 5.05% before recovering some ground. A three-year rate around 5% says that the RBA is not done hiking, and cuts shouldn’t be expected anytime soon either.
What is driving inflation?
The RBA in its statement pushed a lot of blame onto fuel prices. Perhaps it wanted to avoid the current criticism being pushed by many that excessive government spending has been boosting domestic inflation.
A key area behind this year’s hikes has been housing inflation.
The graph below shows the contribution to overall CPI from the items in housing inflation. This has risen from ~0.4% in mid-2025 to around 0.9% now, with the bulk coming from the new dwelling component.
This is not house price inflation – this is the inflation involved in the inputs into housing. This captures the inflation challenge facing the RBA.
Building material costs are rising due in part to the conflict in the Middle East.
At the CEDA conference in late September Governor Michele Bullock also pointed out other supply shocks stemming from the Russia-Ukraine conflict and tariffs. It’s the combination of these supply shocks that risks embedding higher inflation expectations.

And the housing sector also faces labour cost pressures from the growth in data centre capital expenditure that compete for electricians, plumbers and other tradies.
Data centres themselves will not add to net economic growth in the build-out phase. Most of the components are imported and will weigh on the National Accounts net export contribution.
Yet they can add to inflationary pressures on a few fronts as they compete with other sectors for labour and materials.
Electricity prices can be expected to rise. The risk of a drought is increasing. Water prices (and food inflation) may also add to inflationary pressures. Overall, the pressure on inflation remains too high.
Where to from here?
The RBA is unlikely to stop at a single hike. In an unfortunate piece of timing the August monthly inflation series is released tomorrow. We also get the more comprehensive quarterly inflation series in late October along with another monthly inflation series release.
The RBA will have a clearer inflation picture for the next meeting on Melbourne Cup Day. Currently, expectations sit at 1.0% trimmed mean for the third quarter CPI, well above the 0.6% to 0.7% comfort zone.
This should see November priced as another likely hike.
Find out about
Pendal Managed Cash Fund
Steve Campbell, Head of Cash Strategies
If you’d like to hear more about how Pendal’s Income & Fixed Interest team is positioning for this environment, please contact us through your account manager by reply email.
About Steve Campbell and Pendal’s Income and Fixed Interest team
Steve Campbell is Pendal’s head of cash strategies. With a background in cash and dealing, Steve brings more than 20 years of financial markets experience to our institutional managed cash portfolio.
Find out more about Pendal’s cash funds:
Short Term Income Securities Fund
Pendal Stable Cash Plus Fund
Pendal Managed Cash Fund
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.
The Reserve Bank of Australia (RBA) may be on hold, but the inflation fight is far from over. Pendal head of cash strategies STEVE CAMPBELL breaks down the latest commentary and what it means for future rate moves
- RBA watches data as inflation persists
- Business activity complicates inflation outlook
- Find out about Pendal’s cash funds
THE RBA left the cash rate unchanged at 4.35% at its August meeting. The decision was unanimous. No surprises there.
After the weaker inflation data in late July the market removed any likelihood of further tightening.
The key points from the RBA’s statement today are:
- Headline inflation is still too high and trimmed mean inflation remains elevated;
- The labour market has eased by a little more than expected although leading indicators point to only limited easing;
- Momentum in the housing market has shifted and new housing loans have declined noticeably;
- Historically weak productivity growth continues to constrain potential growth; and
- Inflation is not expected to return to the target band until the end of 2027
Also released today were the RBA’s updated set of economic forecasts via its Statement on Monetary Policy.
The latest set of forecasts are as follows: –
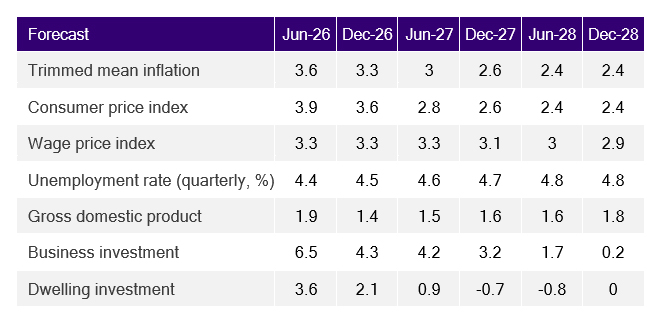
Some high level observations here are: –
- Inflation is not forecast to move back in the band until the end of next year. The RBA also noted that there are upside risks to this projection.
- Data centres are having an impact with business investment forecasts for 2026 revised 3.5% higher to 4.3% and for 2027 revised 1.4% higher to 3.2%. The benefit to economic growth is more subdued due to the imported components required detracting from the net trade position.
- Dwelling investment has been revised lower, with the 2027 forecast reduced by 0.4% to -0.7%. No surprises there either – if those building are no longer getting the price they need to be warrant building, then the tools go down
Productivity growth remains a key concern for the RBA, which sees the economy running with demand ahead of supply currently, and a period of weaker growth is required to bring this back into balance.
If demand was to pick up for whatever reason, then it is likely to feed through more quickly into higher inflation outcomes. The RBA does not want to see higher inflation expectations becoming embedded in the economy.
NAB Business Survey – picking up, slightly
The NAB monthly business survey showed both capacity utilisation and labour costs picking up – not something the RBA would welcome.
Deputy Governor Andrew Hauser has spoken about capacity utilisation previously. The economy did not have the excess capacity to handle the pickup in demand in the second half of 2025 without generating inflation.
According to the NAB survey, capacity utilisation picked up from 81.9% in May to 83% in July.
Another piece of data – household spending – released in early August was also much stronger than expected.
According to the Australian Bureau of Statistics (ABS), household spending rose 0.8% in June taking annual household spending growth to 6%.
So where to from here?
There are plenty of moving parts in the inflation equation.
Data centre building will offset the decline from dwelling investment in the nearer term.
It is not without inflation consequences. Competition for labour along with the energy required to maintain those centres, for example.
Inflation remains uncomfortable for the RBA. Further policy tightening can’t be ruled out. Each monthly inflation data will be closely watched.
Find out about
Pendal Managed Cash Fund
Steve Campbell, Head of Cash Strategies
If you’d like to hear more about how Pendal’s Income & Fixed Interest team is positioning for this environment, please contact us through your account manager by reply email.
About Steve Campbell and Pendal’s Income and Fixed Interest team
Steve Campbell is Pendal’s head of cash strategies. With a background in cash and dealing, Steve brings more than 20 years of financial markets experience to our institutional managed cash portfolio.
Find out more about Pendal’s cash funds:
Short Term Income Securities Fund
Pendal Stable Cash Plus Fund
Pendal Managed Cash Fund
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.
June CPI data has eased expectations of another rate hike in August, although inflation remains above target and the RBA’s tightening bias is likely to stay in place. Pendal’s head of cash strategies STEVE CAMPBELL explains
- Softer inflation lowers August hike expectations
- RBA likely to retain tightening bias
- Find out about Pendal’s cash funds
THE June CPI release has led to an easing in expectations of a further rate hike by the Reserve Bank of Australia (RBA) in August.
The data showed second quarter trimmed mean inflation rising by 0.8% taking the annual trimmed mean to 3.6%.
Consensus was for 0.9% and 3.7%. The result was also lower than the RBA’s May forecast of 3.8%.
Monthly headline inflation data was also released and fell 0.1% resulting in annual headline inflation of 3.8%. Consensus was for +0.2% and 4%.
The following graph shows the contribution by sector to annual inflation against the RBA’s 2 to 3% target band: –

Where does this leave the RBA ahead of its August meeting?
The market had ascribed around a 20% chance of a hike leading into today’s numbers and the cash rate peaking at 4.60% in early 2027.
Post the data, the market is saying zero chance of a hike next month and 50/50 on whether the RBA has finished tightening.
Prior to today’s release Governor Michele Bullock spoke at the Anika Foundation on the 28th July. Among the key points in her speech was that the housing market has been weaker than expected since the last set of forecasts in May.
The labour market has also been a bit softer than expected. Today’s monthly inflation data may have reflected some of the softening in housing extending into second round effects. Furniture prices for example fell over 5% in June and major household appliances dropped 2.5%.
Governor Bullock did also point out that the RBA retains a tightening bias and that “if it looked like inflation was not coming down, the board would have a difficult decision to make with respect to raising rates”.
With inflation below the RBA’s forecast, it is not facing a difficult decision in August. No change and see how the inflation data evolves.
Inflation does however remain above the RBA’s 2 to 3% target band. Governor Bullock pointed out that demand was still exceeding supply.
Should demand pick up, the RBA would expect inflationary pressure to resurface. To keep inflation under control requires an improvement in productivity, something that has been missing for a while.
A period of weaker growth that brings the economy back into balance is still required before the RBA will be comfortable that inflation is heading the right way.
Until that occurs, and with inflation still running 0.6% above their target band, it is likely that the tightening bias remains in the near term. A softening in the RBA’s language may occur when inflation starts moving back towards 3%.
Find out about
Pendal Managed Cash Fund
Steve Campbell, Head of Cash Strategies
If you’d like to hear more about how Pendal’s Income & Fixed Interest team is positioning for this environment, please contact us through your account manager by reply email.
About Steve Campbell and Pendal’s Income and Fixed Interest team
Steve Campbell is Pendal’s head of cash strategies. With a background in cash and dealing, Steve brings more than 20 years of financial markets experience to our institutional managed cash portfolio.
Find out more about Pendal’s cash funds:
Short Term Income Securities Fund
Pendal Stable Cash Plus Fund
Pendal Managed Cash Fund
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.
Cash might not be the “rock-star” of asset classes, but it does have a place in portfolios, explains Pendal’s head of cash strategies, STEVE CAMPBELL
- Cash provides liquidity and capital preservation
- Returns have improved over 2026
- Find out about Pendal’s cash funds
“Cash is always going to be the boring asset class. But with the Reserve Bank tightening monetary policy, cash is giving investors more income,” Campbell explains.
“And it provides investors with liquidity in their portfolios. Liquidity is first and foremost when it comes to cash.”
Higher benchmark interest rates have pushed cash returns higher in 2026, and Campbell says it has become a more appealing investment class for all investors.
But cash isn’t just about liquidity. It is also about capital preservation, he explains.
“All the assets we look at, in addition to being highly liquid, are also short dated in tenure.
“That helps ensure that investors’ capital is preserved.
“They need to be comfortable that they are getting their dollars back at the end of the day.”
Managing yield curve exposure
Pendal actively manages its yield curve exposure, which is important in 2026 given the uncertainty around monetary policy.
“The inflation environment can change. We had tailwinds in the economy over the second half of 2025,” Campbell says.
“Inflation picked up, household consumption was picking up because we had tax cuts. Real disposable household income was picking up as commodity prices came off.
“Then this year, tensions were rising in the Middle East.
“Inflation expectations picked up not only domestically but abroad, and at one point the market was pricing in a cash rate that may have been closer to 5 per cent.
“It is a quickly moving environment and investors need to be in liquid assets to make the most of those opportunities as and when they arise.”
Find out about
Pendal Managed Cash Fund
Steve Campbell, Head of Cash Strategies
If you’d like to hear more about how Pendal’s Income & Fixed Interest team is positioning for this environment, please contact us through your account manager by reply email.
About Steve Campbell and Pendal’s Income and Fixed Interest team
Steve Campbell is Pendal’s head of cash strategies. With a background in cash and dealing, Steve brings more than 20 years of financial markets experience to our institutional managed cash portfolio.
Find out more about Pendal’s cash funds:
Short Term Income Securities Fund
Pendal Stable Cash Plus Fund
Pendal Managed Cash Fund
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.
Cash and short-duration assets are playing an increasingly important role in diversified portfolios, explains Pendal head of cash strategies STEVE CAMPBELL
With inflation still above target and policy settings remaining tight, Pendal head of cash strategies Steve Campbell explains how cash can offer liquidity, capital preservation and a more attractive income profile than in previous years.
In this video podcast, Steve also discusses how active management across yield curve and credit exposures can help investors capture opportunities in a fast-moving rate environment.
Watch the full video to learn more
Listen to the audio only version
Find out about
Pendal Managed Cash Fund
Steve Campbell, Head of Cash Strategies
About Steve Campbell and Pendal’s Income and Fixed Interest team
Steve Campbell is Pendal’s head of cash strategies. With a background in cash and dealing, Steve brings more than 20 years of financial markets experience to our institutional managed cash portfolio.
Find out more about Pendal’s cash funds:
Short Term Income Securities Fund
Pendal Stable Cash Plus Fund
Pendal Managed Cash Fund
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.