
Here are the main factors driving the ASX this week, according to Pendal’s head of equities CRISPIN MURRAY. Reported by portfolio specialist Chris Adams
EQUITY markets remain supported by falling oil prices and associated reduction in bond yields, in anticipation of the peace deal announced this morning.
Last week saw the largest IPO in history as SpaceX listed on the NASDAQ at US$75.1 billion (the prior largest being Aramco at US$29.4 billion). It rose 19% on its first day of trading, putting it on 91x CY26 revenue.
This is an important sentiment indicator and, alongside the recent Alphabet capital raising, provides funding for the roll-out of AI compute infrastructure and Starlink.
An overhang of equity supply is leading to a consolidation in the US, with the S&P 500 up 0.7%.
We are also seeing rotation into some of the lagging sectors – notably REITs and Healthcare – which flowed through to Australia.
The S&P/ASX 300 gained 2.0% last week, led by rate sensitives (REITs +4.9%, consumer discretionary +7.9%) as the federal budget is increasingly seen as a handbrake on economic growth, reducing the need for further rate hikes.
We remain wary of domestic consumer plays as we expect the economy to slow, crimping earnings growth for that sector.
Market outlook
The market has been underpinned since the late-March low by:
- A resilient global economy despite the Iran war.
- Oil prices holding lower than feared.
- The acceleration of revenue growth at Anthropic, signalling that AI business models work.
- Upgraded investment in AI from hyperscalers.
- The SpaceX IPO, which highlighted the acceleration of its revenues.
- The combination of all these reflected in stronger-than-expected earnings growth in the US.
The combination of the continued strength in the market, the largest IPO in history at a punchy valuation, and the growing concentration of the US stock market has rekindled the debate as to whether we are near a market top.
Bears point to the historic precedent of equivalent levels of concentration at previous market peaks.
The 10 largest AI-related companies now comprise 41% of the S&P 500, whereas:
- The Nifty 50 peaked at 40% of the S&P 500 in the 1970s;
- Japan peaked at 44% of the MSCI AC World Index in the late 1980s; and the
- Tech and Telecom sectors reached 41% of the S&P 500 in the early 2000s.
Each ended in significant bear markets.
They also point to warning signs in longer-term valuation metrics. The Schiller P/E (the price over the average real earnings over 10 years) is near its previous high of the tech-wreck – as is the price/book ratio of the MSCI USA index.
The counter to this is that these measures do not capture the shift in earnings and returns on equity, particularly from tech sector.
For example:
- The S&P 500 is up ~9% in US dollar terms this calendar year, but 12-month forward EPS have been revised up 17%, which means the market’s P/E ratio has fallen despite the rise in the index.
- Returns-on-equity (ROE) for the S&P 500 have stepped-up in the last three years to a range of 20-22% (and are currently at the high end), compared to a range of 12 to 20% over the previous 30 years.
That step-up is linked to the mega-cap stocks, which are tapping into global customer bases and have strong market positions.
The factors driving higher ROEs include margin expansion (which reflects franchise quality and industry structure), lower corporate tax rates, increased leverage, and lower interest rates.
There has been some offset from lower asset turnover, however this arguably leads to an understatement of the increase because this is partly driven by the requirement to carry goodwill on balance sheets and higher cash holdings by the megacap stocks.
The key point is returns are higher and when this is mapped over the Schiller P/E it provides greater justification for current valuations than was the case in 1999.
AI return on investment
The key call then becomes the sustainability of these returns, which goes to the current debate about returns on hyperscaler capex. Capex is leading to deteriorating cashflows at the hyperscalers, which in turn drags on returns.
We note current estimates are for AI investment to be US$5.3 trillion from the four largest hyperscalers (Alphabet, Meta, Microsoft, Amazon) between 2025 to 2030 – a number that is trending higher.
The market currently believes the returns on that investment will flow through and cash flows will inflect higher from 2028, dwarfing those previously.
This call is the key to the market. If this plays out it underpins earnings and valuation rating; if not, then capex budgets will have to be cut with knock-on effects to earnings and rating.
The risks are:
- Use cases for AI not being sufficient to drive revenue expectations.
- Funding constraints limiting compute availability.
- Infrastructure constraints limiting compute (power, memory, planning approvals).
- Regulatory intervention slowing the development of models.
Regulatory intervention had been a lower-order issue but was elevated over the weekend as the US government ordered suspension of the Anthropic Fable 5 model’s availability to all foreign nationals. It is rumoured that Amazon discovered there was a way through the model’s guardrails which enabled its use in cyberattacks. Anthropic dispute that this was as serious as suggested.
SpaceX IPO
The SpaceX IPO is an important part of this debate as it provides further evidence of the acceleration of AI-related revenue growth.
The stock is the all-time largest IPO, both in terms of stock issued and market cap at listing (US$1.8 trillion).
It closed up 19% on its first day of trading, taking it to a US$2.1 trillion market cap and an EV/revenue of 91x.
Revenue is expected to grow 80%+ into 2027 and potentially to increase by 20-25x by 2030; from the current CY26 level of US$28 billion to US$450-500 billion.
The IPO valuation is not reliant on Starlink – although some estimate this will grow 7x between 2026 and 2030.
Instead, the bull case rests predominantly on growth in the terrestrial computing power of the company’s AI division, xAI.
Here, the company is forecasting 2 gigawatts (GW) by the end of 2026, 9-10GW by end-2029 and 13GW by end-2030.
How this gets monetised is an open debate, but the view is that if you build the compute the revenue will come.
In this vein, the implied return of US$50bn/GW of Anthropic’s recent leasing deal with SpaceX is unlikely to be replicated, but even a more sober US$20-30bn/GW across 8GW+, sold by 2028 at 35-40% margins, equates to ~US$100 billion of AI-sector EBIT.
Paths to monetisation include:
- Software (reinvesting in building out the Cursor coding product, plus healthcare and robotics tools enabled by Grok),
- Further neocloud-type deals, or
- A better consumer business.
In terms of a broadband product, the key is delivery of the first Starship orbital flight (previous flights have been suborbital). This can in turn facilitate bigger satellites, meaning materially faster speeds and a path from ~17 million to 30-40 million subscribers.
A direct-to-device service is the harder leg. It needs one of the top three telcos to fold (which seems unlikely) or purchase of a large swathe of spectrum. The latter is more likely as there is plenty of spectrum coming online via the One Big Beautiful Bill and SpaceX have said they’ll pay whatever it takes.
Testing of the Starship V3 rocket (the rapidly reusable spaceship) later in the year is likely to be a defining event. This is at the core of the move to build out Starlink and orbital compute.
Elon Musk has floated the idea of hourly launches – in the order of 8-9,000 per year. The market is assuming this is more likely to be 100-200 per annum by 2030.
We note the smaller Falcon 9 rocket is estimated to have 140 launches this year, while the new starship is said to have a payload of 10x the current Falcon.
The upshot is that the buy-side is getting to a US$2.5-3.0 trillion valuation, versus the current day one value of US$2.1 trillion.
This belief in the revenue trajectory highlights the market’s growth optimism, which underpins the broader market given 1) the overall weight of earnings relating to AI, and 2) the flow-on effects through investment spend on industrial companies and resources.
Find out about
Pendal Focus Australian Share Fund
Crispin Murray, Head of Equities
Iran conflict
Reporting this morning suggests a deal has been agreed on US President Donald Trump’s 80th birthday and 107 days after the conflict began.
The market appears confident that it can happen, noting statements from other Gulf countries and reports of Qatari officials going to Tehran to finalise details.
There have also been reports of loading in Iraqi ports for the first time in weeks, suggesting some production is slowly ramping up.
That said, we have been here before and there were a series of attacks through last week.
Oil continues to fall on the expectation of a resolution plus reports that the US has been covertly getting vessels through the Strait, at the rate of around 2-3 million barrels-per-day (bpd) for the last couple of weeks.
Reiterating previous notes, the market has been able to offset the loss of 20 million bpd via a combination of lower Chinese imports, inventory releases, some alternative routing, some flow through the Strait, and some demand destruction.
The latter has been disproportionately met through petrochemicals and some gasoil/ diesel reduction. Regionally, it has been in Asia and the Middle East.
Overall, the tail risk around this issue continues to fall.
There will likely be a long process to begin to restock the supply chain. It will take one to two months to ramp up production and we will see an extended period of strategic stock rebuilding.
All this is likely to hold oil prices around current levels for some time – but the ability to plan for this will improve confidence and likely be supportive for growth.
US macro and policy
May inflation data was largely in-line with expectations, with headline consumer price index (CPI) at 4.2% year/year and core CPI +2.9%.
Producer price index (PPI) was a bit higher than expected and will underpin higher personal consumption expenditures (PCE), likely around 3.5%.
There are three drivers for higher inflation:
- Tariffs – though this wave is rolling over.
- Energy prices – this is playing out as expected but will take time to wash through as companies catch up on passing on costs.
- AI investment-related inflation – relating to the sheer size of spend, the ongoing effect of this is uncertain.
The Fed has its first meeting under Chairman Kevin Warsh. With labour markets in decent shape and inflation not deteriorating – and with potential relief on energy prices – the Fed has time to wait to see how trends play out.
The key judgment on a six-month view is whether the economy can maintain good growth at current interest rates, which would suggest we are nearer to neutral than previously believed.
Markets
It is interesting to note the Mag-7 has been underperforming year-to-date. It is down ~2% versus the S&P 500 up ~9%, the equal weight S&P 500 up ~10%, and the small cap Russell 2000 index ~+18%.
This may reflect both the capital intensity increase as they spend more on capex and also the need to fund the SpaceX IPO and secondary issuance.
Total CYTD issuance in equities has accelerated, leading to a draw on the market.
If we factor in debt issuance, which is also up due to AI funding needs, 2026 has already surpassed 2025 levels.
Sentiment on software – which had been improving – has reversed significantly in the last two weeks driven by the combination of a return to semis (with software used as a funding source) and the launch of Anthropic’s Fable 5 model which renewed concerns around sustainability of traditional franchises.
We have seen early signs of a recovery in lagging sectors of the S&P 500 (REITs and Healthcare), perhaps reflecting a combination of a stabilisation in the outlook for rates, positioning (underheld) and valuation proving supportive.
This is important for our market, and we saw early signs of life in these sectors last week in Australia.
Australia had a good week led by REITs, staples and discretionary. This would indicate the market is getting more comfortable that, with the apparent softness in the economy, the RBA may not need to raise again, which would help rate sensitive sectors.
We think this may be premature optimism, as the RBA needs the consumer to slow meaningfully, to offset strong investment spending and population growth and bring inflation down.
So whether this needs more rate increases or not, the outcome would be for domestic earnings to be under some pressure.
Tech (-4.5%) was the underperformer, mirroring the drop in US software.
About Crispin Murray and the Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia. Crispin’s flagship Pendal Focus Australian Share Fund is a high-conviction equity fund with a two-decade track record across a range of market conditions.
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
Signs of a weakening Australian economy are giving markets growing confidence that the RBA’s next move may not be another hike. Pendal head of government bond strategies TIM HEXT explains
- Business conditions weak, capacity increasing
- Rate hike risks fade
- Find out about Pendal Government Bond Fund
- Browse Pendal’s fixed interest funds
WE HAVE talked numerous times about the richest source of timely information for the Australian economy – the NAB business survey.
It is the most forward-looking release in a sea of lagging indicators.
In fact, we incorporate a number of signals into our macroeconomic quantitative signals on the Australian economy.
Business Conditions Weak – Capacity Increasing
While very weak confidence has been evident for some months now in both the NAB business survey and Westpac consumer confidence, the two more powerful forward indicators are business conditions – what businesses are facing – and capacity utilisation.
After all inflation is essentially a capacity versus demand problem.
Numbers released on Tuesday show +3 for confidence and capacity utilisation at 81.9.
These are not doomsday numbers but as the graph below shows over the last 10 years the current numbers are weak or at least weakening.
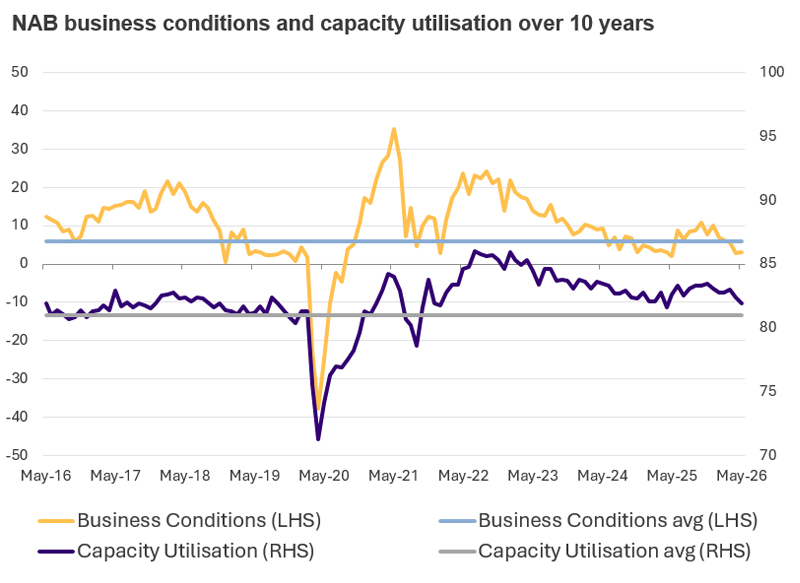
The +3 for conditions is a diffusion index. That is, the difference between optimistic and pessimistic firms. While still just positive, +6 is considered trend as businesses are generally optimistic.
The 81.9 for capacity utilisation is still just above trend of 81 but down from recent years.
The RBA would welcome this development, but anything below 80 would set off some warning signals, as seen from the chart above
Implications for rates
Now markets don’t focus nearly enough on the NAB business survey, remaining more obsessed with the volatile and short-term unreliable employment numbers.
However, they did not go unnoticed by NAB themselves who have removed rate hikes from their forecasts and now are calling for cuts in H1 2027. This is consistent with our view.
In the days since, despite volatile oil markets, the short end in Australia have caught a bid and at the time of writing three-year bonds are again pushing down towards the cash rates.
Peak cash is now less than one more hike and an August hike is down to only a one-third chance.
It may be too early to call for now, but comfort with Australian rates is improving despite expected hikes offshore. Australia for once has been ahead of, not behind, the global game.
Find out about
Pendal Government Bond Fund
Tim Hext, Head of Government Bond Strategies
If you’d like to hear more about how Pendal’s Income & Fixed Interest team is positioning for this environment, please contact us through our accounts team
About Tim Hext and Pendal’s Income & Fixed Interest boutique
Tim Hext is a Pendal portfolio manager and head of government bond strategies in our Income and Fixed Interest team.
Tim has extensive experience in banking, financial markets and funding including senior positions with NSW Treasury Corporation (TCorp), Westpac Treasury, Commonwealth Bank of Australia, Deutsche Bank, Bain & Co and Swiss Bank Corporation.
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.
Find out more about Pendal’s fixed interest strategies here
About Pendal
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
In 2023, Pendal became part of Perpetual Limited (ASX:PPT), bringing together two of Australia’s most respected active asset management brands to create a global leader in multi-boutique asset management with autonomous, world-class investment capabilities and a growing leadership position in ESG.
AI is creating a new wave of investment opportunities on the ASX beyond the obvious winners. Pendal MidCap Fund portfolio manager BRENTON SAUNDERS highlights the niche midcap companies benefitting from the next phase of AI growth
- AI is opening new midcap opportunities
- Neoclouds offer scalable, lower-risk AI exposure
- Find out more about the Pendal MidCap fund
THE first wave of AI investing has centred on obvious beneficiaries such as data centre operators, semiconductor manufacturers and the contractors building the infrastructure behind them.
But a new group of specialised providers is beginning to emerge, offering investors another way to gain exposure to the theme on the ASX.
Among them are neoclouds, niche companies offering cloud computing services tailored to AI workloads.
Rather than building and owning data centres, these businesses lease capacity in existing facilities and install their own graphics processing units (GPUs) and central processing units (CPUs) to support AI computing.
They then sell that computing power to customers ranging from individual users to software developers and large enterprises.
The model is gaining credibility. US technology giant Nvidia has begun partnering with some of these smaller providers as it backs the next generation of hyperscale AI cloud solutions.
One example is Sharon AI, an Australian-founded company listed on the NASDAQ and backed by US capital. It is also considering a dual listing in Australia and has partnered with Nvidia.
Queensland-based network-as-a-service provider Megaport (ASX: MP1), meanwhile, moved into the space through its acquisition of Latitude.sh in November 2025.
Megaport said the deal combined its connectivity platform with Latitude.sh’s high-performance compute capabilities to support AI workloads globally.
Pendal MidCap Fund holds a position in Megaport.
Brenton Saunders, portfolio manager of Pendal MidCap Fund, says the neocloud model offers a less capital-intensive way to access the AI thematic than building data centres from scratch.
“You don’t carry all the construction risk or the risk of capital costs blowing out while you’re building these assets, because it takes years to build them,” he says.
“You have a much more defined return profile. These businesses can pay themselves back within two or three years.
“For me, it’s a preferable way to play the AI thematic domestically.”
AI token advantage
Another fast-growing part of the AI thematic is token usage.
Tokens are the small units of data AI systems process during training and inference, making them a useful gauge of demand for computing power.
Google, for example, says it is now processing more than 3.2 quadrillion tokens a month, up from 9.7 trillion two years ago, underscoring the pace at which AI usage is accelerating. Google CEO Sundar Pichai shared the figures at Google I/O 2026.
“Estimates for token usage continue to rise exponentially,” Saunders says.
“The number of tokens we thought we would need six months ago versus what we may require in a year or two has already increased 10 to 15 times in just six months, as corporates and consumers adopt AI more quickly.
“That leaves a very powerful backdrop for the theme.”
Find out about
Pendal MidCap Fund
Brenton Saunders, Portfolio Manager
Why volatility requires balance
With markets still being shaped by macroeconomic and geopolitical crosscurrents, Saunders says balance is critical in periods of volatility and sector rotation.
“You don’t want to expose yourself to big directional bets tied to geopolitical events, the oil price or inflation,” he says.
“We spend a lot of time intentionally designing portfolios that won’t simply be dragged one way or another by those macro events. That becomes especially important during major market selloffs.”
For Saunders, the task is to identify the stronger companies within that backdrop through detailed, bottom-up research.
He says he is looking for businesses with sound capital structures, manageable debt levels and strong management teams focused on delivering stronger shareholder returns.
“It’s like a moth to the flame at the moment,” Saunders says, noting that investor enthusiasm has quickly shifted from areas such as gold to AI.
“AI has been rallying in the US for some time, but that momentum is now building more meaningfully in Australia.”
About Brenton Saunders and Pendal MidCap Fund
Brenton is a portfolio manager with Pendal’s Australian equities team. He manages Pendal MidCap Fund, drawing on more than 25 years of expertise. He is a member of the CFA Institute.
Pendal MidCap Fund features 40-60 Australian midcap shares. The fund leverages insights and experience gained from Pendal’s access to senior executives and directors at ASX-listed companies. Pendal operates one of Australia’s biggest Aussie equities teams under the experienced leadership of Crispin Murray.
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
Here are the main factors driving Australian equities this week, according to investment analyst JACK GABB. Reported by head investment specialist Chris Adams
THE S&P 500 came close to notching a 10th consecutive weekly gain, and its best run since 1985, before a tech-led sell-off triggered sharp falls in risk assets on Friday.
The catalyst was surging US jobs data, sending 30-year Treasury yields back to 5% and implied rates up over 0.1%.
However, the set up to Friday’s price action was undoubtedly influenced by crowded positioning and the run-up in prices.
The Friday sell-off saw the S&P 500 close down 2.6% for the week, while the Nasdaq finished down 4.7%. Tech and Consumer Discretionary stocks led the US market lower, with Energy and Healthcare better.
The S&P/ASX 300 also ended last week lower, down 1.2%, but led by Real Estate, Materials and Financials. Tech was stronger for the week.
Yields moved higher across the board, with rate expectations rising.
Commodities were hit hard with iron ore losing 6.3% and lithium down 5.5%. Gold fell 4.9%.
Oil bucked the trend as a more permanent solution to the Iran conflict remains elusive. Brent crude rose 1.1% for the week (ex. oil on little/no Iran progress).
Crypto currencies were savaged, with Bitcoin down 16.8% and back below the level it was at when Trump was re-elected.
The US Dollar ended the week stronger despite another warning on the debt ceiling.
This week will see releases on Australian consumer and business confidence as well as data on consumer inflation expectations.
US CPI data will also be closely watched given global inflation expectations.
Warning signs or just crowded positioning?
The global economy is growing strongly at ~3% p.a. (~3.5% pre the Iran conflict).
Large fiscal impulses in the US (running a ~6% budget deficit) and China (~10% deficit) are supportive, and capex is broadening geographically and by sector, as seen in improving PMI data.
This is all constructive for markets.
However, there are also those becoming cautious on the AI trade.
As one commentator put it last week: “When they write the history of the AI bubble 2022-2027, the issuance by Google of $85 billion of stock in early June 2026 will be one red line that was crossed.”
Jensen Huang’s call that Marvell Technology “will be the next trillion-dollar company” saw it add US$51 billion to its market cap in the week, despite giving up US$46 billion of gains on Friday. We are in an era where such calls are seemingly routine.
AI euphoria abounds and positioning is crowded. Commodity trading advisers (CTAs) – systematic strategies that track price momentum and provide a good indicator of market positioning – have been very long equities.
But last week there were a number of warning signs flagged by those looking to call the top of the AI trade:
- Growing AI costs. Uber and Walmart were the latest companies to limit internal AI usage given rising costs.es the market is expecting a significant decline in growth expectations.
- IPOs galore. SpaceX will soon complete its US$75 billion raise at a US$1.8 trillion valuation (its Australia retail offering closes Wednesday). Anthropic (having recently raised US$65 billion at a US$965 billion valuation) filed to IPO last week and OpenAI is likely to follow soon (it raised US$122 billion earlier this year at a US$852 billion valuation).
- Ever-increasing capex; equity raises. While a huge part of Alphabet’s raise will go to meeting tax obligations associated with vesting of employee equity awards (US$30 billion), it will also increase spending to scale AI infrastructure and global compute. The Financial Times also reported Meta is considering following suit and raising tens of billions.
- Overly high expectations. Broadcom announced AI semiconductor revenue will be US$16 billion in its fiscal Q3, well below consensus expectations of US$17.2 billion.
US macro and policy
Nonfarm payrolls triggered much of Friday’s price action, with the May data coming in at +172,000, versus +88,000 expected, mostly driven by unexpected hiring in Local Government, Leisure & Hospitality and Healthcare.
March and April were also revised higher, with the data raising the risk that a tightening labour market could drive up wages and add to upward pressure on rates.
While the JOLTS data also surprised higher earlier in the week (7.6 million job openings versus 6.9 million expected and 6.9 million prior), other data was less clear cut.
For example, the unemployment rate for May was in-line with consensus at 4.3% and average hourly earnings were as expected at 3.4%.
The former is key for the US Federal Reserve, with a rate above 4.2% unlikely to cause much concern despite stronger payrolls.
The risk is that payrolls remain strong, driving down unemployment and seeing a tighter jobs market stoke inflation.
While this is not consensus, the market nevertheless moved up rate hike expectations, which are now pricing in 1.1 hikes by December, versus only 0.57 last week.
We note that payroll data is volatile, subject to revision and the number of jobs is not reflected in the hiring rate implied by the JOLTS data.
In addition, consumer surveys show less confidence in finding a job and the most recent National Federation of Independent Business (NFIB) small business survey recorded a multi-year low for firm hiring plans.
There is a risk that the unemployment rate falls below CPI (which consensus expects to be 4.2%), which would be only the seventh time since 1960.
Years when inflation runs close to or above unemployment have historically seen Fed hikes and poor equity returns.
US debt
The US Treasury Department may need to use extraordinary measures as early as next year to avoid a national debt default.
According to a report by the Bipartisan Policy Centre, absent congressional action, the US will mostly likely reach the debt limit once again sometime between late winter and mid-summer 2027.
That is despite raising the ceiling US$5 trillion last year (to US$41.1 trillion). More than half of that has already been used up.
This likely comes into even sharper focus depending on the outcome of November’s midterms. We note gold rallied US$2,000/oz in the six months after last year’s ceiling raise.
Australia macro and policy
GDP
GDP grew 0.3% quarter/quarter in Q1 2026 – below consensus expectations of 0.4% and much slower than the previous quarter’s +0.9% (revised from +0.8%) – with more subdued consumer spending offset by booming data centre spend.
Growth since Q1 last year is still 2.5%, but 2026 will be materially lower (<2% versus global GDP of 3.0%, or 3.5% pre-Iran) as the impact from the Iran conflict, proposed tax changes and higher rates are felt.
According to the ABS, more modest growth quarter/quarter reflected subdued household and government consumption as well as adverse weather affecting mining exports.
Private sector investment in data centre machinery and equipment was the largest contributor to growth, however at least half of this is imported, hence there was a large corresponding detraction in net trade.
The key trend here is that capex is continuing to outperform consumption, with domestic final demand adding 1% to GDP growth, led by private investment at 0.7% and household spending at 0.3%.
Private investment grew 3.6%, with machinery and equipment up 16.3%. This mostly reflects increased investment in data centres.
While on its own the step-up in capex is inflationary, proportions matter here; capex excluding housing is ~20% of the economy while consumption plus housing is ~60%.
At the margin this increases how much the RBA needs the consumer to slow to be confident that aggregate demand is weakening, particularly given persistent high public sector spending.
Overall consumption rose 0.5%, contributing 0.3% to GDP.
Most of the increase was down to rising spending on essentials (+0.8%) with electricity, gas and other fuels up 11.7% as the energy rebates ended.
Discretionary spending rose 0.1%, with higher interest rates and fuel costs driving more cautious behaviour across most categories. Given recent tax changes, falling house prices and potentially one more rate hike this year, a further deceleration in domestic demand appears likely.
Find out about
Pendal Focus Australian Share Fund
Crispin Murray, Head of Equities
Wages
The Fair Work Commission announced a 4.75% increase to modern award wage rates – at the top end of expectations, but in-line with the RBA’s forecast for headline inflation of 4.8% in FY26.
However, combined with other structural changes, the total lift in award wages is seen at ~5.2%.
This affects almost 2.8 million workers, or 21% of the labour force, but only 11.2% of the national wage bill.
As such, while inflationary and likely to add to pressure on the RBA, which had seen wages rising 3.2% through FY27, it is not hugely significant.
However, early forecasts for next year’s increase are for an additional 3.8%, well ahead of the RBA’s forecast for CPI at 2.4%.
House prices
Proposed tax changes are expected to reshape the housing market, compounding the impact of recent rate hikes.
Estimates for price declines this year range from low single digit to 10% (versus the Treasury at 2%), with turnover seen down as much as 20%.
This represents a headwind for the major banks given the likely slowdown in credit growth.
If investor credit growth slows to 0% (similar to 2019-21), overall housing credit growth would slow from ~7% to 4%, not far from the all-time low of 3% in 2019 – a period when banks underperformed the market by up to 20%.
Consensus currently estimates housing credit growth slowing from 7% to around 4-5%, but any additional rate hikes or material house price falls would likely trigger further revisions.
Feedback from Westpac during the week was that mortgage demand is rolling over faster than many expected, with applications down ~25% quarter/quarter in Q1 and softer again post-period, while investor flow share has fallen from ~40% to ~30%.
Around one-third of investor loans are linked to negative gearing benefits.
Interest rates
The market shifted from pricing an additional 0.71 hikes this year to 0.92 over the course of last week. Despite slowing growth, inflation is still seen as too high.
No change is expected at the meeting later this month, albeit the tone is expected to be hawkish.
This may see expectations for a hike in August increase, with some economists already predicting an increase. They argue that while housing related data is the key near-term variable, the data will not have sufficiently weakened in time to hold off a further raise.
However, hiking into a slowing economy and slowing housing market is clearly higher risk, thus the RBA will likely need further evidence of inflation before then.
Board member Professor Ian Harper warned market measures of inflation expectations have taken an uptick and that strong action is needed to keep inflation expectations anchored.
Governor Michele Bullock noted the Iran conflict is creating a highly uncertain environment that could easily contribute to even higher global and domestic inflation than anticipated.
The conflict is expected to weigh modestly on growth in Australia this year, she said, noting that “this would worsen the trade-off between inflation and economic activity”.
But she does not see stagflation as a concern for Australia at this point.
She also sees the risk of inflationary expectations being embedded in the economy as low.
“Longer term inflation expectations are remaining anchored around the target (2.5%),” she said, “so I’d say the risk is low at this point. But short-term expectations have definitely risen, and that’s to be expected.”
Commodities
Last week was a volatile one for commodities as Iran headlines continued to dominate.
Oil finished up 1.1% for the week, driving down gold, which has been highly (inversely) correlated to movements in the price.
Bitcoin plunged on liquidations and a selldown by the dominant corporate buyer.
Elsewhere there was also a reasonable move down in iron ore, despite no fall in freight rates, while lithium gave up some of its recent gains on rebounding supply expectations.
On the currency side, the yen is worth a mention given it has risen above 160 (USD:JPY), which has been seen as a key level beyond which the Bank of Japan may intervene to prevent further weakening.
In the past, this has seen the country sell US Treasuries to fund the spending, pushing up yields.
Markets
The ASX has benefitted in 2026 from significant earnings upgrades across Mining and Energy stocks. This has seen Material’s ASX200 weighting climb 4.1% year to date (to 27.2%), with Energy +0.9% (to 4.5%).
At the other end of the spectrum, Heath Care is down 2.1%, Financials and Consumer Discretionary down 0.9% and Real Estate down 0.8%.
However, with Energy and Materials earnings momentum rolling off and the domestic economy slowing, overall earnings headwinds are building.
While we do not have a negative view of commodities, in many instances share prices have run ahead of underlying earnings momentum. For example, BHP has been the single largest contributor to ASX gains year to date, however, the recent fall in iron ore is driving lower mark-to-market earnings.
This may challenge recent gains, even as some commentators seek to portray BHP as an AI/data centre play.
About Jack Gabb and Pendal Focus Australian Share Fund
Jack is an investment analyst with Pendal’s Australian equities team. He has more than 14 years of industry experience across European, Canadian and Australian markets.
Prior to joining Pendal, Jack worked at Bank of America Merrill Lynch where he co-led the firm’s research coverage of Australian mining companies.
Pendal’s Focus Australian Share Fund has an 18-year track record across varying market conditions. It features our highest conviction ideas and drives alpha from stock insight over style or thematic exposures.
The fund is led by Pendal’s head of equities, Crispin Murray. Crispin has more than 27 years of investment experience and leads one of the largest equities teams in Australia.
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
The transition to renewable electricity continues to be one of the most pressing global challenges.
- Electricity generation is a large source of global emissions
- Green bonds support net zero through cleaner electricity
- Find out more about Pendal’s Responsible Investing capabilities
Around two thirds of global emissions come from electricity generation.
Renewables and low carbon energy is a fundamental requirement in the transition to a net zero world.
Regnan Credit Impact Trust and Pendal Sustainable Australian Fixed Interest Fund invested in an AUD green bond by the Canada Pension Plan Investment Board (CPP Investments).
CPP Investments is controlled by the Canadian government and is one of the largest pension funds in the world.
It issued its first green bond in 2018[1] and continues to raise funds for investments in renewable energy and energy efficiency, low carbon and clean transportation and green buildings.
In the past, these types of bonds have invested in renewable energy projects across the world.
This includes two wind parks in northeastern Brazil run by Votorantim Energia, six wind and solar power projects in Canada operated by Cordelio Power, and three offshore wind farms in France that are under construction by Maple Power.
We anticipate this green bond to invest in similar types of projects.
A component of investing in this green bond includes reporting of environmental impact indicators associated with underlying projects.
This includes renewable energy generated per year, emissions avoided, waste reused or recycled, and reduction in air pollutants due to implementing low carbon and clean transportation.
[1] CPPIP 2023 Green Bond Impact Report 2023
Find out about
Regnan Credit Impact Trust
George Bishay, Head of Credit and Sustainable Strategies
About George Bishay and Pendal
George Bishay is Pendal’s head of credit and sustainable strategies. George’s investment management career spans over 30 years with Pendal and its predecessor firms.
He has also worked across numerous fixed income, credit and money market portfolios in portfolio management, credit analysis and dealing roles for 27 years.
In 2019 George was awarded the Alpha Manager status by Money Management publisher FE fundinfo.
Find out more about Pendal’s fixed interest strategies here
Pendal is an Australia-based investment management business focused on delivering superior returns for our clients through active management.
Investment in Housing Australia bonds is helping unlock cheaper financing for much-needed housing projects.
- Backing social housing where it’s needed most
- Turning bond investments into real outcomes
- Find out more about Pendal’s Responsible Investing capabilities
Regnan Credit Impact Trust and Pendal Sustainable Australian Fixed Interest Fund continue to invest in social and sustainability bonds from Housing Australia.
These support the construction and growth of social and affordable housing across Australia by providing community housing providers access to cheaper financing.
Examples of the types of projects supported through these bonds include the delivery of 365 social and affordable housing units by Bridge Housing in NSW[1].
This includes properties in Glebe which target First Nations people on low to moderate incomes, Petersham and Leichardt for tenants who have previously been homeless, and South Granville and Westmead where there is a mix between social and affordable housing.
Another example is in Victoria through community housing provider Haven Home Safe, which is focused on the delivery of social housing through townhouses and apartments in Melbourne, Ballarat and Bendigo.
The target cohort for these 113 properties are over 55s[2], those requiring specialist disability accommodation, youth and women, and those at risk of homelessness.
Regnan Credit Impact Trust and Pendal Sustainable Australian Fixed Interest Fund continue to support the delivery of projects like this through investments in Housing Australia.
These projects have life changing consequences for people like Andy, who was sleeping in a friend’s car after becoming homeless.
After being placed in temporary accommodation for three months to develop a rental history, Andy was then connected with a case worker from a community housing provider of services to those who have been sleeping rough.
He was able to rent in one of the buildings that were part funded by Housing Australia bonds.
With the support of the community housing provider, Andy says “I have a lounge, I have nice clothes… my children are back in my life. I am happy to be here, and I wouldn’t have it any other way.”[3]
[1] https://bridgehousing.org.au/developments/
[2] https://havenhomesafe.org.au/about/what-we-do/
[3] Housing Australia Case Study, October 2024
Find out about
Pendal Sustainable
Australian Fixed Interest Fund
George Bishay, Head of Credit and Sustainable Strategies
About George Bishay and Pendal
George Bishay is Pendal’s head of credit and sustainable strategies. George’s investment management career spans over 30 years with Pendal and its predecessor firms.
He has also worked across numerous fixed income, credit and money market portfolios in portfolio management, credit analysis and dealing roles for 27 years.
In 2019 George was awarded the Alpha Manager status by Money Management publisher FE fundinfo.
Find out more about Pendal’s fixed interest strategies here
Pendal is an Australia-based investment management business focused on delivering superior returns for our clients through active management.
Wages are up, growth is down and Australia is struggling. Developments this week only change the current economic narrative at the margin. Pendal head of government bond strategies TIM HEXT explains
- Find out about Pendal Government Bond Fund
- Browse Pendal’s fixed interest funds
Wages up
ON TUESDAY the Fair Work Commission (FWC) Annual Wage Review awarded an increase of 4.75% in award wages to 21.1% of the workforce, around 2.8 million workers.
As many of this cohort are casual or part time this impacts only 11.2% of the overall wage pool. Markets had expected something nearer 4% to 4.5%.
The RBA will be disappointed by this outcome, although they will not directly comment on it.
We estimate that this should add 0.2% to the closely followed Wage Price Index (WPI), although probably 0.1% was captured in the RBA’s recent WPI forecast of 3.2%.
Interestingly the FWC decision quoted the RBA headline inflation forecast of 4.8% for the end of June as its justification for the rise.
This forecast will likely prove too high given recent fuel price falls, so perhaps an inadvertent own goal from the RBA.
Growth down
On Wednesday the National Accounts for the March quarter were released. As always, the two-month delay makes it less useful as a pointy end indicator, but the breadth of information is very powerful.
Overall, the economy grew at only 0.3% in Q1, down from a revised 0.9% in Q4 2025. On a per capita basis we are again going backwards (-0.1%).
The public sector has stepped back from the major engine of growth to being flat in the quarter. Household consumption grew by 0.5%, near average. The only bright spot is the data centre impacted business investment that grew by 5.7% in a quarter, alone adding 0.7% to GDP.
Keep in mind the first two months of the quarter hadn’t been impacted by the Middle East developments that hit confidence. The economy was already struggling, hit by rate hikes and higher inflation.
Australia struggling
The biggest take from today’s data and other recent data is the rapidly changing external account position of Australia. This dragged 0.8% from growth. This is volume not revenue based.
Part of this was weather impacting our commodity exports. However, a growing part is the changing trade position, which is very interesting.
Australia has had a trade surplus since 2017, leaving the ‘banana republic’ days behind us.
The current account also includes our net interest payments, which detracts from the current account position as we are a net debtor to the tune of around $1.2 trillion.
However, by late 2018 even our current account was in surplus. Australia for probably the first time in history was an exporter of capital to the world.

Now in 2026 commodity export volumes have flatlined and a boom in imports, led by technology for data centres, has now seen even the trade position slip back into deficit.
This is likely to continue for some time, despite BHP’s (ASX:BHP) share price suggesting blue skies ahead.
If commodity prices significantly fall, the cracks could become a crisis of sorts for Australia, as we collectively increasingly spend our wealth on imports – think not just technology but new cars, overseas holidays and fuel.
By volume, exports are up 10% over the last decade but imports are up 35%. Only a favourable term of trade shift has helped somewhat prop up our position.
What does this mean for markets?
We will save a more in depth look at what artificial intelligence and data centres mean for the economy and rates for another time.
None of this week’s data on its own will tip the RBA into action or no action in August.
However, the data does play into a difficult period ahead for the Australian economy, as workers try to keep pace with inflation but the economy is yet to see the dividends of all the technology related infrastructure spend.
Find out about
Pendal Government Bond Fund
Tim Hext, Head of Government Bond Strategies
If you’d like to hear more about how Pendal’s Income & Fixed Interest team is positioning for this environment, please contact us through our accounts team
About Tim Hext and Pendal’s Income & Fixed Interest boutique
Tim Hext is a Pendal portfolio manager and head of government bond strategies in our Income and Fixed Interest team.
Tim has extensive experience in banking, financial markets and funding including senior positions with NSW Treasury Corporation (TCorp), Westpac Treasury, Commonwealth Bank of Australia, Deutsche Bank, Bain & Co and Swiss Bank Corporation.
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.
Find out more about Pendal’s fixed interest strategies here
About Pendal
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
In 2023, Pendal became part of Perpetual Limited (ASX:PPT), bringing together two of Australia’s most respected active asset management brands to create a global leader in multi-boutique asset management with autonomous, world-class investment capabilities and a growing leadership position in ESG.
Here are the main factors driving the ASX this week, according to Pendal’s head of equities CRISPIN MURRAY. Reported by portfolio specialist Chris Adams
EQUITY markets continue to rally, led by the US (S&P 500 +1.4% last week) as AI-related investment spending flows through to stronger earnings.
The breadth of winners is widening in the US. A strong update from Dell (NYSE:DELL) reinforced the enterprise hardware story, while a similarly well-received quarterly from Snowflake (NYSE:SNOW) showed some software stocks are benefitting from AI, as companies seek a control or orchestration layer.
Oil prices continued to fall last week (Brent crude -11.1%). This was due largely to the recurring prospect of a ceasefire and reopening of the Strait of Hormuz, as well as better availability of oil and fuel as Chinese imports slow and reserves are released.
The latter tailwind appears to be sustainable for a couple of months.
The fall in oil – combined with benign inflation data – led to lower bond yields which helped the interest-rate-sensitive part of the equity market.
The S&P/ASX 300 rose 0.9%, but still lags the US by 22% quarter-to-date due to a relative lack of semiconductor and other AI-related exposures.
Reasonable domestic consumer price index (CPI) data released last week saw lower expectations for further rate hikes and drove a rally in discretionary stocks.
The domestic tech sector continues to recover, outperforming the S&P/ASX 300 by 11.1% quarter-to-date, but still lags the broader market by 18% this year.
Bank stocks continue to lag, underperforming the market 5.5% in May.
Iran war outlook
A deal to reopen the Strait remains elusive for now.
The key issues appear to be:
- The timing of Tehran’s access to frozen funds relative to the Strait’s re-opening
- Wording around some acknowledgement of Iran’s influence over the Strait
- The framework for discussions on enriched uranium
One factor for the US is obtaining an agreement that’s not perceived to concede too much – particularly relative to the Obama-era Iran deal.
There is also disagreement over the number of ships now transiting the Strait, with some suggesting it is opening up.
Iran’s Islamic Revolutionary Guard Corps claimed there were 20 to 35 daily transits last week (compared to 95 pre-war).
But the International Monetary Fund’s PortWatch noted only four per day in the week to May 24 and Lloyd’s of London reported on May 26 that traffic was down by almost half compared to the previous week.
It may be that the IRGC numbers relate to permits issued (rather than actual transits) and may include Iranian traffic heading to other Iranian ports, which is not relevant to global fuel supply.
The conclusion is there is no tangible evidence that supply is improving.
Despite this, oil and fuel prices continue to fall.
This is more than just market optimism about a deal; it reflects the reality that there is ample supply, for now.
The drivers of this are:
- Chinese oil imports are estimated to have dropped from 12 million to 7 million barrels per day (bpd) in May. Some of this is demand reduction which is estimated at 9%, or about 1.5m bpd. The remainder is a draw-down on strategic reserves. Chinese demand has also fallen with a pivot to coal and renewables, adoption of electric vehicles (now estimated at a third of China’s transport fleet) and a switch from air travel to trains.
- Global demand loss for May is estimated at about 5.6m bpd (compared to 4.3m in April) or about 4.1m bpd excluding China. Of this, about 3m bpd is from petrochemical demand (eg plastics, textiles, fertilisers), 600k bpd from fuel oil and 500k bpd from jet fuel.
- US oil exports have increased by 2 million to 3 million bpd.
- Strategic petroleum reserves (SPR) are drawing down 2-3m bpd.
- There has been growth in other supply and commercial stock draw-downs
So if the starting point is a shortfall of 15 million to 16 million bpd (net of the flow through alternative pipelines), then the factors above are currently plugging that gap and can plausibly continue to do so for another two months.
China can probably sustain reduced demand for an extended period.
This means the key swing point would be the continued SPR draw-downs in other countries and US commercial stocks running too low.
If these factors reached a tipping point, the market would need higher prices to choke off another 3m bpd of demand, which would start getting into more price-inelastic areas like gasoline and diesel.
If anything, there are some short-term oil surpluses for now, since refiners are wary of bidding for product with the risk of a deal.
This has led to further falls in fuel prices.
For example jet fuel, having surged from US$90 to $US220 a barrel in the conflict’s initial stages, has fallen back below US$130.
AI themes
Two quarterly results in the US last week fuelled a broadening of the AI theme:
- Dell (+33%): The computer hardware-maker’s revenues were 23% above expectations and up 88% year-on-year, driven by AI-optimised server revenue (+757% yearly) to US$16 billion. Orders were 1.5x recognised revenue with the backlog rising faster than they could ship. AI customers were up 50% in six months. Supply remains constrained, particularly in memory. Guidance for FY27 is for 50% revenue growth. This highlights the demand from enterprise to upgrade infrastructure.
- Snowflake (+36%): The cloud-based platform, which helps organisations store, analyse and share massive amounts of data, had been caught up in the “SAASpocalypse”, falling 56% from November to April. It reported its second quarter of accelerating year/year revenues from 26% in Q3 CY25, to 30% in Q4 CY25 and now 34% in Q1 CY26, with net revenue retention (a measure which excludes new sales and indicates if existing customer base is growing or shrinking) of 126%. Customers using AI are looking to Snowflake for their intelligence layer – effectively a control plane across the AI agents. This supports the thesis that agents run on top of the Snowflake’s software rather than disintermediate their data warehouse. Snowflake guided to FY27 product revenue growth of 31% (up from 27%) and raised both margin and free cash flow margin guidance.
The key observation here is an acceleration of spending at both ends of the AI stack – in enterprise hardware (servers) and applications (software) – as companies position themselves to integrate AI.
This builds on recent comments from US network equipment maker Cisco Systems that enterprises need to invest in infrastructure to be in a position to use agentic AI.
Confidence in demand is increasing and there are supply constraints that help support margin for companies involved in the build-out of this hardware.
Find out about
Pendal Focus Australian Share Fund
Crispin Murray, Head of Equities
It’s still true that some software businesses facing structural threats, but the market is shifting away from treating the issue in an indiscriminate way.
This is helping underpin a rally in semiconductors – and now a broader rebound with the iShares Expanded Tech Software Sector ETF breaking back above its technical resistance level.
US data
Overall, data is signalling a US economy that is holding up well, underpinned by a resilient consumer and strong investment spending.
Inflation remains stubbornly high, but is not getting worse.
Inflation
The latest personal consumption expenditures (PCE) data – a measure of inflation – was in-line with expectations at a headline level and slightly below expectations on a core basis.
The core measure is still running at 3.3% year-on-year, with headline at 3.8%.
This print, combined with the fall in oil prices, helped two-year US Treasury yields drop 12 basis points.
The US Fed’s challenge is that the absolute number remains stubbornly high at above 3%, while its target is 2%.
There are reasons to believe the current inflation rate may be overstated, including:
- Some tariff effects remain
- There is a reasonable case that IT/software inflation is being materially overstated, due to AI spending and the subsequent uplift in product quality/value to customer not being reflected in pricing.
New Fed chair Kevin Warsh believes the trimmed mean PCE is a better measure of inflation that the Core. The former is running at 2.33%.
However even using this different perspective, inflation data is still running above target.
And when you look at the underlying components, goods are deteriorating – which reflects more-consolidated industries – while services are stable but have not yet begun to fall.
Given labour market trends are improving, and we are in an environment where inflation risk is perceived as being higher, it’s difficult to see how the Fed could make a case for easing.
Spending
US real disposable income and spending data suggest consumption is holding up well, despite some pressure on disposable income – and this is supported by a fall in the savings rate.
Consumption rose 0.1% monthly but prior months were revised up leading to the three-month number picking up.
Real wages were softer, which led to disposable income falling 0-0.5% month/month and -0.3% on a rolling three-month basis. The savings rate fell to 2.6%, its lowest point since December 2022.
This can be read two ways.
Either consumption is unsustainable, or other factors such as consumer wealth, expectation the fuel price shock will prove temporary, and confidence in employment are all underpinning consumer spending.
With recent falls in US petrol prices, there are some signs of relief supporting resilient consumer demand.
Australian economy
April’s CPI inflation data was better-than-expected at a headline level, prompting optimism that the RBA may not need to raise rates again. This drove a 9bp rally in the 2-year government bond.
- Headline CPI rose 0.4% month/month versus 0.6% expected. The annual rate was 4.2% versus 4.3% expected and 4.6% in March. This was helped by the drop in fuel excise.
- The trimmed-mean measure was 3.4%, in line with forecasts. Construction costs surprised to the upside, but international travel was less than forecast.
- The 3-month rate is decelerating marginally and may reflect a loosening of the labour market.
The issue for the RBA is that non-discretionary items (electricity, rents, insurance, education and health) is running at 5.1%. A number of these are structural, such as the impact of the housing shortage.
The RBA needs the economy to run below trend for a period and that probably equates to 1.5% GDP growth. The challenge is while the consumer may be slowing, data indicates the investment side of the economy is accelerating.
Household spending fell 1.1% month/month in April, below forecast, and is +4.9% year/year (versus 5.8% expected).
April’s drop-off came after two strong months and takes the underlying rate back to around 5% which was where it had been. The main cause was a fall in air travel due to the Iran war. The three-month run rate is at 3.6% annualised.
Offsetting this was a boom in investment spending. Private cap-ex spending rose 6.5% quarter/quarter versus 1.2% expected, driven by a surge in plant & equipment spending (+18% quarter/quarter, 31% year/year).
This was driven by non-mining sectors (+8.8%), specifically tech related spend (+96% quarter/quarter and 190% year/year) off the back of an acceleration in data centre spending. There was an offset in building and structures, down -3.8%.
The overall impact is hard to determine, as there is an offset in that at least 50% of data centre investment goes into imported items, although that component is back-ended.
So the net effect on GDP is not as it looks at face value. It is however estimated that investment could represent 40-50% of incremental GDP growth, which does put pressure on the RBA to slow other parts of the economy.
Markets
Markets remain well supported despite the fuel crisis.
Falling energy prices (for now) and lower bond yields help underpin what has been an earnings-driven rally in the US.
Anecdotes around AI investment remain supportive and the recovery in the software index adds breadth to the rally.
Falling oil and bond yields supported airlines and homebuilders last week.
Despite the rebound, overall sentiment does not look too stretched.
One issue to be mindful of is US equity supply; the combination of rising capex spend by US corporates will limit the rise in buy-backs.
At the same time an increase in IPOs, notably SpaceX, could provide a liquidity overhang, which may see some market consolidation.
The key threat to the market, in our view, would come from a softening outlook for AI spending and AI business models. That is not currently on the horizon.
The other would be a significant deterioration in the economy. This risk has diminished as the fuel shock has subsided.
The Australian market was strong last week, helped by inflation data easing concerns on rates and driving market rotation back to some of the more rate-sensitive sectors.
Discretionary stocks rose 4.6% and REITs 2.3%. We also saw tech stocks continuing to bounce, albeit nothing like what has been seen in the US. Banks continue to lag the market both for the week and the month.
The S&P/ASX 300 was up 1.3% for May.
The best-performing sectors were resources (+7.7%) and discretionary (+4.6%).
Healthcare (-8.9%) Utilities (-7.6%) and Energy (-6.0%) were the worst performers. Banks (-4.2%) also lagged.
From a stock perspective, smaller-cap names such as Megaport (MP1, +69.4%) and Sime (SGM, +29.7%) – where earnings are linked with AI demand – led the market.
Among the best-performing larger-cap names were miners (eg South32 (S32, +19.4%) BHP (BHP, +16.0%), rate-sensitives (eg Computershare (CPU, +14.6%) and fuel deflation beneficiaries (eg Qantas (QAN, +12.3%).
Among the worst performers were companies that downgraded earnings guidance, including Brambles (BXB, -26.8%), ASX (ASX, -24.05), CSL (CSL, -22.3%), Endeavour (EDV, -14.0%), Origin Energy (ORG, -10.2%).
Fuel-related names such as Viva Energy (VEA, -13.8%) and Woodside Energy (WDS, -8.6%) also underperformed.
About Crispin Murray and the Pendal Focus Australian Share Fund
Crispin Murray is Pendal’s Head of Equities. He has more than 27 years of investment experience and leads one of the largest equities teams in Australia. Crispin’s flagship Pendal Focus Australian Share Fund is a high-conviction equity fund with a two-decade track record across a range of market conditions.
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
Softer-than-expected inflation data for April has lifted hopes of a rate pause, even as services inflation stays stubbornly elevated. TIM HEXT breaks down the latest data release.
- Find out about Pendal Government Bond Fund
- Browse Pendal’s fixed interest funds
April inflation. Elevated but not accelerating.
THE ABS today released the April monthly CPI numbers. Prices compared to April 2025 (called year-on-year) were 4.2% higher, against expectations of 4.4%. This was lower than the 4.6% in March.

Non-seasonally adjusted prices were 0.4% higher than March, although closer to flat if adjusted (the ABS is still refining their seasonality for monthly numbers).
Trimmed mean inflation was 3.4% in the 12 months since April 2025, up slightly from 3.3% in March.
So overall it is fair to describe inflation as elevated but peaking.
The RBA in its recent forecast update expect headline inflation at 4.8% by the end of June and 4% by the end of the year. These may prove too high, barring new major Middle East disruptions.
What can we learn from the details?
A key focus for nearer term inflation is the so called second round impacts of fuel price increases. The RBA provided this useful graph in its recent Monetary Policy Statement:
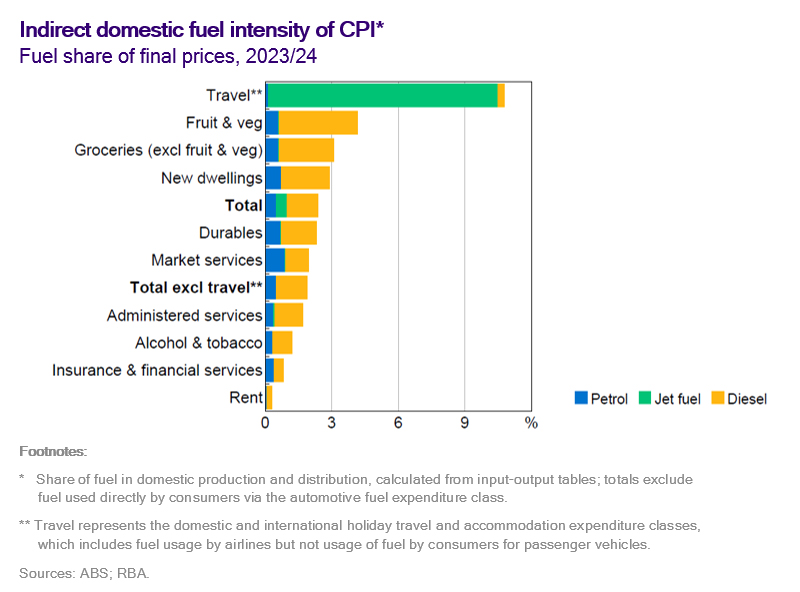
Apart from travel, the impact is limited but not zero. This was backed up by today’s numbers. Added to this, free transport in Victoria and now Tasmania (joining the 50 cent Queensland fares) saw urban transport fall by 20%.
In addition, the ABS recently did a survey of the impact of fuel increases on businesses. Nearly half have absorbed the costs, at least for now. These were the responses:

Housing and medical costs though remain worryingly elevated and leave us pessimistic that services overall will fall below 4% any time soon. For example, health insurance premiums averaged 4.4% higher in their April annual increase.
What does this mean for markets?
We get the Q2 inflation numbers in late July just ahead of the RBA meeting in August. For now, trimmed mean looks like being around 1%, following on from the Q1 result of 0.9%.
Clearly this is too high, but it would leave annual trimmed mean at 3.7%, slightly below the RBA forecast of 3.8%.
Uncertainty remains high for now courtesy of the Middle East. However, combined with the deteriorating employment and now housing outlook (post-budget) we think the RBA may be on hold for the remainder of the year.
Despite this week’s rally, with slightly less than one more hike priced in we think the bond market still offers some value.
Find out about
Pendal Government Bond Fund
Tim Hext, Head of Government Bond Strategies
If you’d like to hear more about how Pendal’s Income & Fixed Interest team is positioning for this environment, please contact us through our accounts team
About Tim Hext and Pendal’s Income & Fixed Interest boutique
Tim Hext is a Pendal portfolio manager and head of government bond strategies in our Income and Fixed Interest team.
Tim has extensive experience in banking, financial markets and funding including senior positions with NSW Treasury Corporation (TCorp), Westpac Treasury, Commonwealth Bank of Australia, Deutsche Bank, Bain & Co and Swiss Bank Corporation.
Pendal’s Income and Fixed Interest boutique is one of the most experienced and well-regarded fixed income teams in Australia.
Find out more about Pendal’s fixed interest strategies here
About Pendal
Pendal is a global investment management business focused on delivering superior investment returns for our clients through active management.
In 2023, Pendal became part of Perpetual Limited (ASX:PPT), bringing together two of Australia’s most respected active asset management brands to create a global leader in multi-boutique asset management with autonomous, world-class investment capabilities and a growing leadership position in ESG.
Get to know CHRIS LEES, a London-based senior portfolio manager with our affiliate asset manager J O Hambro
ALONG with Nudgem Richyal, Chris is a co-portfolio manager of Pendal Global Select Fund.
J O Hambro is an equities specialist asset manager with international capabilities across Global and International, UK, Europe, Asia and emerging markets.
The Pendal Global Select Fund offers access to a professionally managed portfolio of global shares and the potential for long-term capital growth.
Pendal and J O Hambro are part of Perpetual Group.
In this video, Chris discusses the team’s approach to portfolio management and how they screen new investments.
Learn more about Pendal Global Select Fund: https://pendalgroup.com/global-equities/pendal-global-select-fund
Highlights:
0.37 What type of investor has the fund been designed for?
1.17 How do you approach portfolio management?
1.57 How do you screen new investments?
Find out about
Pendal Global
Select Fund
Chris Lees & Nudgem Richyal,
Senior Fund Managers
About Chris Lees and Nudgem Richyal
Chris Lees and Nudgem Richyal are senior fund managers of Pendal Global Select Fund. The pair have been working together as investment managers for more than 20 years.
Chris has more than 32 years of investment industry experience. He joined Pendal Group’s UK-based asset manager J O Hambro Capital Management (JOHCM) in 2008 after spending 19 years at Baring Asset Management, ultimately as head of its global sector team.
Nudgem has 22 years of industry experience, joining JOHCM with Chris in 2008. He was previously an investment director with the Global Equity Group of Baring Asset Management, where he worked closely with Chris since 2001.